
Searching for the best pension plan in India can quickly turn into a comparison of interest rates, tax benefits, investment returns and monthly payouts. But those numbers do not answer the most important question: what do you need your retirement money to do?
Someone in their 30s may primarily need to build a retirement corpus. Someone approaching retirement may be more concerned about dependable income. A retired couple may care more about liquidity, healthcare costs, inflation and what happens to their spouse after one of them dies.
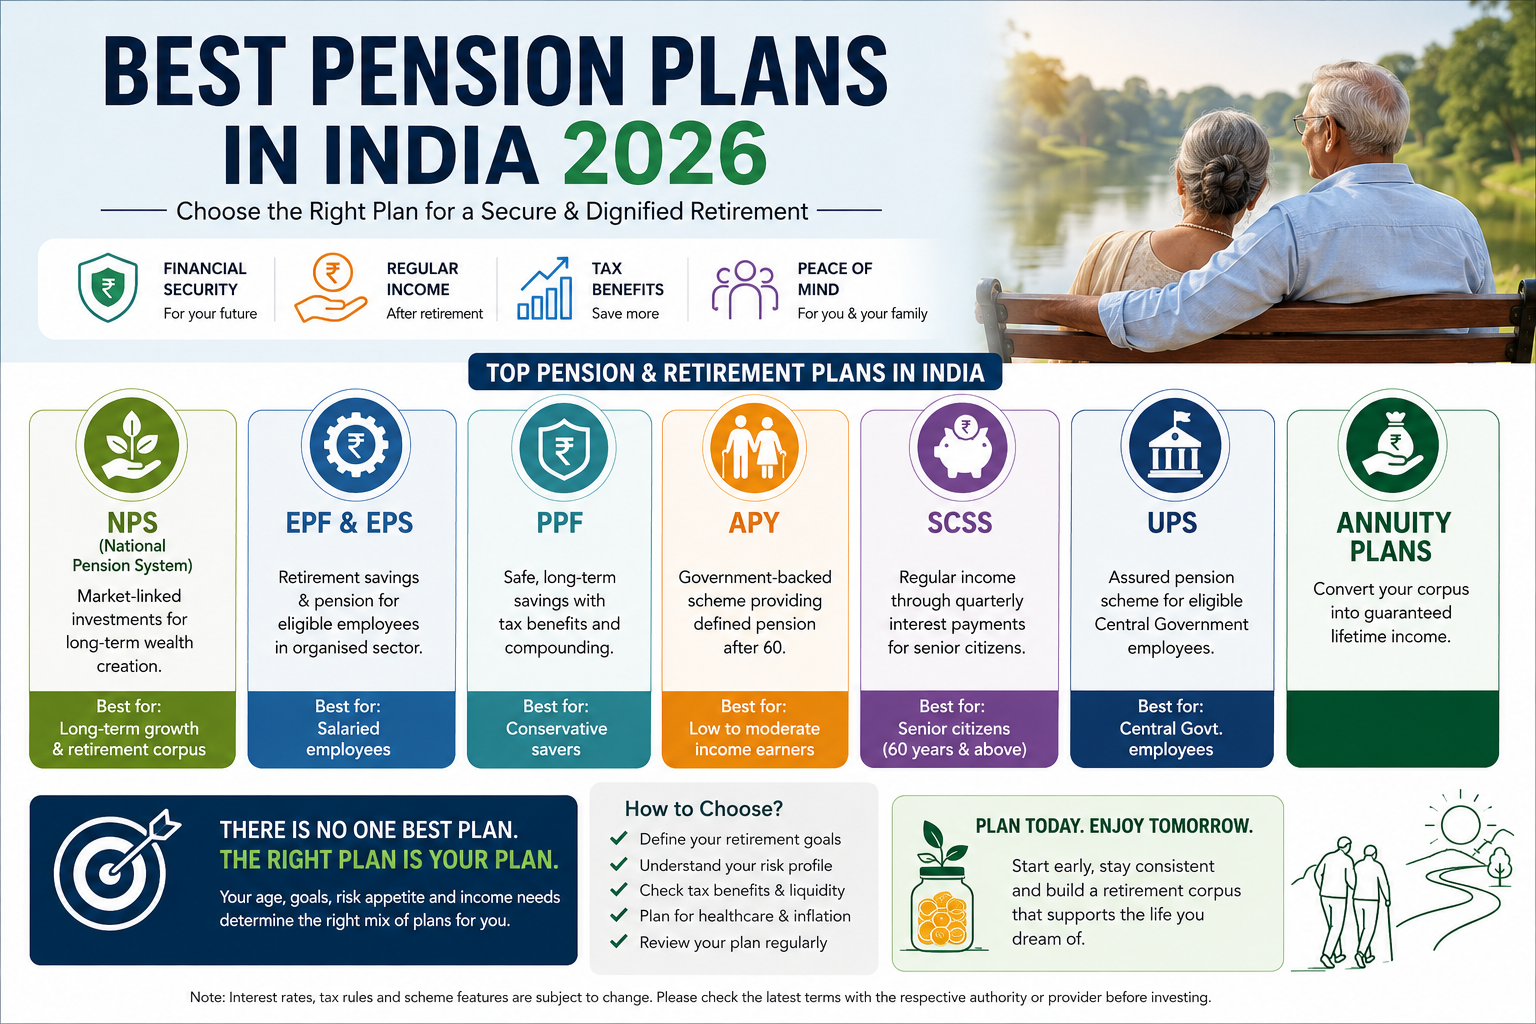
India has several retirement and pension options, including NPS, EPF/EPS, PPF, APY, SCSS, UPS and annuities. They are not interchangeable, and there is no single option that is automatically the best for everyone.
At a Glance
- There is no universal “best” pension plan. The right option depends on whether you are building a corpus, creating income or trying to balance both.
- NPS is primarily a retirement accumulation framework. It is market-linked and can form an important part of long-term retirement planning.
- SCSS is designed for eligible senior citizens seeking relatively predictable interest income.
- APY has specific age and eligibility conditions. It is not a new option for someone who is already a senior citizen.
- UPS is relevant to eligible Central Government employees. It is not a general pension scheme for the public.
- Annuities prioritise income certainty over flexibility. They can be useful for part of a retirement-income plan, but the trade-off needs to be understood.
- A combination may be more useful than one product. Retirement requires income, liquidity, growth and protection against long-term risks.
What Does “Best Pension Plan” Actually Mean?
The word “best” can mean very different things to different retirees.
For one person, the priority may be guaranteed income. For another, it may be building the largest possible retirement corpus over a long period. Someone else may place a higher value on liquidity or leaving money to family.
So instead of comparing pension plans only by return or payout, start by identifying the job the money needs to perform.
| Your Main Priority | What to Look At |
|---|---|
| Building retirement savings | Contribution structure, investment options, time horizon and growth potential |
| Regular retirement income | Pension or annuity payout, income certainty and inflation |
| Safety and predictability | Guarantees, government-backed schemes and fixed-income exposure |
| Liquidity | Withdrawal rules, lock-ins and access to capital |
| Family protection | Spouse benefits, nominee provisions and what happens after death |
Best Pension and Retirement Options in India
The following options can all appear in a retirement plan, but they solve different problems.
| Option | Broad Purpose | Best Considered For |
|---|---|---|
| NPS | Long-term retirement accumulation | People building a retirement corpus over time |
| EPF / EPS | Employment-linked retirement savings and pension benefits | Eligible employees |
| PPF | Long-term savings | People seeking a long-term conservative savings component |
| APY | Defined pension framework | Eligible subscribers within the scheme’s age and other conditions |
| SCSS | Regular interest income | Eligible senior citizens seeking predictable income |
| UPS | Retirement benefit framework for eligible Central Government employees | Eligible Central Government employees |
| Annuities | Converting a lump sum into income | Retirees seeking greater income certainty |
The applicable eligibility conditions, rates, limits and withdrawal rules can change. Always check the current official terms before making a financial decision.
1. National Pension System (NPS)
The National Pension System is a market-linked retirement savings framework regulated by the Pension Fund Regulatory and Development Authority (PFRDA).
Its primary role is accumulation: you contribute during your working years and the money is invested through the NPS framework. The eventual retirement benefit depends on the accumulated corpus, investment performance and the rules applicable when the money is accessed.
NPS can therefore be useful for someone who has a long period before retirement and wants a dedicated retirement investment structure.
What to consider before choosing NPS
- Your remaining investment horizon.
- The level of market exposure you are comfortable with.
- Your existing EPF, PPF, mutual funds and other retirement assets.
- The applicable withdrawal and exit rules.
- How the eventual corpus will be used to generate retirement income.
NPS should therefore be assessed as part of the retirement portfolio rather than as a stand-alone promise of a particular monthly pension.
2. EPF and EPS
For eligible employees, the Employees’ Provident Fund and the Employees’ Pension Scheme can already form an important part of retirement planning.
EPF and EPS should not be treated as identical. EPF represents provident-fund savings, while EPS provides pension benefits under its own eligibility and benefit rules.
For an employee who is already covered by these arrangements, the more useful question may not be whether to “buy” another pension product, but how these existing benefits fit with the rest of the retirement plan.
3. Public Provident Fund (PPF)
PPF is a long-term savings instrument rather than a traditional pension product.
It can nevertheless have a place in retirement planning, particularly during the accumulation years, because it can provide a relatively stable component within a wider portfolio.
The important distinction is that PPF helps build retirement assets. It does not automatically convert those assets into a lifelong monthly pension.
4. Atal Pension Yojana (APY)
Atal Pension Yojana is a government-backed pension scheme administered by PFRDA. It is designed around contributions during the working years and a defined pension benefit beginning at age 60, subject to the scheme’s eligibility and contribution conditions.
One important point is frequently missed in online comparisons: APY is not a scheme that a person can newly join after reaching 60. New subscribers need to meet the scheme’s age eligibility, currently requiring entry between 18 and 40.
APY can therefore be relevant to younger people planning ahead, rather than to someone who is already retired and looking for a new pension product.
5. Senior Citizens’ Savings Scheme (SCSS)
SCSS is specifically designed for eligible senior citizens and can be an important part of a retirement-income plan for people who value relatively predictable interest income.
It is important, however, to distinguish SCSS from a lifelong pension. The scheme provides interest income on the eligible investment under its prevailing rules; the underlying capital remains part of your retirement assets and must still be considered in the wider plan.
SCSS can therefore be useful for one layer of retirement cash flow while other assets provide liquidity, growth or additional income.
6. Unified Pension Scheme (UPS)
The Unified Pension Scheme is relevant to eligible Central Government employees under the applicable government framework. It should not be treated as a general pension option available to every Indian investor.
For an eligible Central Government employee, the relevant comparison may involve understanding how UPS fits against the applicable NPS framework and the individual’s service and retirement circumstances.
For everyone else, UPS should not be treated as a pension product to add to a personal retirement portfolio.
7. Annuity Plans
An annuity addresses a different stage of retirement planning. Instead of primarily accumulating wealth, you use a lump sum to purchase an income stream according to the terms of the chosen annuity.
The attraction is income certainty. Depending on the annuity selected, income may continue for life and may include provisions for a spouse or return of the purchase price.
The trade-off is flexibility. Once a lump sum is committed to an annuity, access to that capital can be much more limited than with an investment portfolio.
This makes annuities potentially useful for covering essential expenses, but they should be compared carefully with other retirement-income approaches.
Annuity or SWP: A Different Retirement-Income Decision
An annuity and a Systematic Withdrawal Plan solve the retirement-income problem in very different ways.
An annuity prioritises a defined income stream and longevity protection. An SWP keeps the underlying investment corpus under your control but leaves the retirement income exposed to investment performance and withdrawal decisions.
For some retirees, the answer may be a combination: enough guaranteed or dependable income to cover essential expenses, with a flexible investment portfolio supporting discretionary spending and longer-term needs.
GreySmiles’ Annuity vs SWP comparison explores this trade-off in more detail.
Absolutely. Here is the plain text version, in the same format as the previous section.
Tax Treatment of Pension and Annuity Income
Pension and annuity income can have tax implications during retirement. The amount you receive is not necessarily the amount you get to keep, so taxation should form part of the comparison when you are evaluating different retirement-income options.
Annuity payouts received from pension or annuity plans are generally taxable as income and are taxed according to the applicable income-tax rules and your tax slab. This means two people receiving the same annuity income may have different post-tax outcomes depending on their overall taxable income and tax regime.
The tax treatment can also differ between the accumulation phase and the payout phase. Certain pension contributions may qualify for deductions subject to the applicable rules and limits. NPS, for example, has specific tax provisions that need to be considered separately from the taxation of the eventual retirement income.
For someone already retired, the more useful comparison is therefore the post-tax income available for regular expenses, rather than simply the headline pension or annuity amount. This becomes particularly important when comparing an annuity with other sources of retirement income such as interest income or withdrawals from an investment corpus.
Tax rules and applicable limits can change over time. Before making a retirement-income decision, check the prevailing tax provisions and consider how the income fits into your overall retirement cash flow.
Tax rules can change, so check the prevailing rules when making a retirement-income decision.
How Should You Compare Pension Plans?
A comparison becomes much more useful when you stop looking at headline returns alone.
| Factor | Why It Matters |
|---|---|
| Purpose | Is the option designed for accumulation, income or both? |
| Risk | Can the value or income change with markets? |
| Income certainty | Is the future income defined, variable or dependent on investment performance? |
| Liquidity | How easily can you access your money when circumstances change? |
| Inflation | Can the income keep pace with rising living costs? |
| Spouse / survivor benefits | What happens to the income after the primary recipient dies? |
| Capital after death | Does the remaining money go to your nominee or is it retained under the product’s terms? |
| Tax treatment | How much of the stated income or return actually reaches you after tax? |
The Best Pension Plan May Be a Combination
Retirement rarely involves just one financial requirement.
You may need predictable income for essential household expenses, liquid money for emergencies, investments that can potentially grow over a long retirement and a separate provision for healthcare.
Trying to make one product perform all these jobs can create unnecessary compromises.
A more useful approach is to decide what each part of the retirement portfolio is supposed to accomplish.
Start With Your Retirement Corpus
Before deciding how much to place into any pension or income product, estimate how much your retirement may actually require.
Your retirement corpus depends on factors such as expected spending, retirement age, inflation, longevity and income that can reasonably be counted on.
The GreySmiles retirement corpus guide explains how these factors fit together.
GREYSMILES CALCULATOR
Retirement Corpus Calculator
Before comparing pension products, get an indicative sense of the corpus your retirement may require. The calculator can help you explore how your assumptions affect the estimated requirement.
Estimate Your Retirement Corpus
Illustrative planning tool. Results depend on the assumptions entered and are not a guaranteed retirement requirement.
What If You Are Already Retired?
For someone already retired, the decision is usually less about building a corpus and more about arranging the assets already available.
The key questions become:
- How much income is required each month?
- How much of that is already covered by pension or other dependable income?
- How much should remain liquid?
- How much can remain invested for longer-term needs?
- How much certainty is required for essential expenses?
- What protection does the spouse need?
This is why a retiree’s best option may be very different from the best option for someone who is 35 and still accumulating wealth.
Common Mistakes When Choosing a Pension Plan
Choosing the highest headline return. Return is only one part of retirement planning. Risk, liquidity, income certainty and inflation matter too.
Calling every retirement product a pension. NPS, PPF, SCSS and annuities perform different jobs.
Ignoring liquidity. A product can look attractive until you need access to the money unexpectedly.
Ignoring inflation. A fixed income that looks sufficient today may buy less in the future.
Forgetting the spouse. Understand what happens to income and capital after the primary account holder dies.
Putting everything into one product. Retirement usually requires a combination of safety, income, liquidity and growth.
Using outdated information. Government schemes, rates, eligibility conditions and withdrawal rules can change.
Questions to Ask Before Choosing
- Am I still accumulating retirement savings or already converting savings into income?
- How much retirement income do I actually need?
- How much dependable income do I already have?
- How much liquidity will I need?
- How much investment risk can I tolerate?
- What happens to my spouse if I die first?
- What happens to the remaining capital after my death?
- How will inflation affect the income?
- What taxes apply?
- Have I checked the latest official rules?
GreySmiles Take
The “best pension plan” is rarely the product with the highest number in a comparison table. It is the arrangement—or combination of arrangements—that solves the retirement problem you actually have. Someone building a corpus needs a different solution from someone converting savings into income, and a retiree who values certainty may make different choices from someone who prioritises liquidity and leaving capital to family.
Frequently Asked Questions
Which is the best pension plan in India?
There is no single best pension plan for everyone. NPS, EPF/EPS, PPF, APY, SCSS, UPS and annuities have different purposes and eligibility conditions. The appropriate choice depends on your age, employment, retirement horizon, income requirement, risk tolerance and existing assets.
Is NPS better than a traditional pension plan?
They are not necessarily solving exactly the same problem. NPS is primarily a market-linked retirement accumulation framework, while some pension arrangements focus more directly on defined or predictable retirement income. The comparison should be made based on the role you need the money to perform.
Is SCSS a pension plan?
SCSS is a government-backed savings scheme for eligible senior citizens that provides periodic interest income. It can be an important part of a retirement-income plan, but it is not the same as a lifelong pension.
Can I join APY after age 40?
New APY subscribers must meet the scheme’s age eligibility, which currently requires joining between 18 and 40. It is therefore not a new pension option for someone who is already over 40.
Is UPS available to everyone?
No. UPS is relevant to eligible Central Government employees under the applicable government framework. It is not a general pension product available to all investors.
Are annuities a good retirement option?
Annuities can be useful when predictable lifetime income is an important priority. Their trade-off is reduced flexibility over the capital committed to the annuity. Whether that trade-off is worthwhile depends on the retiree’s income needs, other assets and family circumstances.
Should I put all my retirement savings into a pension plan?
Not necessarily. Retirement requires different things from your money, including income, liquidity, growth and protection against unexpected expenses. A combination of suitable assets may be more appropriate than relying on one product.
Further Reading
- Pension Plans in India: How They Work and Where They Fit in Retirement Planning
- Retirement Corpus Calculation: How Much Do You Need?
- How to Withdraw From a Retirement Corpus
- Annuity vs SWP: Which Gives You More Retirement Income?
Sources & References
- Pension Fund Regulatory and Development Authority (PFRDA) — NPS, APY and pension-related information.
- Employees’ Provident Fund Organisation (EPFO) — EPF and EPS information.
- India Post — current small-savings scheme information, including SCSS and PPF.
- Insurance Regulatory and Development Authority of India (IRDAI) — information relating to annuity and pension products.
- Government of India — information relating to the Unified Pension Scheme and applicable Central Government employee provisions.
Disclaimer: This article is for educational purposes only and does not constitute financial, investment, tax or pension advice. Eligibility, interest rates, contribution limits, taxation, withdrawal rules and government scheme provisions can change. Always check the latest official information before making a financial decision.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.