
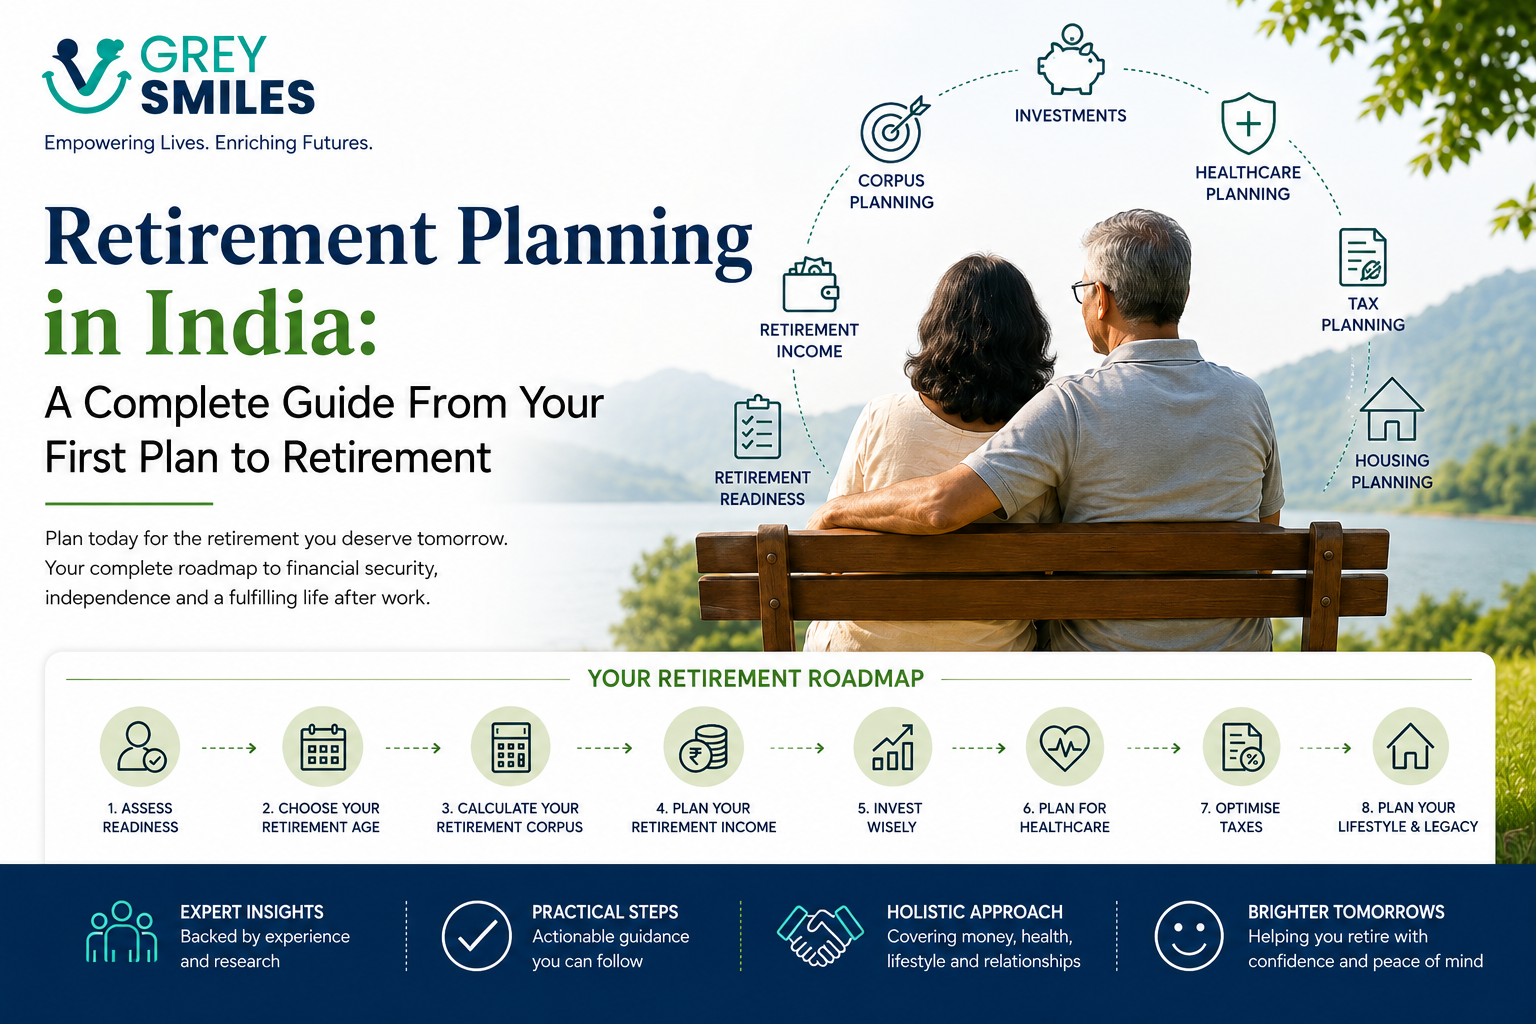
Retirement planning is not one decision you make at 55 or 60. It is a series of decisions that change as your working life changes.
When you are in your 30s, retirement can feel too far away to worry about. In your 40s, children’s education, home loans and other responsibilities may compete for attention. By your 50s, the question becomes much more immediate: Will what I have built actually support the life I want after my salary stops?
For a salaried professional, the advantage is that the journey usually leaves a trail: EPF contributions, investments, insurance, income growth and years of financial decisions. The challenge is bringing those pieces together into one coherent plan.
At a Glance
A useful retirement plan should answer seven questions:
- When might I want to stop working?
- What will my retirement actually cost?
- How much of that cost will my own assets need to fund?
- How should my investments be positioned as retirement approaches?
- How will I generate income after salary stops?
- How will I deal with healthcare, housing and family responsibilities?
- What will I actually do with the years after work?
You do not need perfect answers to all seven today. You do need to know which answer is currently weakest.
Retirement Planning Is a Moving Target
Your retirement plan at 32 should not look like your retirement plan at 52.
Early in your career, the biggest opportunity is time. You have decades for savings to compound and plenty of earning years in which to correct mistakes.
Later, the priorities change. Your retirement date becomes more concrete. Your accumulated corpus matters more. Healthcare, debt, taxes, housing and the transition from salary to investment income become harder to ignore.
That is why retirement planning should be reviewed rather than completed once.
Start With the Life You Want, Not an Investment Product
One of the easiest ways to make retirement planning unnecessarily complicated is to begin with products.
Should I invest in NPS? Should I increase my EPF? Should I buy more mutual funds? Should I use an FD?
Those are useful questions, but they come later.
First decide what the money is supposed to accomplish.
Think about where you expect to live, the lifestyle you want, whether you expect to travel, how much family support you may provide, your healthcare needs and the age at which you would ideally like work to become optional.
The clearer the destination, the easier it becomes to judge whether an investment is helping you get there.
Your First Retirement Number Is Your Spending
People often begin retirement planning by asking, “How many crores do I need?”
That is backwards.
Start with spending.
Look at what your household actually spent over the last 12 months. Then separate those expenses into broad groups:
| Expense | Question for retirement |
|---|---|
| Housing | Will you own your home, rent, downsize or move? |
| Household | Which everyday costs will continue? |
| Healthcare | What will insurance cover and what might you need to fund yourself? |
| Travel & leisure | What experiences do you actually want to afford? |
| Family support | Which commitments are likely to continue after you retire? |
| Irregular expenses | What happens when the car, home appliance or house needs a major expense? |
Do not deliberately underestimate spending simply to make the retirement number look achievable.
A realistic estimate gives you something much more useful: a retirement plan you can actually test.
For a deeper calculation of retirement spending, see How Much Will I Actually Need to Spend in Retirement?
Then Calculate the Retirement Corpus You Actually Need
Once you have an estimate of future spending, you can work backwards towards the corpus.
The calculation needs to consider:
- when you expect to retire;
- how long the money may need to last;
- inflation;
- healthcare costs;
- dependable retirement income;
- taxes and investment costs;
- your asset allocation; and
- how flexible your spending can be.
A 25× or 30× rule can provide a useful first reference point, but it is not a personalised retirement plan.
A person retiring at 55 with no pension and high spending needs a different margin of safety from someone retiring at 65 with a pension, a debt-free home and flexible discretionary expenses.
The current GreySmiles retirement corpus calculation guide goes deeper into this distinction.
GREYSMILES CALCULATOR
Put Your Retirement Numbers Together
If you are still working out how large your retirement corpus may need to be, use the GreySmiles Retirement Corpus Calculator as a starting point.
Calculate Your Retirement Corpus →
Illustrative planning tool only. Actual retirement requirements depend on your spending, income, assumptions and investment outcomes.
Do Not Count Every Asset in the Same Way
Your net worth and your retirement corpus are not necessarily the same thing.
A primary residence may be valuable but may never be sold. Jewellery may have substantial value but may not be part of your retirement-income plan. A business may be worth a lot but may not provide dependable income.
For retirement planning, ask a more practical question:
Which assets can realistically support my retirement spending?
This distinction becomes particularly important when a household looks wealthy on paper but has relatively little liquid or investable wealth available to fund retirement.
EPF Is a Starting Point, Not the Whole Plan
For salaried professionals, EPF can become one of the most useful building blocks of retirement savings because contributions happen alongside employment.
But the presence of EPF does not automatically mean retirement is funded.
Your retirement requirement may be considerably larger than your eventual EPF balance, particularly if you want to retire before the age at which your employment income would otherwise continue.
Treat EPF as one part of the retirement system and understand what other assets and income sources need to do the rest.
What Role Should NPS, PPF and Mutual Funds Play?
Different investment vehicles solve different problems.
| Vehicle | Potential role | What to consider |
|---|---|---|
| EPF / VPF | Long-term retirement savings for eligible salaried employees. | Contribution rules, employer arrangements and overall asset mix. |
| NPS | Structured long-term retirement investing. | Investment choices, withdrawal rules, tax treatment and retirement-income needs. |
| PPF | Long-term fixed-income component for eligible investors. | Lock-in, contribution limits and the role it plays within the wider portfolio. |
| Mutual funds | Potential long-term growth and diversification. | Asset allocation, volatility, time horizon and the specific role of each fund. |
The mistake is trying to identify one “best” product.
A retirement portfolio is a system. The right question is what each part is expected to do.
Asset Allocation Matters More Than Product Collecting
Someone can own EPF, NPS, PPF, five mutual funds, two FDs and gold and still have a poorly structured retirement portfolio.
Why? Because the number of products does not tell you how much risk the household is actually taking.
Look at the portfolio as a whole.
How much is exposed to growth assets? How much is relatively stable? How much is genuinely liquid? How much will you need in the next few years? What happens if equity markets fall shortly before or after retirement?
Asset allocation should change as your circumstances and time horizon change. It should not change simply because one investment product is currently fashionable.
If you are in your 30s and building long-term wealth, see Retirement Asset Allocation in Your 30s for a more detailed discussion.
The 10 Years Before Retirement Are Different
The final decade before retirement deserves a different kind of attention.
You are no longer simply trying to maximise accumulation. You are preparing for a transition.
That means asking:
- Is the projected corpus adequate?
- How much of my future spending will need to come from investments?
- What debts will remain when I retire?
- What happens to employer-provided health insurance when I leave?
- How much liquidity will I need?
- Is my portfolio taking more risk than I can comfortably absorb?
- What will my first few years of retirement income look like?
This is where retirement planning stops being an abstract future goal and becomes a transition plan.
Healthcare Cannot Be Added at the End
Healthcare is one of the areas most likely to make an otherwise comfortable retirement plan look different.
Consider not just hospitalisation, but medicines, consultations, diagnostics, dental and vision care, rehabilitation, home healthcare and expenses that insurance may not fully cover.
Employer health insurance also needs particular attention. A policy that works while you are employed may not remain available after retirement.
GreySmiles’ healthcare-cost planning guide suggests a more useful approach: distinguish between regular healthcare spending and a separate reserve for unexpected costs. :contentReference[oaicite:2]{index=2}
The broader point is simple: healthcare is part of the retirement number, not an optional addition to it.
Debt Can Change Your Retirement Date
A home loan or other debt does not automatically mean you cannot retire.
But the repayment has to fit the income you expect to have after employment stops.
A useful pre-retirement exercise is to map every major liability against its expected closure date.
If a substantial EMI will continue well into retirement, do not simply assume that investment returns will take care of it. Include the repayment in the retirement cash-flow picture.
Family Responsibilities Need a Boundary
For many Indian households, retirement planning cannot be separated completely from family.
You may still want to help children with education, a wedding, a home or another major expense. You may also be supporting parents.
That is a family decision, not necessarily a financial mistake.
The problem begins when the retirement plan assumes that these commitments will somehow disappear without calculating their cost.
Before retirement, distinguish between:
- essential retirement spending;
- planned family support;
- discretionary gifts; and
- financial commitments that you cannot realistically afford.
Your children may be an important part of your life. They should not accidentally become the retirement plan.
Retirement Income Is a Different Problem From Retirement Savings
Accumulating ₹3 crore and knowing how to use ₹3 crore are two different financial problems.
After retirement, you may have income from pension, annuity income, deposits, rental property, investments or continued part-time work. The rest may need to come from your retirement corpus.
The objective is to create a sustainable cash-flow system without putting unnecessary pressure on the corpus.
Once you reach this stage, the question changes from “How do I build wealth?” to “How do I turn wealth into income without running out?”
See How to Generate Income After Retirement in India for the next part of that journey.
Your Home Is Part of the Retirement Plan
A house can be an enormous source of security, but home ownership does not automatically solve retirement planning.
Ask whether your current home will still work for you at 70 or 80.
Think about stairs, maintenance, healthcare access, transport, neighbourhood, proximity to family and the cost of keeping the property running.
Sometimes the best retirement decision is staying exactly where you are. Sometimes it is downsizing. Sometimes it is moving closer to family or healthcare.
There is no universal answer. But housing should be a deliberate retirement decision rather than something that happens by default.
Do Not Forget the Person Who Will Retire With You
For couples, retirement is a joint financial transition even when the investment accounts are not joint.
Both spouses should understand:
- where the major investments are;
- what income is expected after retirement;
- which insurance policies exist;
- what major debts remain;
- where important documents are kept; and
- what happens financially if one spouse dies first.
A technically excellent retirement plan that only one person understands is not a robust household plan.
And Then There Is Life After Work
This is the part financial planning tends to leave until the very end.
But retirement is not simply the moment salary stops.
Work may have given you a routine, colleagues, identity, purpose and a reason to leave home every morning. When those things disappear, money cannot automatically replace them.
Think about what an ordinary Tuesday might look like after retirement.
Who will you spend time with? What will keep you curious? Will you travel, consult, volunteer, learn, exercise, build something or spend more time with family?
There does not need to be one grand answer. But having no answer at all can make the transition harder than expected.
GreySmiles’ work on purpose after retirement explores this side of the transition in greater depth.
A Better Way to Think About Retirement Readiness
At some point, the planning question changes.
You stop asking, “Am I saving enough?” and start asking, “Am I actually ready?”
That is a broader assessment.
You need to look at your spending, corpus, dependable income, healthcare, debt, housing, family responsibilities and life after work together.
The GreySmiles Retirement Readiness Test is designed for exactly this point in the journey. It is a diagnostic rather than a simple corpus calculator. :contentReference[oaicite:3]{index=3}
GREYSMILES RETIREMENT READINESS
Do You Know What Still Needs Fixing?
The GreySmiles Retirement Readiness Test looks beyond your corpus and asks about income, healthcare, debt, housing, family responsibilities and life after work.
Take the Retirement Readiness Test →
Educational planning tool only. A readiness score is not personalised financial advice or a guarantee that you can retire.
The Six Stages of the Retirement Journey
Retirement planning becomes easier to understand when you stop treating it as one giant task.
The priorities naturally change:
| Stage | Main question |
|---|---|
| Early career | How do I establish good financial habits and start building long-term wealth? |
| Building years | How do I increase savings as income and responsibilities grow? |
| Pre-retirement | Is the financial system strong enough to support the retirement I want? |
| Transition | How do I move from salary to sustainable retirement income? |
| Early retirement years | Is my spending and withdrawal plan working as expected? |
| Later retirement | How do I maintain independence, healthcare security and financial resilience? |
GreySmiles’ Six Stages of Retirement Planning explores this progression in more detail. :contentReference[oaicite:4]{index=4}
What Should You Do at Different Ages?
In Your 20s
Build the habit. Protect yourself appropriately. Start investing early enough for time to work in your favour. You do not need a perfect retirement portfolio at this stage.
In Your 30s
Increase savings as income grows. Avoid allowing lifestyle inflation to absorb every salary increase. Review your investment allocation, insurance, debt and long-term goals.
In Your 40s
Retirement should become a visible financial goal rather than a distant idea. Check whether your projected corpus is keeping pace with the life you expect to fund. Family responsibilities and debt need to be included honestly.
In Your 50s
Move from accumulation towards preparation. Stress-test the corpus, healthcare, debt, income and investment risk. Decide what retirement timing would actually look like.
Within Five Years of Retirement
Build the transition plan. Know your expected spending, dependable income, liquidity needs, healthcare arrangements and withdrawal strategy before the salary stops.
The Retirement Planning Mistakes That Matter Most
Most retirement mistakes are not caused by failing to discover a secret investment.
They are usually caused by leaving one important question unanswered.
- Saving without knowing the target: accumulating money without understanding what it needs to fund.
- Using a single corpus number: treating ₹2 crore, ₹5 crore or ₹10 crore as meaningful without considering spending and income.
- Ignoring inflation: planning with today’s expenses for a retirement that may begin years from now.
- Ignoring healthcare: assuming insurance or family support will automatically cover future medical needs.
- Taking excessive risk near retirement: forgetting that the time available to recover from a major loss is shrinking.
- Having too many products: confusing diversification with collecting investments.
- Ignoring the spouse: leaving the entire financial system dependent on one person’s knowledge.
- Planning only the money: preparing financially while giving no thought to the life that follows work.
A Simple Annual Retirement Review
You do not need to rebuild the plan every year.
A short annual review is enough to ask whether the assumptions still make sense:
- ☐ Has my expected retirement date changed?
- ☐ Has my household spending changed materially?
- ☐ Has my projected retirement corpus changed?
- ☐ Are my investments still aligned with my time horizon?
- ☐ Has my debt position changed?
- ☐ Has my health insurance or healthcare requirement changed?
- ☐ Are family responsibilities different?
- ☐ Does my spouse understand the household’s financial position?
- ☐ Are nominations and important documents up to date?
- ☐ Do I have a clearer idea of what I want life after work to look like?
The Point of Retirement Planning
Retirement planning can easily become an exercise in accumulating numbers.
How much have I saved? How much more do I need? What return am I getting? Which investment should I buy next?
Those questions matter, but they are not the destination.
The purpose of retirement planning is to create enough financial resilience that work eventually becomes a choice rather than a necessity.
That requires a corpus that matches your spending, investments that fit your time horizon, healthcare protection, manageable debt, sensible retirement income and a life after work that you have actually thought about.
You do not need to solve all of retirement today. You need to know what the next important decision is.
Further Reading
- How to Calculate Your Retirement Corpus in India
- How Much Will I Actually Need to Spend in Retirement?
- How to Generate Income After Retirement in India
- How to Plan for Healthcare Costs in Retirement
- 6 Stages of Retirement Planning in India
- Can I Retire? The GreySmiles Retirement Readiness Test
Sources & References
Retirement planning involves assumptions about inflation, investment returns, taxation, healthcare costs, longevity and future income. These assumptions should be reviewed periodically rather than treated as permanent facts.
For current rules relating to EPF, NPS, taxation, insurance and government-backed savings schemes, verify information with the relevant official authority before making a financial decision.


Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.