
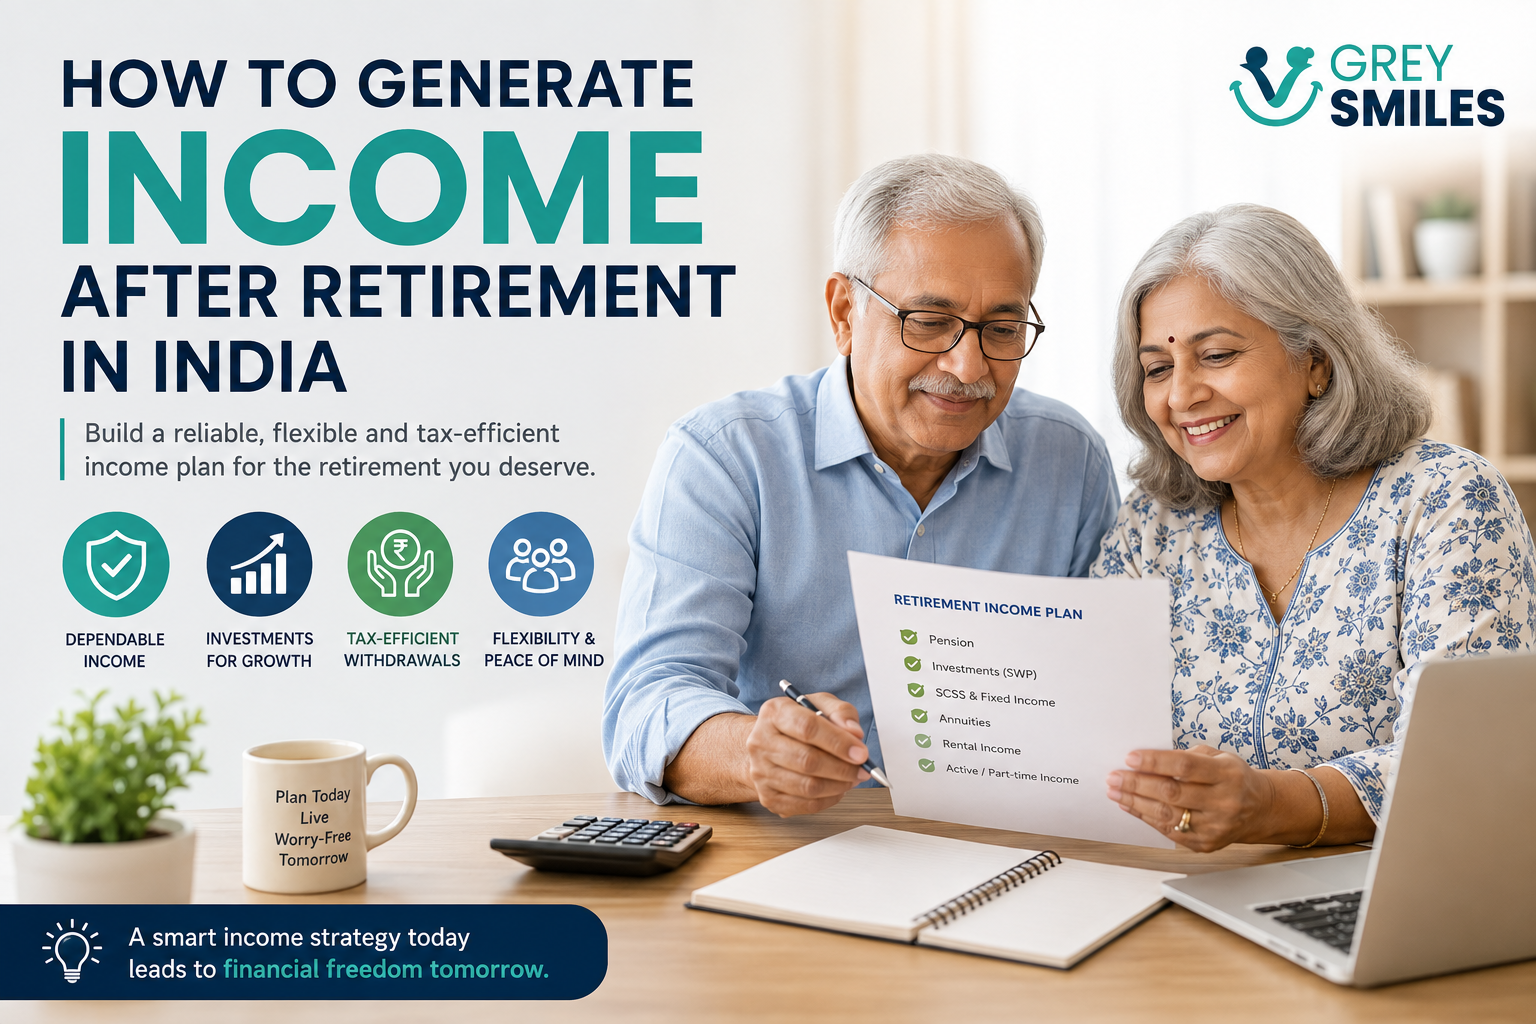
A practical approach to creating sustainable income after retirement through multiple income sources
How do you turn a retirement corpus into an income you can actually live on? That is one of the most important questions to answer before you stop working. A large corpus by itself does not guarantee financial security. You also need a plan for how much to withdraw, where your income will come from, how you will handle inflation and market falls, and what happens when healthcare or other unexpected costs rise.
At a Glance: Building Retirement Income
A resilient retirement-income plan usually combines three layers: dependable income for essential expenses, a carefully managed investment portfolio for flexibility and inflation protection, and optional active income if you want to remain professionally or socially engaged. The right combination depends on your age, spending, assets, health, other income and how long your money may need to last.
In simple terms: retirement income is not one product. It is a system.
1. Start With One Question: How Much Do You Need Each Month?
Before deciding between a Systematic Withdrawal Plan (SWP), fixed deposits, SCSS, an annuity or rental income, work out your actual retirement spending.
Separate your expenses into three groups:
- Essential: food, utilities, housing, medicines, insurance and regular household costs.
- Flexible: travel, dining, hobbies, gifts and discretionary spending.
- Irregular: major repairs, medical treatment, family support and other expenses that do not arrive every month.
This distinction matters because your entire retirement income does not need to be equally predictable. Your essential expenses should have the strongest income protection, while discretionary spending can be adjusted when markets or circumstances change.
If you have not yet worked out your target corpus, start with Grey Smiles’ Retirement Readiness Test and our guide to retirement corpus planning.
2. Think in Three Layers of Retirement Income
Layer 1: Dependable income for essential expenses
This is the income you can reasonably expect regardless of market conditions. It may include a pension, annuity income, interest from selected fixed-income investments or other relatively predictable sources.
The objective is not to maximise returns. It is to make sure that a market correction does not immediately threaten your ability to pay for food, housing and healthcare.
Layer 2: Portfolio income for flexibility and growth
Your investment portfolio can provide the second layer of income. This may involve withdrawing periodically from mutual funds or other investments rather than keeping the entire retirement corpus in fixed-income products.
An SWP allows an investor to redeem a specified amount at regular intervals. However, an SWP is not a guaranteed pension: units are being redeemed, and the value of the remaining portfolio can rise or fall with the underlying investments. The tax treatment also depends on the type of fund and the gains realised.
The important question is therefore not simply, “How much can I withdraw every month?” It is “How much can I withdraw while giving the remaining portfolio a reasonable chance of supporting me for decades?”
Layer 3: Optional active income
Some retirees want to continue earning, not because their retirement plan has failed, but because they enjoy working, teaching or contributing their experience.
Depending on your skills and energy, possibilities include consulting, mentoring, teaching, writing, freelancing, advisory work or a small business. The advantage is that active income can reduce pressure on your investment corpus while also providing structure, purpose and social connection.
3. Where Can Retirement Income Come From?
There is no universally best retirement-income vehicle. Each source solves a different problem.
| Income source | Best suited for | Key consideration |
|---|---|---|
| Pension | Essential household expenses | Predictability and adequacy of income |
| SCSS and other fixed-income options | Dependable income | Interest rates, limits, taxation and changing rules |
| Bank deposits | Capital stability and liquidity | Interest rates, tax and reinvestment risk |
| Mutual-fund withdrawals | Flexible long-term income | Market risk, withdrawal rate and taxation |
| Annuities | Lifetime income needs | Liquidity, payout structure and inflation risk |
| Rental income | Additional recurring income | Vacancies, maintenance, taxes and property concentration |
| Consulting or part-time work | Additional income and engagement | Health, demand and willingness to continue working |
The key principle is diversification of income sources, not collecting as many financial products as possible. SEBI’s investor education material similarly emphasises diversification, retirement planning and considering inflation and future expenses when planning for retirement. SEBI’s retirement-planning resources can be useful for readers who want to explore the basics further.
4. How Much Should You Withdraw From Your Corpus?
This is where many retirement plans become too simplistic. A fixed withdrawal percentage cannot guarantee that a portfolio will last for every retiree.
Your sustainable withdrawal depends on factors such as:
- your age when you retire;
- how long the money may need to last;
- your annual spending;
- asset allocation and portfolio risk;
- inflation;
- taxes;
- healthcare costs; and
- what happens to markets during the first few years of retirement.
Rather than treating 4% or 5% as a universal rule, use a withdrawal rate as a planning assumption that should be stress-tested. A retiree with a long horizon and limited guaranteed income may need to begin more conservatively than someone with a substantial pension covering most essential expenses.
SEBI also provides retirement-planning tools, including an Annual Retirement Income Calculator and Retirement Investment Tracker, which can help readers think through the relationship between corpus and income.
5. What Happens When Markets Fall?
A retirement portfolio faces a different challenge from an accumulation portfolio. During your working years, a market fall can be uncomfortable but you may still have salary income and time to recover. After retirement, you may be withdrawing money while the portfolio is falling.
This is why keeping some near-term expenses outside volatile investments can be useful. One approach is a bucket strategy: maintain a relatively liquid bucket for near-term spending, a more stable bucket for medium-term needs and a growth-oriented bucket for longer-term expenses.
The exact allocation should reflect your circumstances rather than a fixed formula. The objective is to avoid being forced to sell growth assets simply because you need money for next month’s expenses.
6. Don’t Forget Taxes
Retirement income can come from several different sources, and they may not all be taxed in the same way. Interest, pension, rental income, capital gains and professional income can have different tax treatment.
That makes the order and timing of withdrawals important. A retiree with multiple investments should review the tax consequences before making a large redemption or restructuring income sources.
Tax rules change, so avoid building a retirement plan around a tax rate or deduction remembered from a previous financial year. For significant withdrawals, property transactions or consulting income, confirm the current rules with a qualified tax professional.
7. Build Healthcare Into the Income Plan
Healthcare should not be treated as an afterthought or simply deducted from whatever remains at the end of the year.
Keep health insurance and a separate liquid medical buffer in your retirement plan. Insurance can reduce the financial impact of major hospitalisation, but policies still have exclusions, deductibles, waiting periods and other conditions that need to be understood.
IRDAI notes that health insurance policies can be lifelong renewable when renewed without a break, subject to the applicable policy and regulatory conditions. It also provides information on health insurers and health-insurance regulations. IRDAI’s health-insurance resources are a useful starting point.
For a deeper look at retirement healthcare costs, see Grey Smiles’ Healthcare Budgeting for Retirement.
8. A Simple Retirement-Income Framework
Before retiring, try answering these five questions:
- What is our essential monthly spending?
- How much of that spending is covered by dependable income?
- How much will need to come from our investment portfolio?
- How will we fund large healthcare or unexpected expenses?
- What will we change if markets fall sharply?
If you cannot answer these questions, the problem may not be that your corpus is too small. Your retirement-income plan may simply be incomplete.
9. Should You Continue Working After Retirement?
Retirement does not have to mean a complete stop.
For some people, consulting, teaching, mentoring or a small venture can provide useful supplementary income. More importantly, it can preserve routine, purpose and social interaction.
The choice should be voluntary. Your basic retirement plan should not depend on being healthy enough to work indefinitely. Active income is best viewed as an additional layer of flexibility rather than something you must earn to make retirement work.
Frequently Asked Questions
What is the best way to generate income after retirement?
There is no single best method. A combination of dependable income, appropriately managed investments and, where desired, active income can provide greater flexibility than relying entirely on one source.
Is an SWP a good option for retirees?
An SWP can provide regular withdrawals from mutual-fund investments, but it is not guaranteed income. The sustainability of withdrawals depends on the portfolio, withdrawal amount, market performance, taxes and retirement horizon.
Should retirees keep all their money in fixed deposits?
Fixed deposits can provide predictability, but keeping the entire retirement corpus in fixed-income products can create inflation and reinvestment risks. The right mix depends on your spending needs, other income, risk tolerance and time horizon.
How much retirement income should come from guaranteed sources?
There is no universal percentage. A useful starting point is to consider how much dependable income you need to cover essential expenses. The greater the gap, the more important it becomes to manage your investment withdrawals carefully.
Can I generate income through consulting after retirement?
Yes. Consulting, mentoring, teaching and freelance work can provide supplementary income and continued engagement. However, treat the income as variable unless you have a reliable contractual arrangement, and check the applicable tax rules for your situation.
The Bottom Line
A retirement corpus is only half the equation. The other half is knowing how that money will support your life year after year.
A strong retirement-income plan starts with essential spending, builds a dependable base, uses investments for long-term flexibility and growth, keeps a healthcare buffer, accounts for taxes and has a clear response to market downturns.
You do not need to find one perfect financial product. You need a system that can adapt as your expenses, health, markets and priorities change.
If you are still building that system, begin with the Grey Smiles Retirement Readiness Test, then explore how much retirement corpus you may need before deciding how that corpus should generate income.
Important disclaimer: This article is for general educational purposes only and does not constitute investment, financial or tax advice. Retirement-income strategies depend on individual circumstances, risk tolerance, health, longevity, taxation and the specific investments held. Investment values can rise or fall, and past performance does not guarantee future results. Check current rules and consult a SEBI-registered investment adviser or appropriately qualified professional before making significant financial decisions.


Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.