
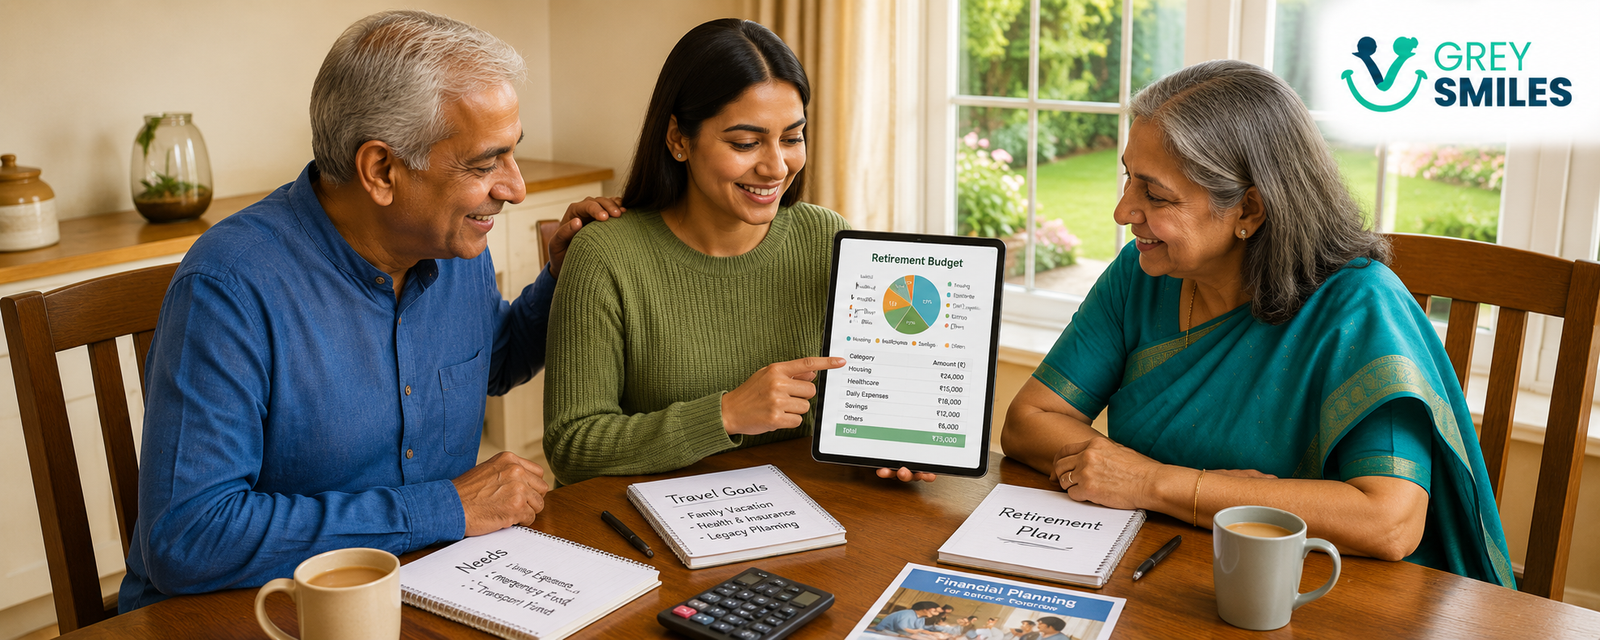
If you are in your 20s, retirement may seem like something far away. But your parents’ retirement may be much closer, and you may already be wondering whether they have enough money, adequate healthcare cover, or a realistic plan for life after work.
Helping your parents plan for retirement does not mean taking control of their money or making every financial decision for them. Your role can be much simpler: start the conversation, understand their plans, help them organise the numbers, identify gaps and support better decisions.
At a Glance
You do not need to be a financial expert to help your parents plan for retirement. Start by understanding what they want retirement to look like, when they expect to stop working and what they expect their monthly expenses to be.
Then help them make a simple inventory of their income, savings, investments, property, insurance, debts and other financial commitments. The objective is not to judge their choices but to understand whether their resources are likely to support the retirement they want.
Healthcare, housing and regular living expenses deserve particular attention because retirement planning is about more than building a corpus. Your parents also need a plan for generating income, managing medical costs and dealing with unexpected expenses.
Most importantly, keep your parents involved in every decision. You are there to support them, not take over their finances. A regular family conversation can make retirement planning less stressful and help everyone understand what needs to happen next.
GreySmiles Take: One of the most useful things an adult child can do is help parents move from vague questions such as “Will we have enough?” to a clearer picture of what they have, what they need and what gap, if any, needs to be addressed.
In This Article
Start the Conversation |
Understand Their Retirement Vision |
Build a Financial Picture |
Check Retirement Income |
Review Savings and Investments |
Plan for Healthcare |
Think About Housing |
Build a Retirement Budget |
Help Without Taking Over |
Review the Plan Regularly |
Practical Checklist |
FAQs
1. Start the Retirement Conversation
Talking to parents about retirement can feel awkward. Money is often personal, and some parents may see questions about their finances as criticism or interference.
The easiest way to begin is not to ask, “Do you have enough money to retire?” Instead, start with their plans.
Ask what they would like their life to look like after they stop working. Would they like to travel, spend more time with family, pursue hobbies, move to a smaller home or simply enjoy a slower routine?
Once the conversation is about their goals rather than their money, it becomes much easier to discuss the financial side of retirement.
Questions You Can Ask
- When do you expect to retire?
- What would you like your retirement years to look like?
- Where would you like to live?
- What expenses do you expect to continue after retirement?
- Are there any major expenses you are planning for?
- What concerns you most about retirement?
The answers will give you a starting point for the rest of the discussion.
2. Understand What Your Parents Want From Retirement
There is no single definition of a comfortable retirement. For one couple, it may mean staying in their existing home and spending time with grandchildren. For another, it may involve travel, relocation or pursuing interests they did not have time for while working.
This matters because the amount they need in retirement depends heavily on the lifestyle they want to maintain.
Encourage your parents to distinguish between essential expenses and lifestyle expenses. Housing, food, utilities, medicines and insurance may be essential. Travel, hobbies and large discretionary purchases may be flexible.
This does not mean cutting everything enjoyable. It simply helps the family understand which expenses are non-negotiable and which can be adjusted if circumstances change.
3. Help Build a Simple Financial Picture
Before discussing whether your parents are financially ready for retirement, help them gather the basic numbers.
| What to Check | Examples |
|---|---|
| Income | Salary, pension, rent, interest and other regular income |
| Savings | Bank deposits, emergency savings and other liquid money |
| Investments | EPF, PPF, NPS, mutual funds, bonds, FDs and other investments |
| Property | Home and other property, including assets intended to generate income |
| Liabilities | Home loans, personal loans, credit-card balances and other obligations |
| Insurance | Health insurance and other relevant protection |
You do not need a complicated spreadsheet to begin. Even a simple document listing these items can reveal gaps or areas that need further investigation.
If your parents have complicated finances, significant investments or substantial assets, consider involving a qualified financial professional rather than trying to make decisions yourself.
4. Check Where Retirement Income Will Come From
A retirement corpus is useful only if it can support spending over time. Help your parents identify the income they are likely to have after they stop working.
Depending on their circumstances, this may include:
- Pension income
- EPF or other retirement benefits
- NPS-related retirement income
- Interest from deposits and other fixed-income investments
- Rental income
- Systematic withdrawals from investments
- Other regular sources of income
The next question is whether these sources are likely to cover their essential monthly expenses.
If there is a gap, that does not automatically mean the retirement plan has failed. The family can explore different options, including increasing savings before retirement, reducing discretionary expenses, adjusting the retirement date, generating additional income or reviewing the way assets are allocated.
5. Review Their Savings and Investments
You do not need to tell your parents which investment to buy. A more useful role is to help them understand what they already own and why they own it.
Ask whether they know:
- How much they have invested.
- What each investment is intended to achieve.
- How much risk each investment carries.
- When the money may be needed.
- What taxes or charges may apply.
- How the investments will contribute to retirement income.
Parents approaching retirement may also need to consider whether their overall portfolio has an appropriate balance between growth and stability. The right allocation depends on their circumstances, risk tolerance, income requirements and time horizon.
Avoid making investment changes simply because an investment has recently performed well or because someone in the family recommends it.
If you want to understand how different retirement investments fit together, see our guide to mutual funds for retirement and our broader retirement planning guide.
6. Make Healthcare Part of the Retirement Plan
Healthcare deserves its own conversation because medical expenses can become a significant part of later-life spending.
Start by understanding what health insurance your parents currently have, who is covered, the sum insured, renewal terms and any important exclusions or limitations.
Also discuss how they would manage expenses that are not fully covered by insurance.
This is particularly important if one or both parents have existing medical conditions or expect healthcare needs to increase with age.
Our guide on health insurance after 60 can help you work through the questions to ask before buying or renewing cover.
Family conversation worth having: Ask your parents where they would prefer to receive care if they needed significant medical or nursing support in the future. Discuss who would help, where they would live and how the costs would be managed. These conversations can be uncomfortable, but they are easier to have before a crisis.
7. Discuss Housing and Where They Want to Live
The family home can be one of your parents’ largest assets, but it is also where they live. It should therefore not automatically be treated as money available for retirement spending.
Talk about whether they expect to remain in their current home throughout retirement.
Questions worth considering include:
- Is the home suitable for them as they grow older?
- Will maintenance become difficult or expensive?
- Is it close enough to healthcare and essential services?
- Would they prefer to move closer to children or other family?
- Would downsizing eventually make sense?
These are lifestyle decisions as much as financial decisions. Your parents should remain at the centre of them.
8. Build a Realistic Retirement Budget Together
Once you have a clearer picture of their income, assets and goals, help them estimate what retirement may actually cost.
Start with their current monthly spending and separate it into three broad categories:
| Category | Examples |
|---|---|
| Essential | Food, utilities, housing, medicines, insurance and essential transport |
| Lifestyle | Travel, dining out, hobbies, entertainment and gifts |
| Irregular | Home repairs, medical emergencies, major purchases and other occasional expenses |
Then consider how these expenses may change after retirement.
Some expenses may disappear, such as commuting costs. Others may increase, particularly healthcare, travel or spending on activities that replace work.
Building the budget around actual spending is generally more useful than choosing an arbitrary percentage of pre-retirement income.
9. Help Without Taking Over Their Finances
This may be the most important part of the process.
Your parents have spent decades making their own financial decisions. Even when you believe a particular decision is better, they may not want their children managing their money.
Try to make your role one of support rather than control.
You can help by:
- Organising financial documents.
- Creating a simple list of accounts and investments.
- Helping compare information from reliable sources.
- Making appointments with financial or legal professionals when appropriate.
- Helping them understand unfamiliar financial terms.
- Keeping a record of important renewal and review dates.
But major financial decisions should remain with your parents while they are capable of making them themselves.
This approach can also reduce future confusion for the family because everyone understands where important documents and financial information are kept.
10. Reassess the Retirement Plan Regularly
Retirement planning is not something that can be completed once and forgotten.
Income, expenses, investments, health, family circumstances and housing needs can all change.
A simple annual family review can cover:
- Current monthly spending
- Investment values and asset allocation
- Retirement income
- Health insurance
- Major upcoming expenses
- Loans and liabilities
- Important financial and legal documents
- Changes in your parents’ retirement goals
The review does not have to become a formal financial meeting. A short conversation once or twice a year may be enough to identify something that needs attention.
Practical Checklist: How to Help Your Parents Plan for Retirement
If you are not sure where to begin, work through these steps one at a time.
- Start a conversation about what your parents want from retirement.
- Find out when they expect to retire and whether that date is flexible.
- List their income sources and likely retirement income.
- List savings, investments and property without immediately judging them.
- Identify debts and ongoing financial commitments.
- Review health insurance and discuss how uncovered healthcare costs would be handled.
- Build a realistic retirement budget based on actual spending.
- Identify any gap between expected retirement income and expenses.
- Discuss housing and future care preferences before they become urgent decisions.
- Agree on a regular review so the plan stays current.
Don’t try to solve everything in one weekend. If your parents have never discussed retirement openly, simply getting the conversation started is meaningful progress. Work through the financial picture gradually and bring in qualified professionals where the situation requires specialist advice.
FAQs: Helping Parents Plan for Retirement
How can I help my parents plan for retirement?
Start by understanding their retirement goals, expected retirement age, income, expenses, savings, investments, insurance and debts. Then help identify any gap between the lifestyle they want and the resources available to support it.
Should I manage my parents’ investments for them?
Not necessarily. Your role can be to help them understand their investments, organise information and find qualified professional advice where needed. Parents who are capable of making their own financial decisions should remain involved in those decisions.
What financial information should I know about my parents?
You should understand the broad picture rather than necessarily having access to every transaction. This includes their income, savings, investments, property, liabilities, insurance and major financial commitments. Important documents and account information should also be organised so they can be accessed when genuinely needed.
How much money do parents need for retirement?
There is no single amount that works for every family. The requirement depends on expected expenses, retirement age, life expectancy, inflation, healthcare needs, income sources, assets and the lifestyle they want to maintain.
Should I encourage my parents to invest more aggressively before retirement?
Not simply because they are behind on their retirement goals. Investment risk should be considered alongside their time horizon, financial capacity, income needs and ability to withstand losses. If the situation is complex, professional financial advice may be appropriate.
What should we discuss besides money?
Discuss where your parents want to live, healthcare preferences, how they want to spend their time, whether they expect to continue working, and what kind of family support they would want if their circumstances changed.
The Bottom Line
Helping your parents plan for retirement is not about becoming their financial manager. It is about helping them have the conversations that may otherwise be postponed.
Start with their vision for retirement. Then understand the numbers: income, expenses, savings, investments, property, insurance and liabilities. From there, you can help them identify gaps and decide whether anything needs to change.
Most importantly, keep the process collaborative. A parent who feels supported rather than judged is much more likely to have an open conversation about money, healthcare and the future.
You may not be able to plan your parents’ retirement for them. But you can help them plan it better.
Further Reading
- Ultimate Retirement Planning Guide for Indian Salaried Professionals
- Health Insurance After 60
- Selecting the Best Mutual Funds for Retirement
- Retirement Readiness Test
Disclaimer: This article is intended for general information and educational purposes. Personal financial, investment, insurance, legal or tax decisions should be based on individual circumstances and, where appropriate, advice from a qualified professional.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.