
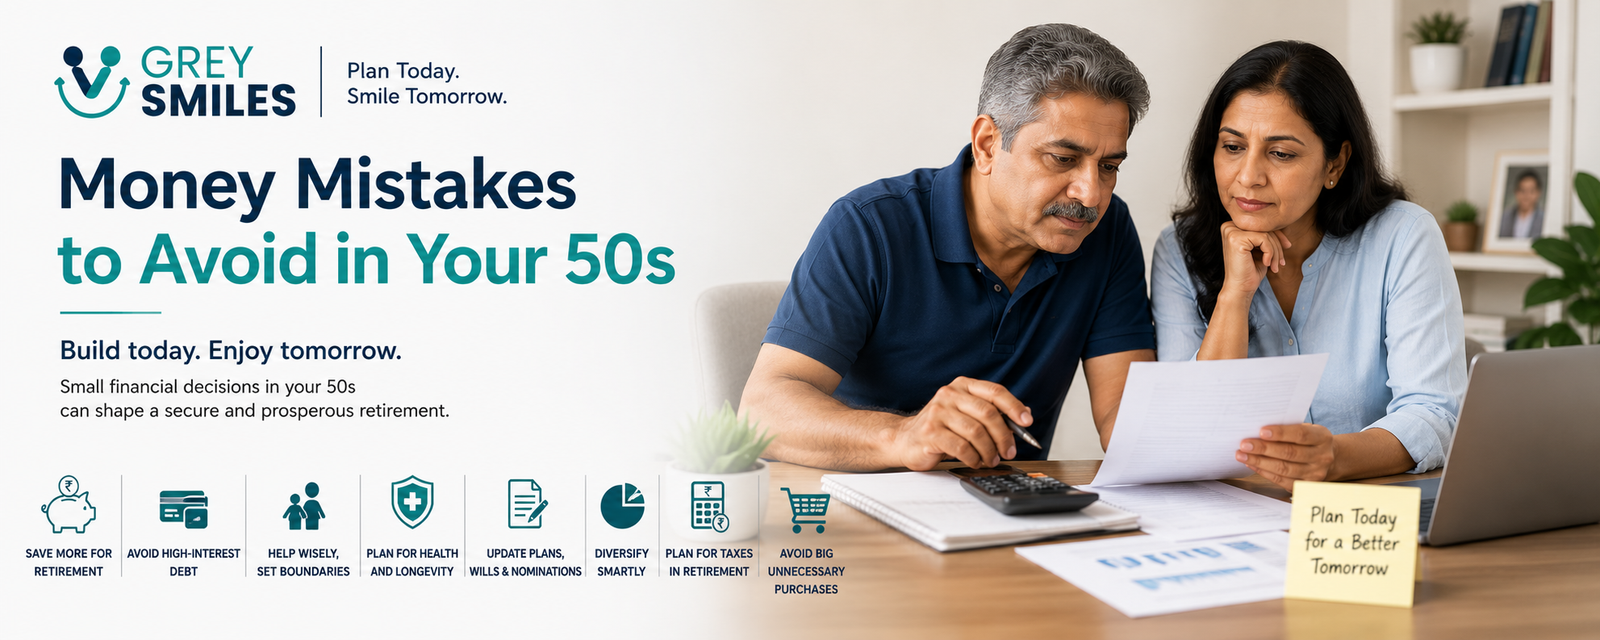
Your 50s are a crucial decade for fine-tuning your finances and preparing for retirement.
Your 50s are a crucial decade for setting yourself up for financial security in retirement. Here are the money mistakes to avoid in your 50s for a prosperous life. In this post we will discuss the money mistakes to be avoided in later years of your life.
At a Glance: Money Mistakes to Avoid in Your 50s
- Don’t neglect retirement savings: Your 50s may be among your most important earning and saving years.
- Reduce high-interest debt: Credit cards and expensive personal loans can significantly affect your retirement readiness.
- Set boundaries when helping adult children: Supporting family should not come at the cost of your own financial security.
- Plan for healthcare and longevity: Retirement may last 25–30 years or more, making healthcare and longevity important planning considerations.
- Keep financial documents updated: Review your financial plan, wills, beneficiaries and investment strategy as circumstances change.
- Diversify: Balance growth and preservation rather than putting your retirement corpus into a single asset or investment.
- Plan for taxes: Understand how different retirement income and withdrawals may affect your tax liability.
- Avoid unnecessary large purchases: Major discretionary spending in your 50s can reduce the resources available for retirement.
Your 50s are not the time to panic about retirement. They are the time to fine-tune your retirement plan, identify gaps and make the adjustments that can improve your financial security for the years ahead.
Some of the most common mistakes people make are neglecting retirement savings, carrying high-interest debts, helping adult children too much, ignoring health and associated costs, failing to update financial plans & wills, not planning for longevity, failing to diversify investments, not planning for taxes in retirement and making big unnecessary purchases.
1. Neglecting Retirement Savings
Maximize contributions to Mutual Funds and invest in your EPF / PPF and other retirement accounts that you may have. You can enhance your EPF contributions for better compounding, save tax, earn interest of around 8% (+- 0.25%) and benefit from a relatively secure retirement savings vehicle.
For current EPF rules and contribution-related information, check the official Employees’ Provident Fund Organisation (EPFO) website. For PPF and other small savings schemes, the National Savings Institute provides official information.
If you are in your 50s, it is also useful to revisit your overall retirement asset allocation rather than simply increasing contributions without considering how the money is invested.
2. Carrying High-Interest Debt
Credit card balances and personal loans can eat away at your savings. Make a plan to pay off these debts ASAP so your money can work for you, not your lenders.
High-interest debt is particularly important to address as retirement approaches because debt repayments can continue eating into income that could otherwise support your retirement lifestyle.
3. Helping Adult Children Too Much
Supporting kids financially can drain your retirement funds. It’s okay to help, but set clear boundaries—remember, there’s no “retirement loan” available.
Helping children with education, housing or other major expenses can be meaningful, but your own retirement security should remain part of the decision. Once your working years are over, rebuilding a depleted retirement corpus may be difficult.
The GreySmiles Thumb Rule
In your 50s, your retirement security should not be sacrificed to meet every financial demand around you. Help family where you can, but first make sure your own retirement needs, healthcare and essential expenses are adequately funded.
4. Ignoring Health Care Costs
Don’t underestimate future medical expenses. Consider long-term care insurance and review your health coverage to avoid unpleasant and costly surprises later.
Healthcare can become a significant retirement expense, particularly when retirement lasts for several decades. Review your existing health insurance and understand what it does and does not cover. The Insurance Regulatory and Development Authority of India (IRDAI) is the official regulator for insurance in India.
You can also review GreySmiles’ practical guidance on health insurance after 60 as part of your retirement preparation.
5. Failing to Update Financial Plans & Wills
Life changes—so should your financial documents. Regularly review and update your estate plan, beneficiary designations, and investment strategy to align with your current needs and goals.
Your 50s are a good time to check whether your overall retirement strategy, nominations, insurance arrangements, investments and estate-planning documents still reflect your current family circumstances.
6. Underestimating Longevity
People are living longer than ever! Don’t plan for retirement as if it will last only 10-15 years—you may need income for 25-30 years or more. Adjust your planning accordingly.
Longevity risk is one of the most easily overlooked retirement risks. Your retirement corpus may need to support not only your regular living expenses but also inflation, healthcare and unexpected costs over a long period.
This is why retirement wealth diversification matters: different parts of your portfolio can serve different purposes as your needs evolve through retirement.
7. Failing to Diversify Investments
At this stage, your portfolio should balance growth and preservation. Avoid putting all your eggs in one basket—diversify across stocks, bonds, and other assets to reduce risk.
Being in your 50s does not necessarily mean eliminating growth assets. Inflation can continue to erode purchasing power during a long retirement, so the objective is to find an appropriate balance between growth, stability, income and liquidity.
Read more about portfolio diversification and beating inflation.
8. Not Planning for Taxes in Retirement
Taxes won’t vanish after you stop working. Consider how withdrawals from different accounts like Mutual Funds, NPS, Bonds, Fixed Deposits etc will affect your tax bill in retirement. Take the help of financial planner and tax consultant.
Different retirement income sources can have different tax treatment. Before retirement, it is worth understanding how your expected income, withdrawals and investments may affect your post-tax cash flow.
For information on current income-tax rules and provisions, refer to the official Income Tax Department website.
9. Making Big Unnecessary Purchases
Now’s not the time to overspend on luxury cars, expensive vacations, or a second home that stretches your budget. Focus on experiences and purchases that support your long-term goals.
A major purchase in your 50s should be evaluated not only on whether you can afford it today, but also on how it affects your retirement corpus, future cash flow and financial flexibility.
Preparing for a More Secure Retirement
Your 50s are all about fine-tuning your financial habits for lasting peace and security. Avoiding these common mistakes will help ensure your financial foundation is strong for the years ahead.
Prioritizing your own financial health in your 50s will ensure peace of mind and a comfortable, prosperous retirement!
Frequently Asked Questions
1. What are the biggest money mistakes to avoid in your 50s?
Some of the most important mistakes include neglecting retirement savings, carrying high-interest debt, over-supporting adult children, underestimating healthcare and longevity costs, failing to diversify, ignoring taxes and making large unnecessary purchases.
2. Is it too late to start saving for retirement in your 50s?
No. While starting earlier provides more time for compounding, your 50s can still be an important period for increasing savings, reviewing investments, reducing debt and identifying retirement planning gaps.
3. Should I still invest in equities in my 50s?
Your 50s do not automatically mean that you should eliminate equity investments. The appropriate allocation depends on your retirement timeline, risk tolerance, existing corpus and expected income needs. The objective is generally to balance growth with capital preservation.
4. Should I help my adult children financially before retirement?
Helping adult children can be part of family financial planning, but it should not compromise your own retirement security. Set clear boundaries and consider the long-term impact of significant financial support on your retirement corpus.
5. How much should I plan for healthcare in retirement?
There is no universal amount because healthcare needs and costs vary widely. However, retirement planning should account for rising medical expenses, adequate health insurance and the possibility of significant healthcare costs later in life.
6. Why is longevity important when planning retirement?
A retirement plan needs to account for the possibility of living 25–30 years or more after leaving full-time work. Underestimating longevity can result in a retirement corpus that runs out earlier than expected.
7. Should I pay off debt before retirement?
Reducing high-interest debt before retirement can strengthen financial security because fewer retirement resources will be required for debt repayments. The appropriate strategy depends on the type of debt, interest rate, available savings and overall financial situation.
8. Should I review my will and financial plan in my 50s?
Yes. Your 50s are a useful time to review your will, nominations, beneficiaries, insurance, investments and broader financial plan, particularly after major changes in family circumstances or assets.
9. What is the most important financial priority in your 50s?
The priority is to understand whether your current savings, investments, insurance, debt and expected income are sufficient to support the retirement lifestyle you want. Your 50s are an opportunity to identify gaps and make adjustments while you still have earning years ahead.
Disclaimer: This article is intended for general information and educational purposes. Investment, insurance and tax rules can change, and readers should consider their individual circumstances and seek appropriate professional advice where required.


Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.