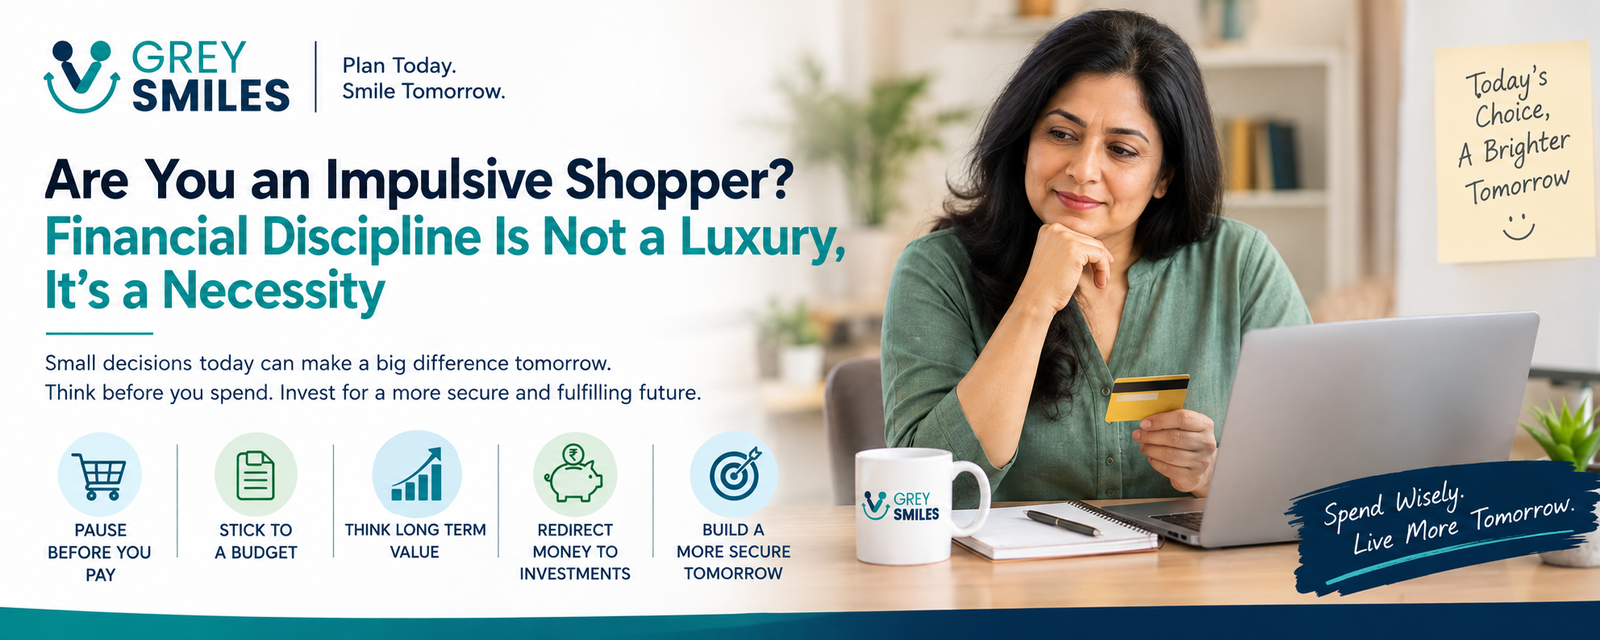
A pause before an impulse purchase can protect today’s savings and tomorrow’s financial goals.
In today’s fast-paced, consumer-driven environment, the temptation to make unnecessary purchases, be it the latest smartphone, branded clothes, fancy car or gadgets, is stronger than ever. Impulsive big-ticket purchases that you regret later should be avoided because they instantly erode your savings cushion and create opportunity costs. Money spent on a fleeting thrill can no longer earn returns for your home, education, or retirement goals; such buys often depreciate quickly, may incur high-interest debt if financed, and add stress that undermines long-term financial security and freedom, while reinforcing a harmful habit loop of emotional spending that’s hard to break.
At a Glance: Controlling Impulse Spending
- Pause before buying: Give yourself time to distinguish between a genuine need and a temporary desire.
- Set a discretionary spending limit: A budget gives you room to enjoy your money without allowing impulse purchases to take over.
- Track your spending: Awareness of where your money goes can help build better financial habits.
- Think about opportunity cost: Money spent today cannot simultaneously be invested for tomorrow.
- Redirect surplus money: Regular investments in suitable instruments can turn small amounts into meaningful long-term wealth.
- Financial discipline matters: Especially when you have responsibilities such as children’s education, family support and retirement planning.
What is the Real Cost of Impulse Buying?
When you spend money on things you don’t truly need, you’re not just missing out on savings; you’re also sacrificing the opportunity to create wealth for your future. A Rs 5,000 splurge on an unplanned shopping trip may seem harmless today, but if you repeatedly indulge, you lose out on the power of compounding, which is the bedrock of building a solid retirement fund.
This is the opportunity cost of impulse spending: the money you spend today is money that cannot simultaneously be invested, saved or used towards an important financial goal.
For a broader look at how small financial decisions can influence long-term wealth, read Best Ways to Compound Wealth in India.
Money Rules to Avoid Impulse Purchases
1. Pause Before You Pay
Give yourself at least 24–48 hours before making any non-essential purchase. This buffer period helps you differentiate between need and want.
A simple delay can be surprisingly effective. The urgency associated with a purchase often disappears once you give yourself time to think about whether you actually need it.
2. Make a Budget and Stick to It
Hate to say this, but allocate a fixed amount each month for discretionary spending and don’t exceed it.
A budget does not mean that you cannot enjoy your money. It simply gives discretionary spending a defined place within your overall financial plan.
If you are working towards a longer-term goal such as retirement, make sure discretionary spending does not consistently take priority over your retirement planning goals.
3. Track Every Rupee
Use apps or a simple notebook to track expenses. Awareness curbs excess, but don’t drown in this tracking, build discipline, and then you can ditch these apps… At times, it can be too depressing.
The objective is not to monitor every rupee forever. The bigger goal is to understand your spending patterns well enough to develop sustainable financial discipline.
4. Ask: Will This Bring Me Lasting Value?
Before buying, ask yourself if the item truly adds long-term value or is just a fleeting desire.
This question becomes particularly useful for expensive purchases. Consider not just the price, but how often you will use the item, whether it supports your priorities and whether the purchase could delay an important financial goal.
A Little GreySmiles Thought
Before you make a big purchase, pause for a moment and ask yourself: “Will this make my life better, or will the money I spend on it make my future better?” You don’t have to say no to everything you want. The real discipline is knowing when to enjoy your money and when to let it work for you.
Building Discipline—The Secret Ingredient
Wealth isn’t built overnight; it’s cultivated with discipline and patience. In India, where family responsibility, children’s education, and caring for elders are major priorities, financial discipline is not a luxury—it’s a necessity. By consciously saying ‘NO’ to things you don’t need, you’re saying ‘YES’ to your future self and your family’s security.
Financial discipline does not mean eliminating enjoyment from your life. It means being intentional about where your money goes so that spending today does not compromise the life you want tomorrow.
Re-Directing Money: Invest for Retirement
Instead of spending impulsively, invest that money where it grows. Even small, regular investments in mutual funds, PPF, or NPS can snowball into a sizeable corpus over the years due to compounding interest. For instance, if you divert just Rs 2,000 a month away from impulse buys and invest it for 20 years (assuming a 10% annual return), you could accumulate nearly Rs 15 lakh—a sum that can help you retire with dignity and peace of mind.
The important lesson is not the precise future value of the investment, because actual returns will vary. It is the potential difference between repeatedly spending small amounts and consistently redirecting those amounts towards a long-term financial goal.
For more on building a retirement portfolio, see Retirement Wealth Diversification Guide for India.
You can also explore portfolio diversification and beating inflation as part of a broader long-term wealth strategy.
In Summary
Controlling impulse spending is like planting seeds for a financially secure future. The discipline you show today ensures that tomorrow, you can enjoy your retirement years without financial stress, provide for your loved ones, and live life on your own terms.
So next time you’re tempted, remember: “A rupee saved is a rupee invested for your dreams to come true.”
Frequently Asked Questions
1. What is impulse buying?
Impulse buying is making an unplanned purchase without adequately considering whether you need the item, can afford it or whether the money could be better used for another financial goal.
2. How does impulse buying affect long-term wealth?
Repeated impulse purchases can reduce the money available for saving and investing. They also create an opportunity cost because money spent today cannot simultaneously earn returns towards future financial goals.
3. How can I stop making impulse purchases?
Simple measures such as waiting 24–48 hours before non-essential purchases, setting a discretionary spending limit, tracking expenses and asking whether a purchase provides lasting value can help develop better spending habits.
4. Is it wrong to spend money on things I enjoy?
No. Financial discipline does not mean avoiding all discretionary spending. The objective is to spend intentionally within a budget while ensuring that lifestyle purchases do not consistently compromise important financial goals.
5. Can small amounts saved from impulse spending really make a difference?
Yes. Small amounts invested regularly can potentially grow significantly over long periods because of compounding. The example in this article illustrates how redirecting Rs 2,000 a month could potentially build a meaningful corpus over 20 years.
6. Should I invest money instead of spending it every time?
Not necessarily. Essential expenses, appropriate lifestyle spending and adequate liquidity are all important. The key is to create a balance so that discretionary spending does not consistently crowd out saving and investing for important future goals.
7. Why is financial discipline particularly important in India?
Many Indian households balance multiple financial responsibilities, including children’s education, family support, elder care and retirement. Financial discipline can help ensure that one set of responsibilities does not unnecessarily compromise another.
Disclaimer: This article is intended for general information and educational purposes. Investment returns are not guaranteed, and readers should consider their individual financial circumstances before making investment decisions.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.