
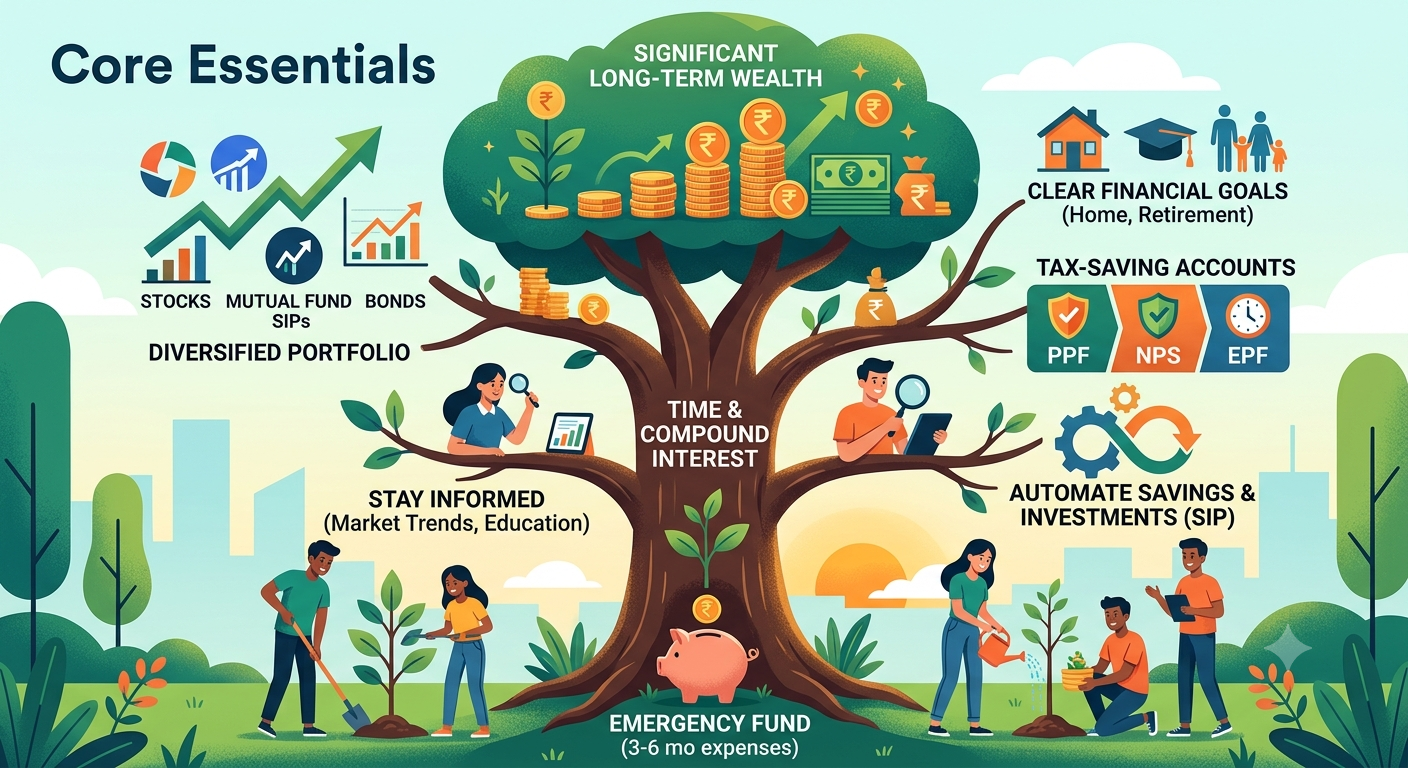
Master the core essentials of investing from building an emergency safety net to leveraging compound interest and tax-saving accounts to secure long-term financial freedom.
In today’s fast-paced financial landscape, young adults often face the challenge of managing their everyday finances while planning for their future. The earlier you start investing, the more time your money has to grow. For Millennials and Gen Z, understanding the basics of investing can pave the way to long-term financial security and a comfortable retirement. In this article, we will cover fundamental investment strategies and tips that can help you make your money work for you.
In This Article
- 1. Understand the Power of Compound Interest
- 2. Set Clear Financial Goals
- 3. Build an Emergency Fund
- 4. Create a Diversified Portfolio
- 5. Consider Retirement Accounts
- 6. Stay Informed About Market Trends
- 7. Automate Your Savings and Investments
- 8. Know Your Risk Tolerance
- 9. Don’t Panic During Market Fluctuations
- 10. Review and Rebalance Your Portfolio Regularly
- Frequently Asked Questions
1. Understand the Power of Compound Interest
One of the most crucial concepts in investing is compound interest—the ability of an investment to generate earnings that are reinvested to generate additional earnings.
Example: If you invest ₹5,000 per month at an annual return of 8%, by the time you reach 60, you could potentially accumulate about ₹10 crores. The key takeaway is that starting early can dramatically increase your wealth due to compounding.
2. Set Clear Financial Goals
Before you start investing, it’s important to identify your financial goals. Ask yourself:
- What do I want to achieve in the next 5, 10, or 20 years?
- Am I saving for a home, retirement, or education?
Defining your goals will help you choose the right investment strategies. Goals can be short-term (like saving for a down payment) or long-term (like retirement), and they will dictate the level of risk you’re willing to take.
3. Build an Emergency Fund
Before diving into investments, make sure you have a financial safety net in place. An emergency fund typically covers 3 to 6 months’ worth of living expenses. It provides peace of mind, allowing you to invest confidently without worrying about unexpected expenses.
4. Create a Diversified Portfolio
Diversifying your investments means spreading your investments across various asset classes to reduce risk.
Types of Investments:
- Stocks: Buying shares in companies can yield high returns but comes with higher risk. Consider index funds or Exchange-Traded Funds (ETFs) for a diversified stock portfolio, monitored under frameworks established by SEBI (Securities and Exchange Board of India).
- Bonds: These are typically lower-risk investments that pay regular interest. Government bonds, corporate bonds, and fixed deposits are common options.
- Mutual Funds: These funds pool money from many investors to purchase stocks and bonds. They are managed by professionals and can be a good option for beginners.
- Real Estate: Investing in property can also diversify your portfolio, though it often requires substantial capital up front.
A balanced portfolio might include 60% stocks, 30% bonds, and 10% alternative investments, but adjust this based on your risk tolerance and time horizon.
5. Consider Retirement Accounts
In India, several retirement savings options can help you save effectively:
- Public Provident Fund (PPF): A government-backed scheme offering attractive interest rates and tax benefits.
- National Pension System (NPS): A retirement-focused investment plan governed by PFRDA that allows contributions to a mix of equity and debt.
- Employee Provident Fund (EPF): If you’re salaried, this provides a good way to save for retirement with employer contributions under EPFO guidelines.
Contributing to these accounts not only helps secure your future but also provides significant tax benefits under the rules of the Income Tax Department of India.
Related Guides on Greysmiles:
6. Stay Informed About Market Trends
Education is key in the world of investing.
- Read Books and Articles: Start with foundational texts like The Intelligent Investor by Benjamin Graham or Rich Dad Poor Dad by Robert Kiyosaki.
- Follow Financial News: Outlets like Moneycontrol, The Economic Times, or Bloomberg can keep you updated on market trends and economic changes.
- Online Courses: Platforms like Coursera or Udemy offer courses that can help deepen your investment knowledge.
7. Automate Your Savings and Investments
Consider automating your contributions to savings and investment accounts. This “pay yourself first” approach ensures that you save before you spend.
SIP (Systematic Investment Plan): For mutual funds, setting up a SIP allows you to invest a fixed sum regularly, minimizing the impact of market volatility and encouraging discipline.
8. Know Your Risk Tolerance
Understanding your risk appetite is vital for making informed investments. Risk tolerance varies from person to person:
- Aggressive: If you’re young and have a high appetite for risk, consider a larger percentage of stocks in your portfolio.
- Moderate: A mix of stocks and bonds can be suitable if you prefer a balanced approach.
- Conservative: If you’re anxious about market fluctuations, allocate more to safer investments like bonds and fixed deposits.
9. Don’t Panic During Market Fluctuations
Market volatility is normal, and panicking during downturns can lead to poor financial decisions, such as selling at a loss. Maintain a long-term perspective, and remember that investments are generally more resilient over time.
10. Review and Rebalance Your Portfolio Regularly
As your financial situation and market conditions change, periodically review and rebalance your portfolio. This can help you maintain your desired asset allocation and adapt to new financial goals.
Frequently Asked Questions
1. How much should a beginner invest every month in India?
There is no minimum fixed amount, but following the 50/30/20 rule is a great benchmark: allocate 50% of your income to needs, 30% to wants, and at least 20% toward investments. Through mutual fund SIPs, you can start with as little as ₹500 per month.
2. Is it better to invest in direct stocks or mutual funds for beginners?
For most young adults without deep market analysis expertise, equity mutual funds or index funds via SIPs are recommended. They offer instant diversification and professional management, whereas direct stocks require continuous research and carry higher volatility risk.
3. What is the difference between PPF and NPS for long-term saving?
Public Provident Fund (PPF) is a 100% risk-free, government-backed debt scheme offering guaranteed returns with EEE tax status. The National Pension System (NPS) allows market-linked equity exposure (up to 75%), offering potentially higher returns over 20-30 years alongside additional tax deductions under Section 80CCD(1B).
4. Why is an emergency fund necessary before I start investing?
An emergency fund prevents you from prematurely liquidating long-term equity investments or SIPs during unexpected crises like medical expenses or job transitions. It ensures your long-term compounding strategy remains uninterrupted.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.