
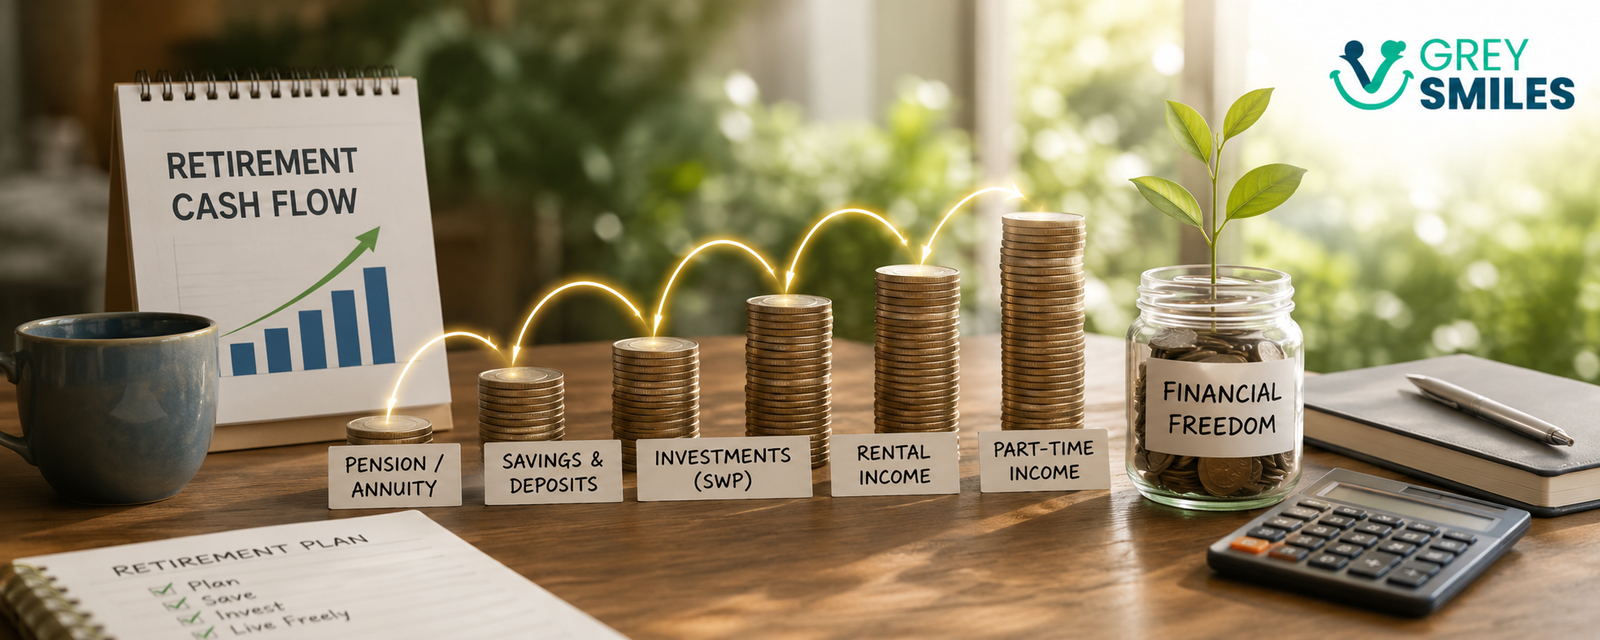
Different sources of retirement cash flow can work together to provide regular income and financial flexibility.
Retirement income is rarely as simple as replacing a salary with one new source of money. For many households, the cash flowing in after retirement may come from a combination of pension, interest, rent, dividends and withdrawals from investments.
The challenge is to make these different sources work together so that essential expenses are covered, the portfolio is not depleted unnecessarily and enough money remains available for the later years of retirement.
At a Glance
- Start with the income you actually need. Retirement cash flow should be built around expected spending, not around a product or investment.
- Separate dependable income from market-linked income. They behave differently and serve different purposes.
- Your retirement corpus is an income-producing asset. The question is not only how much you accumulate, but how you eventually use it.
- Don’t depend on one source unnecessarily. A combination of income sources can give a retirement plan greater flexibility.
- Review the plan as circumstances change. Spending, inflation, investment values and family needs will not remain constant throughout retirement.
First Work Out What Your Retirement Cash Flow Needs to Cover
The starting point is not “Which investment gives me monthly income?” It is “How much will I actually need to spend, and which expenses will continue throughout retirement?”
Housing, food, healthcare, insurance, travel, household help, family support and discretionary spending can all form part of the retirement budget. Some expenses may reduce after retirement, while others may increase or appear later.
GreySmiles’ article on how much you may actually need to spend in retirement looks at this question in more detail.
Then Identify the Income You Can Reasonably Count On
Once you have an estimate of retirement spending, list the income sources that are likely to be available.
| Income Source | What It Can Do | What to Watch |
|---|---|---|
| Pension | Provide relatively dependable recurring income | Amount, inflation, survivor benefits and terms |
| Interest income | Generate cash flow from deposits or other fixed-income assets | Interest rates, taxes and reinvestment risk |
| Rental income | Provide recurring income from property | Vacancies, maintenance, taxes and irregular receipts |
| Dividends | Provide distributions from eligible investments | Payments are not guaranteed and can change |
| Portfolio withdrawals | Fill the gap between other income and spending | Market returns, withdrawal rate, inflation and longevity |
The useful distinction is between money you can reasonably depend on and money whose availability depends on investment performance or other conditions.
Pension Can Form the Base, But It May Not Cover Everything
A pension can provide a useful foundation for retirement cash flow because it is designed to provide recurring income.
But the adequacy of that income depends on your expenses. A pension that comfortably covers essential household costs may still leave a substantial gap once healthcare, travel, family support or other discretionary expenses are included.
That gap is where other assets and income sources become important.
Interest Income Can Add Stability
Bank deposits and other fixed-income investments can provide interest income and may play an important role in the more stable portion of a retirement portfolio.
However, interest income should not automatically be treated as permanent. Interest rates can change, deposits mature and money may need to be reinvested at different rates.
Tax also matters. The amount that reaches your bank account after tax is more relevant to your household budget than the headline interest rate.
Rental Income Is Useful, but It Is Not the Same as a Pension
Property can produce recurring rental income and may form an important part of some retirees’ financial plans.
But rent can be interrupted by vacancies, delayed payments, maintenance expenses or changes in the property market. A realistic retirement budget should therefore distinguish between expected rental income and income that is genuinely dependable.
Property can also represent a large concentration of household wealth. The fact that an asset produces rent does not automatically make it suitable for every retirement-income plan.
Dividends Should Not Be Treated as a Guaranteed Salary
Dividend-paying investments can contribute to retirement cash flow, but dividends are distributions rather than guaranteed income.
The amount and timing can change, and the underlying investment remains exposed to market movements. For this reason, dividend income is better viewed as one component of a diversified retirement-income structure rather than as a guaranteed replacement for employment income.
Your Retirement Corpus May Need to Fill the Remaining Gap
Suppose your household needs more income than pensions, interest and other dependable sources can provide. Your accumulated retirement corpus may need to fund the difference.
This is where retirement planning moves from accumulation to withdrawal.
The size of the corpus matters, but so do the timing and size of withdrawals, investment performance, inflation and how long the money needs to last. A large corpus can still come under pressure if withdrawals are poorly structured or begin during a prolonged period of weak market performance.
GreySmiles’ guide on how to withdraw from a retirement corpus explores this transition in more detail.
A Large Corpus Does Not Automatically Mean Reliable Income
It is tempting to look at a retirement corpus and divide it by the number of years you expect to live. Real retirement cash flow is more complicated.
Investment values move. Inflation changes the purchasing power of withdrawals. Healthcare expenses can be unpredictable. Retirement can last longer than expected.
There is also a behavioural problem: a retiree may be uncomfortable selling investments after a market fall and may either withdraw too much from safer assets or make abrupt portfolio changes.
A sustainable income plan therefore needs to consider both the amount of money available and how different parts of the portfolio will be used over time.
Think About Near-Term and Longer-Term Money Separately
One useful way to organise retirement cash flow is to distinguish between money that may be needed soon and money that can remain invested for later years.
The money required for the next few years has a different job from money that may not be touched for a decade or longer. Treating both in exactly the same way can expose near-term spending to unnecessary market volatility or leave too much of the long-term portfolio sitting idle.
This is one reason laddering for retirement can be useful as a way of organising assets around future cash requirements. It is not a complete retirement-income strategy, but it can help connect investment maturities with planned spending needs.
Inflation Changes the Meaning of “Enough”
A retirement income that looks comfortable today may not buy the same amount of goods and services many years from now.
This is particularly important for expenses that may rise faster than general household spending, such as healthcare.
A retirement-income plan therefore needs enough flexibility to respond to changing costs rather than assuming that today’s monthly budget will remain unchanged throughout retirement.
What Happens When One Income Source Falls?
A good retirement-income plan should not depend on every source performing perfectly every year.
Rent may stop temporarily. Interest rates may fall. Dividends may change. Investment markets may decline. A family member may need financial support.
The question is whether the household has enough flexibility to absorb these events without immediately disrupting essential spending.
This is also why an emergency reserve and a separate healthcare provision can be useful. The retirement portfolio should not have to solve every unexpected problem at the exact moment it occurs.
Don’t Build the Plan Around One “Perfect” Income Product
Retirement products are often presented as if one solution can solve the entire income problem. In reality, different assets can perform different jobs.
A pension may cover part of essential spending. Fixed-income assets may provide stability. Investments may provide longer-term growth. A portion of the corpus may be withdrawn as needed. Property may contribute rent. The right combination depends on the household.
The objective is not to make every rupee produce a monthly payment. It is to create a structure that can meet spending needs over the whole retirement period.
A Simple Way to Map Your Retirement Cash Flow
Start with four numbers:
- Expected essential spending
- Expected discretionary spending
- Dependable retirement income
- The amount that needs to come from investments
The gap between spending and dependable income gives you a much clearer starting point for thinking about your investment portfolio.
The size of that gap can also tell you whether the retirement corpus is likely to be adequate or whether you need to revisit spending, retirement timing, savings or other sources of income.
Review the Cash Flow Plan, Not Just the Portfolio
Retirement planning does not end when you retire.
Your expenses can change. Investment values can change. A spouse’s income situation can change. Healthcare requirements may change. You may decide to travel more in one period and spend less in another.
A periodic review should therefore ask not just “How did my investments perform?” but “Can my current income structure still support the life I am living?”
GreySmiles Take
Retirement income is less about finding one investment that pays every month and more about organising different sources of money around the way you actually spend. The strongest plans leave room for both certainty and flexibility: dependable income for the expenses that must be met, and a sufficiently diversified pool of assets for everything that cannot be predicted in advance.
Frequently Asked Questions
What is cash flow in retirement?
Cash flow in retirement is the money coming into the household and the money going out to meet expenses after employment income reduces or stops. It can include pensions, interest, rent, dividends and withdrawals from investments.
What are the best sources of retirement income?
There is no single best source for everyone. Pensions, fixed-income investments, property income and withdrawals from a retirement corpus can all play different roles. The appropriate combination depends on spending needs, existing assets, risk and the desired level of flexibility.
Should I live only on the interest from my retirement corpus?
Not necessarily. Interest rates can change, and relying exclusively on interest may not provide enough income or sufficient protection against inflation. The appropriate approach depends on the size and structure of the overall retirement portfolio.
Can rental income fund retirement?
Rental income can contribute significantly to retirement cash flow, but it is not guaranteed. Vacancies, repairs, taxes and changes in rental demand can affect the amount actually received.
Should I withdraw from my retirement corpus every month?
A regular withdrawal schedule can make budgeting easier, but the amount and frequency should be considered in the context of the overall portfolio, expected spending, investment performance, inflation and longevity.
How can laddering help with retirement cash flow?
Laddering organises portions of a portfolio around different future time horizons or maturity dates. It can help make upcoming cash requirements more visible and reduce the need to make investment decisions at the last minute.
Further Reading
- How Much Will I Actually Need to Spend in Retirement?
- Retirement Corpus Calculation: How Much Do You Need?
- How to Withdraw From a Retirement Corpus
- Laddering for Retirement
Sources & References
- Pension Fund Regulatory and Development Authority (PFRDA) — retirement and pension education resources.
- Securities and Exchange Board of India (SEBI) — investor education material on retirement planning and investment risk.
Disclaimer: This article is for educational purposes only and does not constitute financial or investment advice. Retirement income depends on individual circumstances, assets, expenses, investment performance, taxation, inflation and longevity.


Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.