
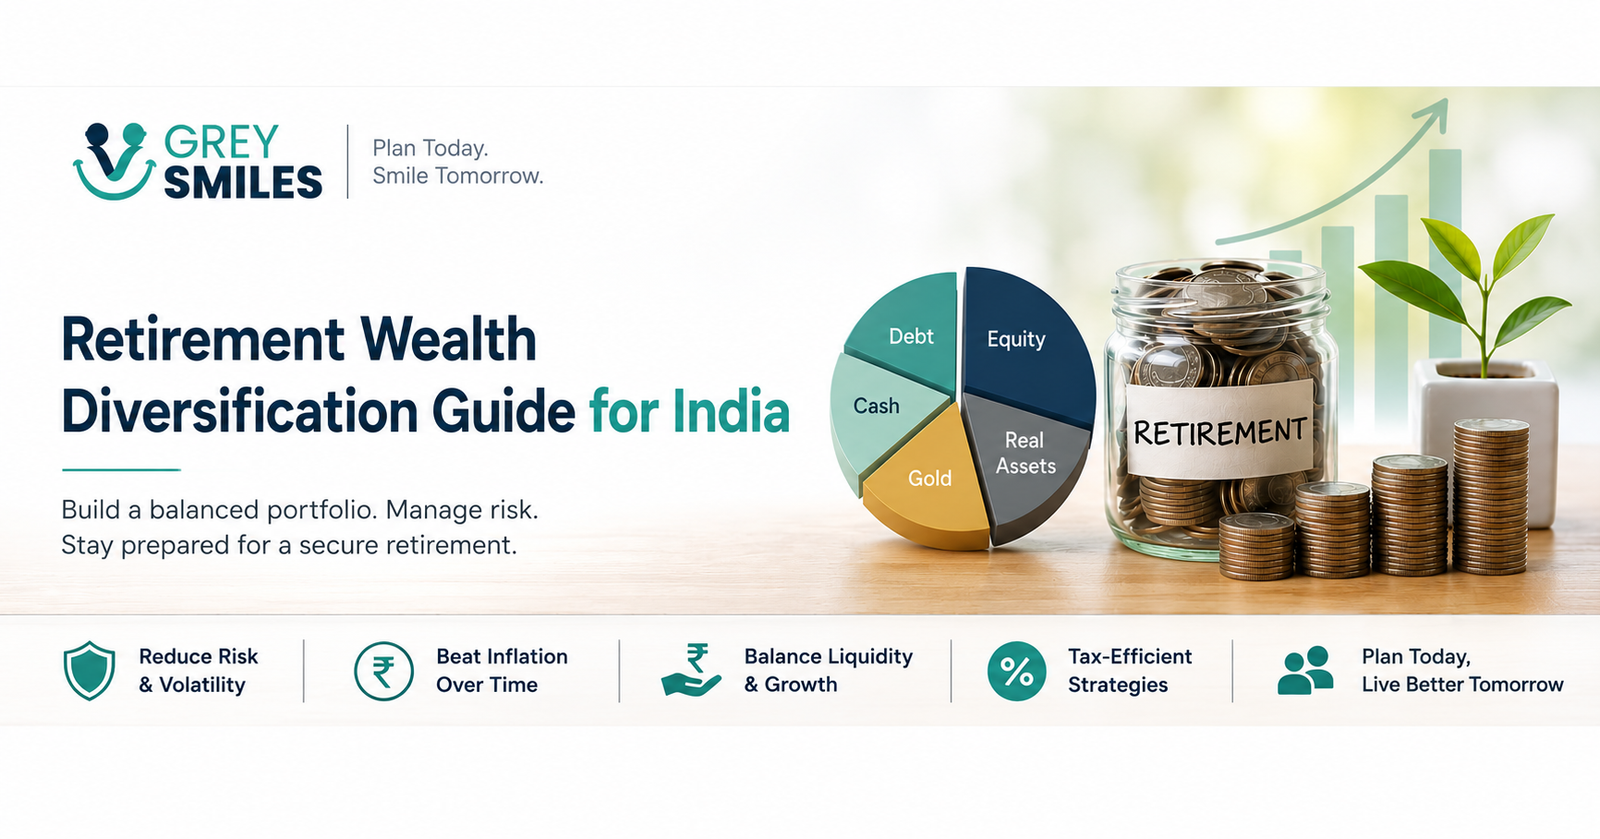
A diversified retirement portfolio can balance growth, stability, income and liquidity.
A practical, diversified retirement portfolio reduces the risk of running out of money, helps manage inflation & longevity risk, and balances tax and liquidity needs. This article explains what diversification means for retirement, offers India-focused instruments, sample allocations, a corpus calculation approach, and an action checklist you can implement.
At a Glance: Retirement Wealth Diversification
- Diversification: Spread retirement wealth across equity, debt, cash, real assets and insurance/annuities to balance growth, stability, income and liquidity.
- Risk changes with age: Your asset allocation should reflect your age, retirement timeline, risk tolerance and required retirement income.
- India offers multiple options: PPF, EPF, NPS, SCSS, fixed deposits, government securities, mutual funds, gold and annuities can play different roles.
- Liquidity matters: Keep sufficient funds available for emergencies and near-term expenses so long-term investments do not have to be sold at an inconvenient time.
- Tax matters: Different retirement instruments have different tax treatments, so post-tax returns and withdrawal needs should be considered.
- There is no one-size-fits-all allocation: The right mix depends on your circumstances and retirement goals.
For a broader understanding of the retirement planning process, see our guide to Retirement Planning in India.
Contents:
- What is wealth diversification?
- Why it matters for retirement
- Key asset classes & expected returns
- Sample asset allocations (by age & risk)
- India-specific instruments & tax notes
What is wealth diversification?
Diversification spreads your money across different asset types (equity, debt, cash, real assets, and insurance/annuities) and within those types (different sectors, market caps, geographic exposures). The goal is to reduce volatility and sequence-of-returns risk while preserving the chance for real growth that beats inflation.
Why diversification matters for retirement planning
- Protects against large drawdowns close to retirement (sequence-of-returns risk).
- Maintains purchasing power vs inflation over a long retirement horizon.
- Balances liquidity needs (emergency & near-term expenses) with growth needs (long-term spending).
- Provides tax-efficient withdrawal strategies given India’s tax rules.
For more on protecting retirement wealth against rising prices, see Beating Inflation in India: The Case for Strategic Investment Diversification.
Key asset classes & expected ranges
Key Asset Classes & Expected Ranges
Note: Returns are indicative historic/typical ranges (nominal), not guaranteed. Update with current market data before finalizing.
| Asset Class | Primary Purpose | Typical Time Horizon | Indicative long-term returns (nominal) | Key Risks |
|---|---|---|---|---|
| Indian Equity (index & diversified MFs) | Real growth, beat inflation | 10+ years | 9–14% p.a. | Volatility, market corrections, sequence risk |
| Debt (govt bonds, corporate bonds, debt MFs) | Stability, income, capital preservation | 1–10 years (varies) | 5–8% p.a. | Interest-rate risk, credit risk |
| Public Provident Fund (PPF)/EPF | Safe tax-efficient long-term savings | 15+ years (PPF tenure) | 6.5–8% p.a. (government-set) | Liquidity constraints (lock-in), admin rate changes |
| Fixed Deposits / SCSS / Post office | Guaranteed income for near-term/seniors | 1–5 years / SCSS 5 years | 6–8% p.a. (variable) | Inflation risk, reinvestment risk |
| National Pension System (NPS) | Long-term retirement accumulation, partial tax benefits | Long-term till retirement | Mixed (equity + debt) — depends on allocation; equity returns 8–12% long-run | Market risk for equity portion, annuity rules at exit |
| Annuities / Pension plans | Guaranteed lifetime income | Post-retirement | Depends on plan; typically lower than equities (real yield may be low) | Inflation erosion unless inflation-linked |
| Real assets (gold, property exposure) | Inflation hedge, diversification | Medium to long | Varies; gold ~6–10% long term (volatile) | Liquidity, valuation, concentration risk (property) |
Sample asset allocations (guidelines)
Sample Asset Allocations
Asset allocation must match your risk tolerance, current age, retirement age, and required retirement income. Use these as starting templates and customize after assessing goals.
| Profile / Age | Equity | Debt & PPF/EPF | Cash / FD / Emergency | Other (Gold, Property, Annuity) |
|---|---|---|---|---|
| Accumulation — Young (25–35), High risk | 70–90% | 5–15% | 3–6 months of expenses | 5–10% |
| Mid-career (36–50), Balanced | 50–70% | 20–35% | 6–9 months of expenses | 5–10% |
| Pre-retirement (51–60), Conservative tilt | 30–50% | 35–55% (incl. PPF/EPF) | 9–12 months of expenses | 5–10% (consider annuities near retirement) |
| Post-retirement (60+), Income focus | 20–40% (for growth) | 40–60% (FDs, SCSS, debt funds) | 1–2 yrs of expenses in liquid instruments | 10–20% annuity or inflation-linked products |
Tax structure
Equity
- Index funds & large-cap diversified mutual funds: low cost and simple core holdings.
- ELSS (Equity Linked Savings Scheme) gives 80C tax benefit but has a 3-year lock-in.
- Direct equity for those with capacity & risk appetite; diversify across sectors.
Debt / Government schemes
Debt / Government Schemes
Public Provident Fund (PPF): Government-backed, tax-free maturity (EEE). Lock-in 15 years (extendable in blocks of 5). Interest rate set quarterly by government — indicative mid-2024 range ~6.5–7.5% p.a. Good for long-term guaranteed portion.
Employees’ Provident Fund (EPF): For salaried employees; contributions & interest generally tax-exempt at retirement (subject to conditions). Interest rate set annually (historically ~8–8.5% in many years; check current). The Employees’ Provident Fund Organisation (EPFO) provides the latest information on EPF rules, contributions and interest.
Senior Citizens Savings Scheme (SCSS): For 60+ (and some other eligible groups). 5-year tenure (with possible extension), interest paid quarterly; interest taxable. Indicative rates mid-2024 ~7% p.a. Good for retirees seeking secure income. Current eligibility, limits and interest rates should be checked before investing.
Government Small Savings & Post Office Schemes (KVP, TDs, MIS): Provide guaranteed returns; some may have lock-ins or tax implications. Kisan Vikas Patra (KVP)
Government Bonds / G-Secs / Sovereign Gold Bonds: G-Secs provide predictable coupon income (yields vary; 10-year G-sec often used as a benchmark; update current yield). Sovereign Gold Bonds are an interest-bearing way to hold gold with capital gains indexation benefits.
Bank Fixed Deposits / Corporate FDs: For shorter-term guaranteed income; interest taxable as per slab. For retirees, laddering helps manage reinvestment risk.
National Pension System (NPS): Mix of equity/debt with tax benefits (partial). At retirement, a portion must be used to buy an annuity (rules and tax treatment change, check latest notifications). Equities in NPS help growth; debt portion reduces volatility.
The GreySmiles Thumb Rule
Do not choose an investment simply because it offers the highest return. For retirement, the better question is whether each investment has a clear role in your portfolio — growth, stability, income, liquidity or protection. A diversified retirement portfolio should make it easier to stay invested through market cycles, not harder.
Equity & Tax-efficient options
- Equity Linked Savings Schemes (ELSS): 3-year lock-in, qualifies for section 80C deduction — useful for building equity exposure early.
- Index funds & large-cap MFs: Low-cost core equity allocation; use SIPs to average cost.
- Direct equity: For experienced investors — ensure sector & stock diversification and position sizing limits.
Annuities & insurance
- Immediate annuities: Convert lump sum to guaranteed income. Consider inflation-indexed annuities if available or combine annuity for base income + a growth portfolio for upside.
- Life insurance & health insurance: Not direct retirement assets but essential for financial protection to avoid burning retirement capital for emergencies.
Tax note summary: PPF interest & maturity are tax-free; EPF tax-exempt at retirement subject to conditions; FD & SCSS interest taxable as per slab; ELSS eligible for 80C deduction; annuity income is taxable. Laws have been changing frequently in recent years, please consult a tax advisor.
Also read:
Beating Inflation in India: The Case for Strategic Investment Diversification
Best Ways to Compound Wealth in India
Why you should target 4 Crore retirement corpus?
Frequently Asked Questions
1. What is wealth diversification for retirement?
Retirement wealth diversification means spreading your retirement savings across different asset classes such as equity, debt, cash, gold, property and, where appropriate, annuities. The aim is to balance growth, stability, income and liquidity.
2. How much equity should I have in my retirement portfolio?
There is no single allocation that works for everyone. Equity exposure should reflect your age, retirement timeline, risk tolerance, existing corpus and required retirement income. The sample allocations in this article are starting points rather than fixed recommendations.
3. Why is diversification important after retirement?
Retirement portfolios need to support withdrawals over a potentially long period. Diversification can reduce dependence on any one asset class and help manage market volatility, inflation, liquidity and longevity risks.
4. Which investments can be used for retirement in India?
Depending on individual circumstances, retirement portfolios can include equity mutual funds, debt instruments, PPF, EPF, NPS, fixed deposits, SCSS, government securities, gold, property and annuities.
5. Should retirees keep money in fixed deposits?
Fixed deposits can provide predictable income and liquidity and may form part of the stability portion of a retirement portfolio. However, retirees should also consider inflation, taxation and reinvestment risk rather than relying entirely on fixed deposits.
6. Is NPS suitable for retirement planning?
NPS can form part of a long-term retirement strategy by combining equity and debt exposure with applicable tax benefits. Its rules, exit provisions and tax treatment should be checked against the latest applicable regulations.
7. What is the GreySmiles approach to retirement diversification?
The focus should not simply be on finding the highest-return investment. Each investment should have a clear role in the portfolio — growth, stability, income, liquidity or protection.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.