
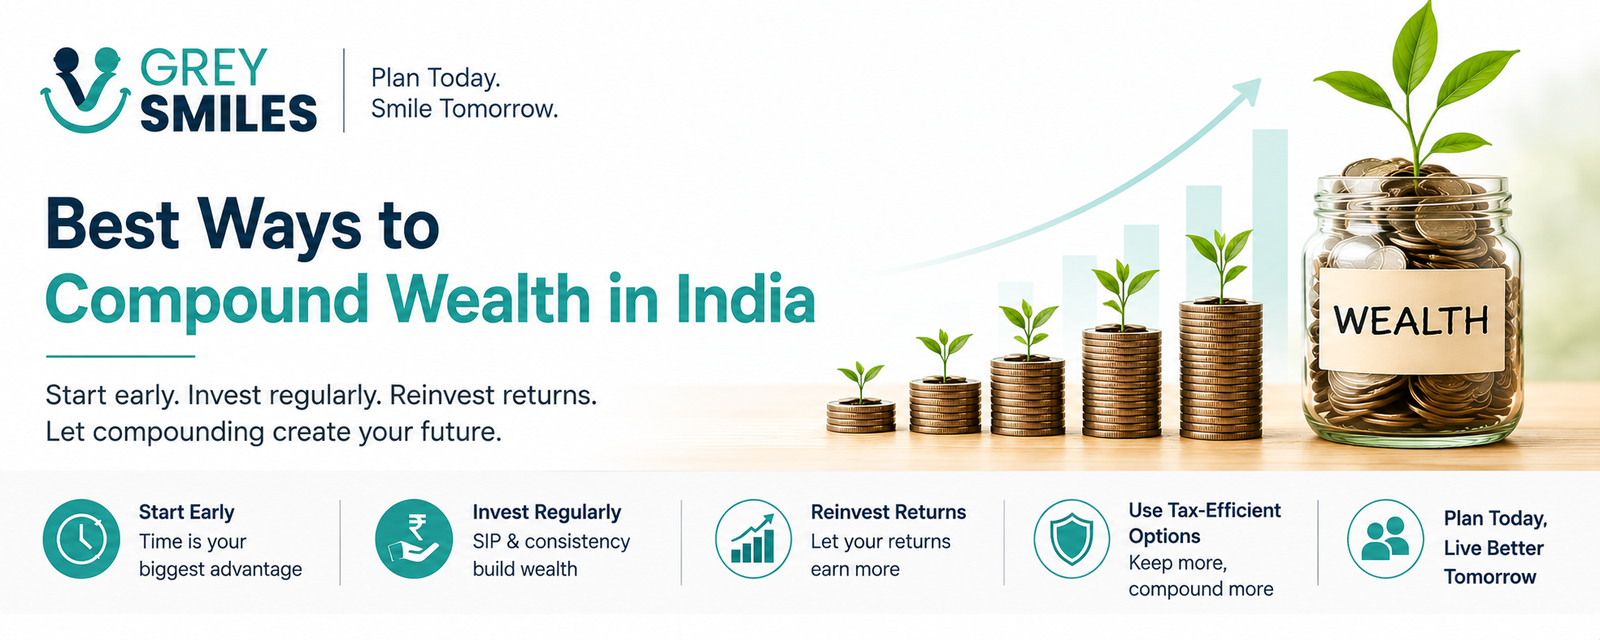
Starting early, investing regularly and reinvesting returns can help wealth compound over time
Building wealth is often presented as a hunt for the investment that will deliver the highest return. That is usually the wrong place to start.
Long-term wealth is built through a combination of time, regular investment, sensible returns, reinvestment and the ability to stay invested. The investment product matters, but it is only one part of the equation.
Compounding works because returns can themselves generate further returns. Given enough time, even relatively modest regular investments can become meaningful. But compounding can also work against you when high costs, unnecessary withdrawals, excessive debt or poor investment decisions interrupt the process.
At a Glance
- Time matters enormously. Starting earlier gives your money more years to potentially compound.
- Regular investing matters. Consistent contributions can be more important than trying to identify the perfect entry point.
- Returns matter, but higher returns come with higher risk. Chasing returns can damage the very compounding process you are trying to build.
- Reinvestment is central to compounding. Returns that remain invested have the opportunity to generate further returns.
- Costs, taxes and unnecessary withdrawals reduce what remains invested.
- Compounding is a process, not a product. Mutual funds, provident funds, NPS, deposits and other investments are vehicles through which wealth can potentially compound.
What Does Compounding Actually Mean?
Suppose you invest ₹1 lakh and it earns a return. If the return remains invested, the next period’s return is earned not only on your original ₹1 lakh but also on the accumulated gains.
Over a long period, that difference can become substantial.
The mathematics is simple:
Future Value = Initial Investment × (1 + Return)Number of Years
With regular investments, the calculation becomes more complicated because money enters the portfolio at different points in time. But the underlying idea remains the same: money that stays invested has more opportunity to generate further growth.
Why Starting Early Makes Such a Difference
Consider two people who eventually invest the same total amount but start at different ages.
The earlier investor has something the later investor cannot buy back: time.
This does not mean that someone starting at 45 or 50 has missed the opportunity. It means that the later you start, the more important your savings rate, investment discipline and realistic expectations become.
Starting early can also reduce the pressure to achieve unusually high investment returns. If you have several decades, your wealth has more time to grow through repeated periods of investment and reinvestment.
This is one reason retirement planning and wealth creation are closely connected, even though they are not the same thing.
Compounding Has More Than One Engine
People often talk about compounding as though investment returns are the entire story.
In reality, several forces work together.
| Engine | What it does |
|---|---|
| Time | Allows investment growth to accumulate over many years. |
| Fresh savings | Adds new capital to the portfolio. |
| Investment returns | Increase the value of the existing portfolio. |
| Reinvestment | Keeps gains working rather than removing them from the portfolio. |
| Behaviour | Determines whether you remain invested long enough for the process to work. |
That last factor is easy to underestimate.
An investor who repeatedly moves in and out of investments because of short-term market movements can lose some of the benefit of long-term compounding even if the underlying investments are sound.
Regular Investing Can Matter More Than Perfect Timing
For someone building wealth from monthly income, regular investing provides a straightforward way of putting new money to work.
A Systematic Investment Plan (SIP) is one way to do this through mutual funds. It does not guarantee returns, and it does not make an investment risk-free. Its main advantage is behavioural: it creates a regular investment habit.
Trying to wait for the “perfect” market level can become another form of procrastination.
For long-term goals, the more useful question is often whether the amount being invested is appropriate for the goal and whether the investor can remain committed through market cycles.
Where Should Compounding Money Be Invested?
There is no single investment that owns the concept of compounding.
Different assets can play different roles.
| Investment type | Potential role | What to remember |
|---|---|---|
| Equity | Long-term growth | Higher volatility means investors need an appropriate time horizon and risk capacity. |
| Equity mutual funds | Diversified participation in equity markets | Fund selection, costs, risk and portfolio fit still matter. |
| EPF/PPF and other fixed-income instruments | Stability and long-term savings | Returns and rules vary by instrument and can change over time. |
| NPS | Long-term retirement savings | It has its own investment choices, rules and withdrawal structure. |
| Deposits and bonds | Income and portfolio stability | Lower volatility does not necessarily mean protection from inflation. |
| Gold and other assets | Diversification | They may play a supporting role rather than being the primary compounding engine. |
The important distinction is between an asset’s role and the fact that it may produce a return.
A retirement portfolio, for example, may need both growth and stability. Putting everything into the asset with the highest historical return is not necessarily a sensible way to build long-term wealth.
Equity Can Be a Powerful Long-Term Growth Asset — But It Is Not a Shortcut
Equities have significant long-term wealth-building potential because investors participate in the growth of businesses and the economy.
But equity markets can also fall sharply.
That creates an important distinction: the ability to tolerate volatility is part of the price of pursuing higher long-term growth.
Someone who sells after a large market decline can turn temporary volatility into a permanent loss. Someone who remains appropriately invested may have more opportunity to benefit from a subsequent recovery.
This does not mean every investor should maximise equity exposure. The appropriate allocation depends on the goal, time horizon, risk capacity and the investor’s ability to remain invested.
Compounding Can Be Damaged by Good-Looking Decisions
Not every financial decision that feels sensible helps long-term wealth.
Frequent switching
Moving between investments because one has recently performed better can lead to chasing past performance rather than following a long-term plan.
Taking excessive risk
A higher expected return is not useful if the resulting volatility causes you to abandon the investment at the wrong time.
High costs
Investment costs reduce the amount of money that remains invested. Small differences can matter when they are repeated over many years.
Unnecessary withdrawals
Money removed from a long-term portfolio no longer has the opportunity to compound inside it.
Using retirement money for short-term goals
If long-term investments repeatedly become the source of funding for near-term expenses, the compounding process gets interrupted.
Growing lifestyle expenses as fast as income
A rising income does not automatically create rising wealth. If every increase in earnings is absorbed by higher spending, the amount available for long-term investment may never increase.
The Difference Between Saving More and Earning More From Investments
There are two broad ways to increase the eventual size of a portfolio:
- put more money into it; and
- allow the existing money to grow.
Both matter.
For someone early in their career, increasing the savings rate can be a particularly powerful lever because income may rise over time. A person who increases investments whenever income rises can gradually put more capital to work without relying entirely on higher market returns.
This is often more controllable than trying to predict which investment will outperform next year.
What About Tax?
Compounding should be considered on what you actually keep, not simply on the headline return.
Taxes can affect the amount available for reinvestment, depending on the investment, holding period, transaction and applicable tax rules.
That does not mean the most tax-efficient investment is automatically the best investment. Liquidity, risk, diversification and suitability still matter.
The useful principle is simply to include tax in your overall return calculation rather than treating it as an afterthought.
What About Debt?
Debt can quietly compete with investment compounding.
If a household is carrying expensive debt while simultaneously investing for long-term wealth, it is worth comparing the cost of the debt with the expected after-tax return from the investment.
This does not mean every loan should be repaid before investing. A home loan, education loan and high-cost consumer debt are very different situations.
But building an investment portfolio while allowing expensive debt to accumulate can undermine the wealth-building process.
Compounding and Retirement
Compounding becomes especially important when retirement is the goal because the investment horizon can be long.
But retirement planning adds another dimension: eventually, the direction reverses.
During the accumulation years, you are putting money into the portfolio and allowing it to grow. During retirement, you begin taking money out.
That transition needs its own planning.
Once you are close to or in retirement, the question is no longer simply how quickly the portfolio can grow. You also need to think about liquidity, withdrawal rates, market volatility, inflation and how long the money may need to last.
For that reason, wealth accumulation and retirement-income planning should be treated as connected but separate decisions.
See How to Calculate Your Retirement Corpus in India when you are ready to translate accumulated wealth into a retirement target.
A Simple Wealth-Compounding Routine
You do not need to monitor your investments every day to benefit from compounding.
A simpler routine can be more effective:
- Set a long-term goal. Know what the money is ultimately meant to achieve.
- Invest regularly. Automate contributions where practical.
- Choose an appropriate asset allocation. Match risk to the time horizon and your ability to tolerate losses.
- Keep costs under control. Understand what you are paying.
- Reinvest rather than constantly withdrawing.
- Increase investments when income rises.
- Review periodically. Check whether the portfolio still matches the goal rather than reacting to every market movement.
- Allow time to do its work.
What Compounding Cannot Do
Compounding is powerful, but it is not magic.
It cannot guarantee a particular return. It cannot remove market risk. It cannot compensate indefinitely for inadequate savings. And it cannot turn an unsuitable investment into a suitable one simply because you intend to hold it for a long time.
It also cannot recover time that has already been lost.
That is why starting with a realistic savings habit and a sensible portfolio is more useful than searching endlessly for the investment with the highest possible return.
A Useful Way to Think About Wealth
There are three stages to long-term wealth building:
| Stage | Main job |
|---|---|
| Build | Increase income, control spending and create investable savings. |
| Compound | Keep appropriate investments working for the long term and reinvest gains. |
| Use | Convert accumulated wealth into the income and spending that the money was built to support. |
The mistake is to spend too much attention on the second stage while neglecting the first and third.
The Bottom Line
There is no secret investment that makes wealth compound.
Compounding is the result of giving money time, adding to it consistently, earning reasonable returns for the risk taken, reinvesting the gains and avoiding decisions that repeatedly interrupt the process.
For a young investor, the biggest advantage may simply be time. For someone starting later, increasing savings and making sensible investment decisions become more important.
And as wealth grows, the objective eventually changes. The money has to move from being something you are building to something that supports your life.
That is where wealth creation becomes retirement planning.
Sources & References
- SEBI Investor – Investor Education
- PFRDA – National Pension System
- EPFO – Employees’ Provident Fund Organisation
Disclaimer: This article is for educational and informational purposes only and should not be treated as personalised financial or investment advice. Investment values can rise or fall, and past performance does not guarantee future results. Tax rules, investment-product features and regulations can change. Verify current information from the relevant official source before making financial decisions.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.