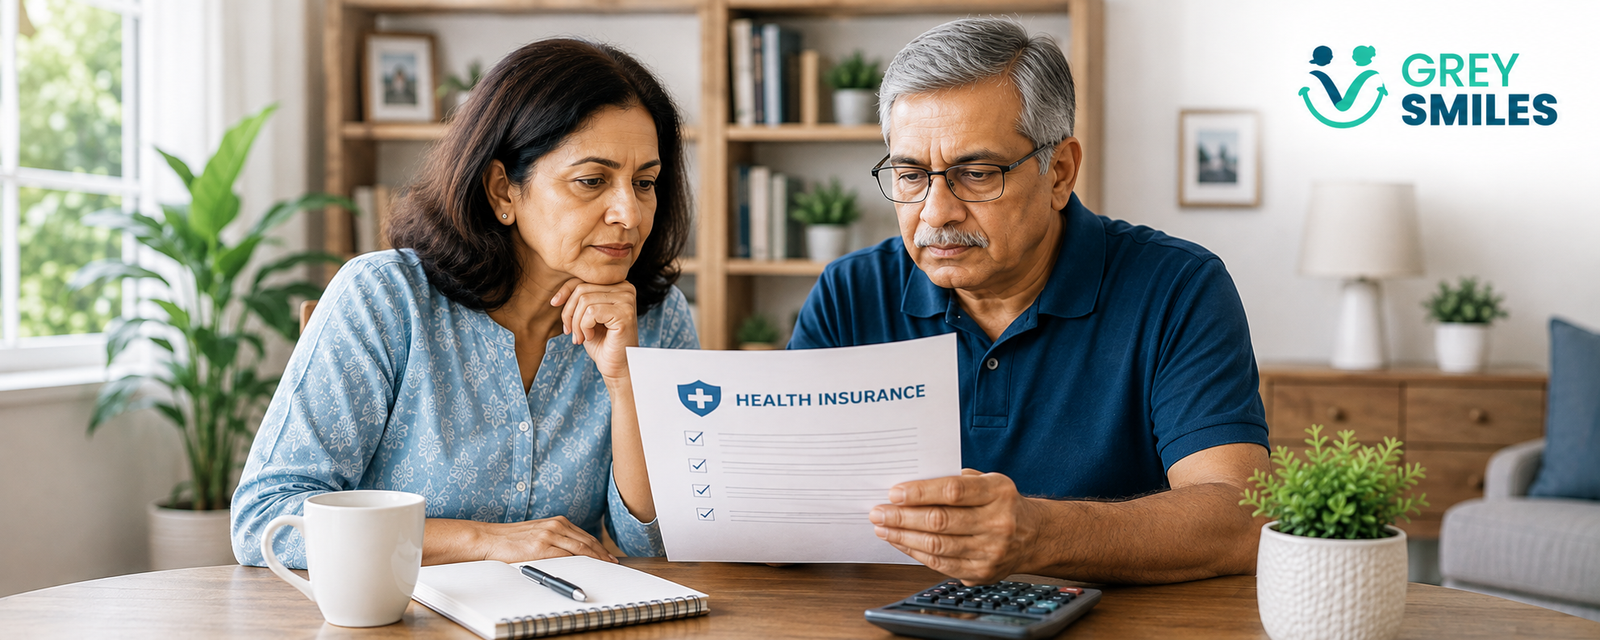
Reviewing health insurance coverage and potential gaps before retirement.
By Kartikey Gupta, CMT, CFA Level II Qualified
Finance professional with 6+ years of experience across capital markets, insurance and financial services
Having health insurance is an important part of preparing for retirement. However, having a policy does not necessarily mean you have enough protection for the years ahead.
As you move from employment into retirement, your health insurance can become more important. Employer-sponsored cover may change, premiums may become a larger part of your budget, and some healthcare expenses may still have to come out of your own pocket even when you have substantial insurance cover.
The more useful question is not simply “Do I have health insurance?” It is:
“Is the health insurance I have likely to be enough for the retirement I am planning?”
At a Glance
There is no single health-insurance amount that is enough for every retiree. Adequacy depends on your age, health, existing coverage, family situation, policy terms, location and the amount you can comfortably pay yourself if a claim does not cover the entire expense.
- Look beyond the sum insured. A large headline cover can still have important limitations.
- Understand your out-of-pocket exposure. Co-payments, deductibles, exclusions and limits can affect what you actually pay.
- Check future affordability. A policy is less useful if its premiums become difficult to maintain after retirement.
- Look at both spouses separately. Their ages, health, coverage and future needs may be different.
- Plan for costs outside insurance. A separate healthcare reserve can provide another layer of protection.
- Review the policy periodically. Your healthcare needs and insurance circumstances can change over time.
What Does “Enough” Health Insurance Actually Mean?
“Enough” is not simply a number printed on the first page of your policy.
Your actual protection depends on what the policy covers, the conditions attached to that cover and what you may still have to pay yourself.
A policy with a large sum insured can still leave you with significant out-of-pocket expenses if there are co-payments, deductibles, exclusions, waiting periods or sub-limits.
That is why assessing health insurance for retirement requires looking beyond the headline cover amount.
Start With Your Current Policy
Before deciding whether you need more insurance, take your current policy documents and understand exactly what you already have.
- What is the current sum insured?
- Is the cover individual or shared with other family members?
- What co-payment or deductible applies?
- Are there room-rent or other sub-limits?
- Which major exclusions apply?
- Are there waiting periods that are still relevant?
- What expenses are you likely to pay yourself?
- Can you comfortably afford the premium after retirement?
- What happens to the coverage if your employment ends?
- Does your spouse have adequate protection separately?
If several of these questions are difficult to answer, that itself is a reason to review the policy more carefully.
Look Beyond the Sum Insured
The sum insured is one of the easiest parts of a health insurance policy to compare. It is also not the whole story.
Co-payments and deductibles can affect how much of an eligible claim you ultimately pay yourself. Sub-limits and other policy conditions can also affect the amount that is actually payable for particular expenses.
The important point is not that these features are automatically good or bad. It is that you should understand them before assuming that your full sum insured represents money available for every medical expense.
What About Waiting Periods and Exclusions?
Waiting periods and exclusions can become particularly important as you get older or when you already have health conditions.
A policy may provide substantial cover overall while still restricting coverage for particular conditions or treatments during specified periods. Do not assume that an illness or treatment will be covered simply because your policy has a large sum insured.
Read the policy wording and understand what is covered, what is excluded and whether any waiting period applies.
If you are considering changing policies, these conditions deserve particular attention. A lower premium or higher headline cover does not automatically remove the need to examine continuity and restrictions.
For current regulatory and consumer information, refer to the Insurance Regulatory and Development Authority of India (IRDAI).
Can You Afford the Insurance After Retirement?
This question can be overlooked while you are still working. A health insurance policy may represent a relatively small part of your household income today. After retirement, you may depend primarily on pension income, investment income or withdrawals from your retirement corpus.
That makes future affordability an important part of your retirement planning.
Look at the premium alongside the retirement income you expect to have and the other expenses your retirement corpus will need to support.
Health insurance should therefore be considered not only as protection, but also as an ongoing retirement expense.
What Happens to Employer Health Insurance When You Retire?
If your current health insurance comes through your employer, find out exactly what happens when your employment ends. Do not assume that employer-sponsored cover will automatically continue after retirement.
Document your current employer cover, understand when it ends and find out what migration or continuation options are available under your arrangement.
If you are several years away from retirement, this is worth checking well before your last working day. It gives you time to understand your post-retirement options rather than making a rushed decision after employment ends.
For a separate look at this transition, see What Happens to Your Health Insurance When You Retire?
What About Your Spouse?
Couples should not assume that household-level coverage automatically means both people have the same level of protection.
Age, health history, treatment needs and policy conditions may differ between spouses. If one spouse is covered through the other’s employer, the effect of retirement on that cover also needs to be understood.
Review both spouses’ coverage separately and identify what each person may need to pay if insurance does not cover the full expense.
Insurance Is Only One Part of the Healthcare Plan
Even a well-understood health insurance policy does not necessarily eliminate all healthcare spending.
Regular medicines, consultations, diagnostic tests, physiotherapy, dental or vision care and certain forms of home care can create expenses outside a hospitalisation claim. Policy conditions can also leave you with part of an eligible expense to pay yourself.
This is where a separate healthcare reserve can provide another layer of protection.
Read How Much Should You Keep Aside for Healthcare in Retirement? to understand the role of that reserve.
GreySmiles Take
Having health insurance and having enough health insurance are two different things.
As you approach retirement, do not judge your policy only by the sum insured or the premium. Look at what the policy actually protects, what you may still have to pay yourself and whether you can continue to maintain that protection after your salary stops.
Insurance is also not the entire healthcare plan. Your retirement finances should leave room for healthcare expenses that fall outside the policy and for changing healthcare needs over time.
The useful question is not “How much insurance should I buy?” It is “What healthcare risk am I protected against, what risk remains, and can my retirement plan handle the difference?”
A Practical Health Insurance Adequacy Check
Keep your policy documents in front of you and work through these questions rather than relying on what you remember about the cover.
- What is my current sum insured?
- Is the cover individual or shared?
- What co-payment or deductible applies?
- Are there room-rent or other sub-limits?
- Which major exclusions apply?
- Are there waiting periods that are still relevant?
- What expenses am I likely to pay myself?
- Can I comfortably afford the premium after retirement?
- What happens to my coverage if employment ends?
- Does my spouse have adequate protection separately?
- Do I have an accessible healthcare reserve for expenses insurance does not cover?
- When did I last review the policy against my current circumstances?
What People Get Wrong About Health Insurance in Retirement
A common mistake is to treat the sum insured as the same thing as actual financial protection.
Your real exposure depends on the policy terms, what the insurer will pay, what you may have to contribute yourself, what falls outside the policy and whether you can afford the cover as you get older.
Another mistake is to think of insurance as the entire healthcare plan. Insurance can protect against significant covered medical expenses, but it does not necessarily eliminate regular healthcare spending or every unexpected cost.
A more realistic way to think about healthcare resilience is:
Insurance protection + Healthcare reserve + Ability to absorb uncovered costs.
If Your Health Insurance Seems Inadequate, Find the Gap First
If your current cover appears inadequate, first identify why.
The issue may be the sum insured, policy limits, co-payment, exclusions, affordability or a gap between your expected healthcare needs and the protection available.
Once you understand the specific gap, you can review the available options rather than simply buying more cover because a larger number feels safer.
What Should You Check in Your Policy Documents?
For an important retirement-healthcare decision, do not rely only on what you remember about your policy or on a generic insurance checklist.
Your current policy wording, schedule and renewal documents tell you the actual terms of your cover, including the sum insured, exclusions, waiting periods, co-payments, deductibles, sub-limits and other conditions.
The headline sum insured does not tell you what you will necessarily receive when a claim occurs.
For regulatory and consumer information, refer to the Insurance Regulatory and Development Authority of India (IRDAI).
What If Retirement Is Only a Few Years Away?
Do not wait until the final few months.
Start by documenting your current employer cover and your personal insurance. Find out exactly what changes when employment ends and understand what your post-retirement arrangement could look like.
Then bring the expected premiums and out-of-pocket costs into your retirement spending and corpus assumptions. If the numbers are uncomfortable, you still have time to review the situation rather than being forced into a decision after retirement.
Frequently Asked Questions
How much health insurance is enough after retirement?
There is no universal amount that is sufficient for every retiree. The appropriate level of cover depends on factors such as age, health, location, family circumstances, existing coverage, policy terms and your ability to meet expenses that are not covered by insurance.
Is a higher sum insured always better?
Not necessarily. A higher sum insured can provide more protection, but you also need to examine co-payments, deductibles, exclusions, waiting periods, sub-limits and the affordability of the policy over time.
What expenses might I still have to pay even with health insurance?
Depending on your policy, you may have to pay co-payments, deductibles, excluded items or expenses subject to policy limits. Regular medicines, consultations, diagnostic tests and certain forms of outpatient or home care may also create costs outside a hospitalisation claim.
Does employer health insurance automatically continue after retirement?
Not necessarily. The outcome depends on the employer’s arrangement and applicable policy terms. Find out before retirement when your cover ends and whether any migration or continuation option is available.
Should I keep a separate healthcare reserve if I have health insurance?
A separate healthcare reserve can provide additional financial flexibility for expenses that insurance does not fully cover. The appropriate amount depends on your insurance, age, health needs, family circumstances and overall financial position.
Should couples assess their health insurance separately?
Yes. Even when a couple has family coverage, each person’s age, health history, treatment needs and insurance conditions may be different. Reviewing both spouses separately can reveal gaps that are not obvious when looking only at the household’s total coverage.
Should health insurance premiums be included in retirement expenses?
Yes, if you expect to pay them yourself after retirement. Premiums are part of the household’s ongoing retirement spending and should be reflected in your retirement assumptions.
The Bottom Line
The question is not simply whether you have health insurance. It is whether you understand what that insurance actually protects, what you may still have to pay yourself and whether you can maintain the cover after retirement.
Review the policy terms, understand the effect of co-payments, deductibles, exclusions and limits, check what happens to employer coverage, and consider the healthcare reserve that sits alongside your insurance.
You do not need to predict every medical expense you will ever have. You do need to make sure that losing an employment benefit or facing an uncovered healthcare expense does not become an unexpected financial problem when your salary stops.
Sources & References
Insurance Regulatory and Development Authority of India (IRDAI)
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.