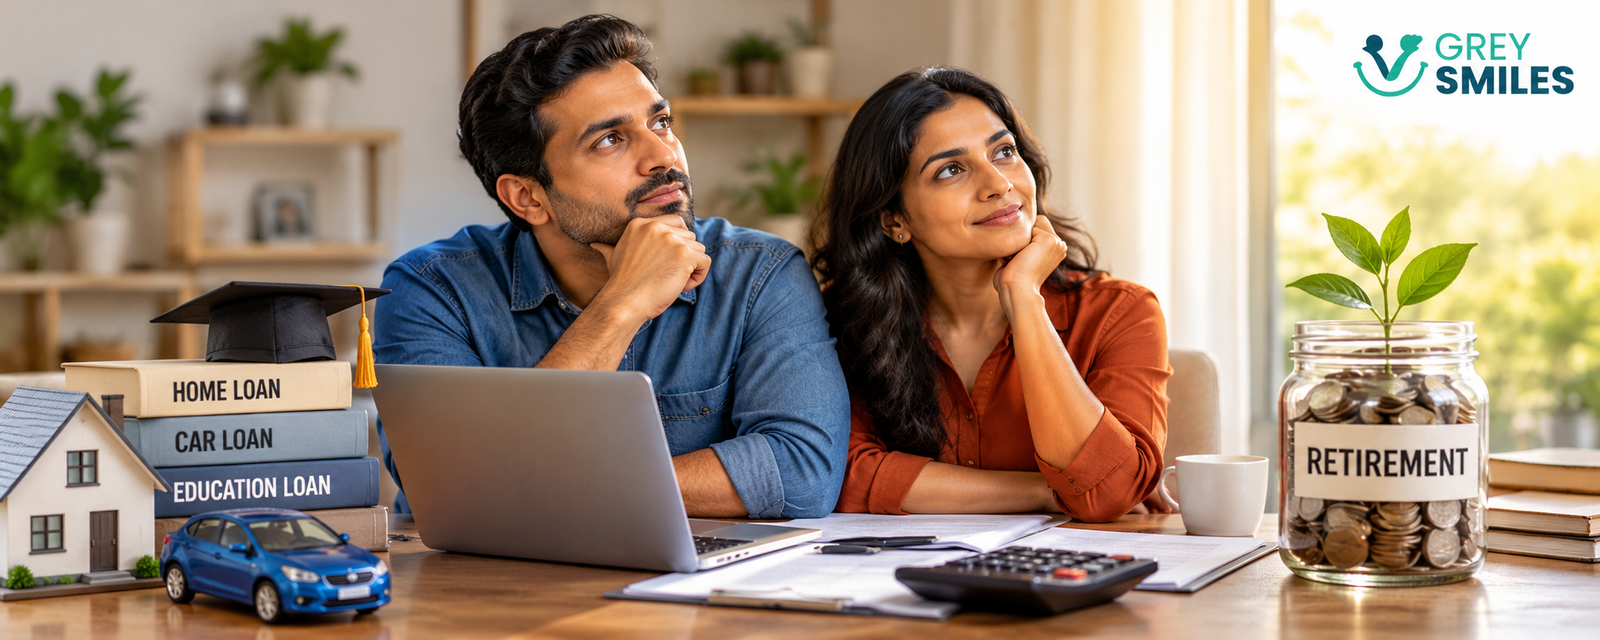
The point is not to stop taking loans or to feel guilty about spending money on your family. It is to recognise that the financial decisions you make today can determine how much freedom you have tomorrow.
At a Glance
- Loans can help finance purchases today, but they cannot replace a retirement income plan.
- EMIs and rising family expenses can quietly reduce the money available for long-term savings.
- Depending entirely on working longer can leave your retirement plans vulnerable to health, employment and family circumstances.
- Estimating your future expenses and reviewing your retirement readiness can help you decide what to do next.
We Know How to Finance the Life We Want Today
Think about the big financial decisions many families make. A home loan helps them buy a house before they have saved its entire cost. A car loan makes a vehicle more affordable through monthly instalments. An education loan can help a child pursue a course that might otherwise be difficult to fund.
These are not necessarily bad decisions. A loan can be useful when the repayment is manageable and the borrowing supports a considered goal.
The difficulty begins when every new financial commitment is treated as a monthly payment to accommodate, while retirement savings are left to whatever remains at the end of the month.
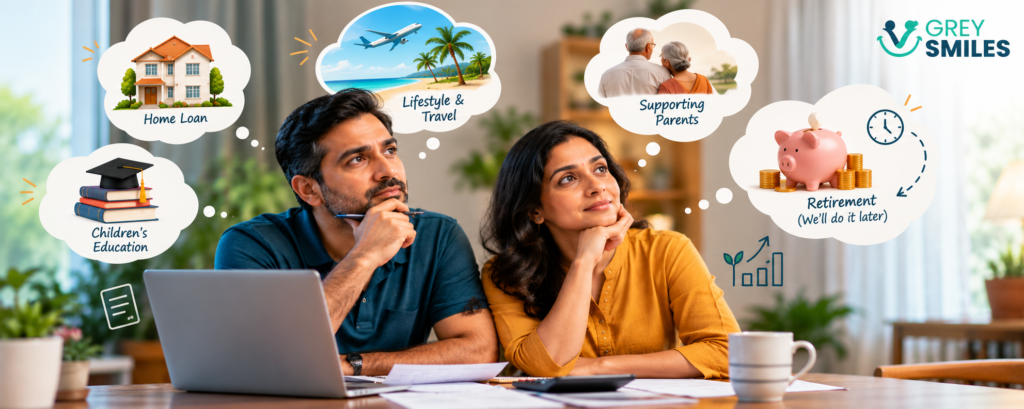
In your 30s, retirement may seem far away. In your 40s, school fees, a home loan, parents’ needs and career responsibilities may feel much more urgent. It is easy to keep postponing retirement contributions because there is always another priority.
If this sounds familiar, you may also find it useful to read our guide to retirement planning for salaried employees in India.
Why Retirement Does Not Work Like a Purchase
A loan helps you bring a purchase forward and repay its cost over time. Retirement planning works in the opposite direction: you need to build resources today to support expenses that may continue for decades after your salary stops.
There is no guaranteed future employer who will lend you your retirement income. Nor can you assume that your children will be able to support you financially, even if they want to.
Your retirement resources may need to pay for housing, food, healthcare, travel, household help and the ordinary pleasures that make life meaningful. Inflation can also make these expenses substantially higher over time.
Starting earlier gives your savings more time to grow. Starting later does not make planning pointless, but it can mean that you need to save more, review your assumptions carefully or reconsider some future expenses.
How EMIs Can Crowd Out Retirement Savings
One EMI may be manageable. Several instalments, combined with school fees, insurance premiums, household expenses and support for parents, can leave surprisingly little room for long-term saving.
The problem is not always the size of a single purchase. It is the cumulative effect of financial commitments that continue for years.
Consider a common pattern: a salary increase arrives, household spending rises, a new loan is taken, and retirement contributions remain unchanged. Income has grown, but the amount being set aside for the future has not kept pace.
A useful first step is to review your monthly commitments and distinguish between:
- Essential expenses: housing, food, utilities, healthcare and other necessities.
- Financial commitments: EMIs, insurance premiums and other contractual payments.
- Flexible spending: discretionary purchases and expenses that can be adjusted.
- Future-focused contributions: retirement investments, emergency savings and other long-term goals.
This review is not about eliminating every pleasure from your present life. It is about ensuring that your future is not funded only if money happens to be left over.
What If You Expect to Work Longer?
Many people assume they can work until 65, 70 or even longer. Continuing to work may be a welcome choice, especially if you enjoy your profession and remain healthy. It is less reassuring when working longer becomes the only way your retirement plan can succeed.
Employment may change because of health, caregiving responsibilities, industry shifts, redundancy or a desire to slow down. Self-employment and consulting can also bring irregular income rather than a dependable salary.
It is sensible to consider later-life work as one possible source of income. It is risky to build an entire retirement plan around the assumption that suitable work will always be available.
Use your expected retirement age as a planning assumption, then test what happens if you stop working earlier or earn less than expected. A plan that remains workable under more than one scenario gives you greater flexibility.
What About Your House? Can You Borrow Against Your Assets?
You may own a home or other assets that could potentially support you financially later in life. Depending on the circumstances, options such as downsizing, renting out a property or exploring a suitable loan against property may be considered.
These options are not interchangeable with a dedicated retirement income plan. Property may be valuable but difficult to convert into regular cash without selling it, moving, taking on repayment obligations or accepting other risks.
Borrowing against an asset can also introduce costs and obligations at a stage when dependable income may be limited. Any such decision requires careful review of the terms, alternatives, family circumstances and long-term implications.
Your home can be an important part of your retirement picture. It should not automatically be treated as if it were cash available for everyday expenses.
Estimate What Your Retirement May Need
Retirement planning becomes more practical when you move from a vague concern about the future to an estimate you can review. Start with the lifestyle you expect, the age at which you would like to stop working, your existing savings and investments, and the income you may receive after retirement.
Next, consider inflation, healthcare costs, your expected retirement duration and the returns your investments might earn. These are estimates rather than guarantees, so test different assumptions instead of relying on a single number.
Put Your Retirement Numbers to Work
Use the GreySmiles retirement resources to estimate the corpus you may need and assess how prepared you are. The results are planning estimates, not guaranteed outcomes or personalised financial advice.
Estimate Your Retirement Corpus
You do not need perfect figures before you begin. A realistic first estimate can reveal whether your current savings rate, retirement age and expected lifestyle are broadly aligned.
You Do Not Have to Choose Between Today and Tomorrow
It is easy to read an article about retirement and conclude that you should stop spending, avoid every loan and invest every spare rupee. That is rarely a realistic way to manage a family’s finances.
You may need a home. Your children’s education may matter deeply to you. Your parents may need support. You may also want to travel, enjoy life and make room for experiences while you are healthy and active.
The aim is to balance these priorities rather than allow the most immediate one to consume all your financial capacity.
Start by asking yourself five questions:
- How much do I currently contribute to retirement savings each month?
- Have those contributions increased as my income has grown?
- How much of my take-home income is committed to EMIs and other fixed payments?
- What would happen if I had to stop working earlier than planned?
- When did I last estimate my retirement needs using updated expenses and assumptions?
Your answers can help identify a practical next step. You might increase your retirement contribution gradually, review expensive debt, redirect part of a loan repayment once it ends, or revisit your expected retirement date and lifestyle.
If you are approaching retirement with outstanding debt, our article on retiring with debt can help you think through the issue. You can also explore the six stages of retirement planning to place your next step in the wider planning journey.
The GreySmiles Take
A loan can help you pay for something you need or value today. Retirement savings help protect your ability to make choices when a regular salary is no longer there.
You do not need to solve your entire retirement plan this month. You do need to stop treating it as the one financial goal that can always wait.
Give your future a place in today’s budget, before every other commitment takes that place away.
Frequently Asked Questions
Can I prioritise my home loan over retirement savings?
Your home loan and retirement plan both matter. The right balance depends on the interest rate, remaining loan term, cash reserves, age, income stability and existing retirement investments. Avoid assuming that retirement saving must stop until every loan is repaid.
Is it too late to start retirement planning in my 40s?
No. Starting in your 40s can leave less time for savings to grow, but a clear estimate and consistent contributions can still improve your position. You may need to review your expected retirement age, savings rate and future spending.
Can my house fund my retirement?
A house may contribute to retirement security, but its value does not automatically provide regular income. Consider maintenance costs, whether you will continue living there, the possibility of downsizing or renting, and the risks and costs of borrowing against the property.
How much should I save for retirement each month?
There is no single amount that suits everyone. It depends on your age, current corpus, expected retirement age, lifestyle, other income sources and assumptions about inflation and investment returns. Use a retirement-corpus estimate as a starting point and review it regularly.
What is the first step if I have several EMIs?
List every loan, its outstanding balance, interest rate, monthly instalment and remaining term. Review your emergency savings and essential expenses, then decide how to manage debt while preserving a realistic retirement contribution. Avoid taking on additional debt without understanding its impact on your future cash flow.
Disclaimer: This article is for general educational purposes only and should not be treated as personalised financial, investment, tax or legal advice. Calculator outputs and retirement estimates depend on the assumptions and information entered and are not guarantees of future results. Consider your individual circumstances and consult a qualified professional where appropriate.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.