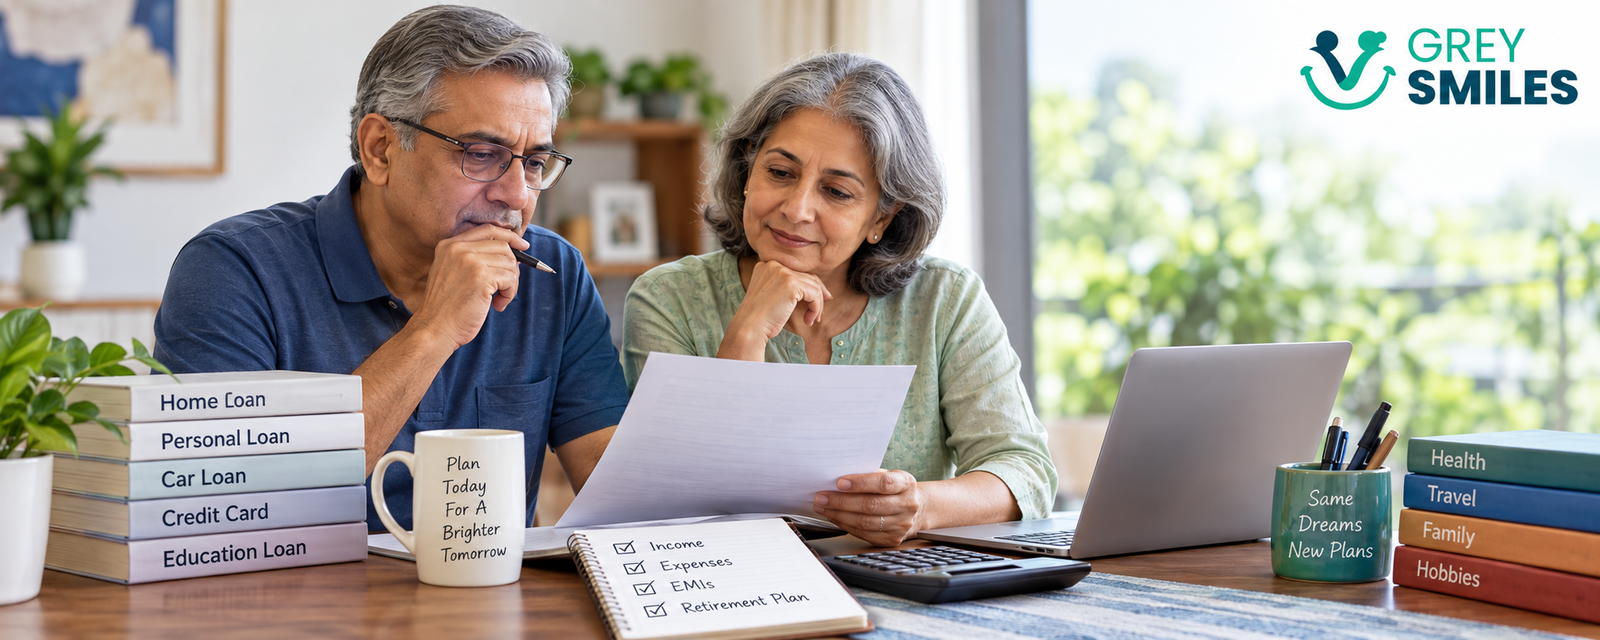
Reviewing loans, EMIs and retirement finances before making the decision to retire.
Written by Kartikey Gupta: He is a finance professional with 6+ years of experience across capital markets, insurance and financial services. He is a CMT and CFA Level II qualified professional and writes on retirement planning, investing and financial security.
At a Glance
Having debt does not automatically mean you cannot retire. The more useful question is whether your retirement income, savings and expected spending can comfortably support the debt you still have.
- The type of loan matters. A home loan is different from a credit-card balance or an expensive personal loan.
- High-cost, unsecured debt generally deserves more attention before retirement.
- A manageable EMI may be possible after retirement if your regular income can comfortably support it.
- Using your retirement corpus to become debt-free can reduce monthly pressure, but it also reduces the money available for the rest of your retirement.
- The decision should be based on cash flow, loan cost, remaining tenure and the corpus left after repayment.
Many people reach their 50s or early 60s with some debt still outstanding. It could be a home loan that has not yet been fully repaid, a car loan, a personal loan, an education loan taken for a child, or a loan against property. Some households may also be carrying credit-card balances or other short-term borrowing.
That can make retirement planning feel more complicated. The question is often framed very simply: Can I retire if I still have debt?
There is no universal answer. A ₹20 lakh home loan with a manageable EMI can present a very different situation from ₹5 lakh of high-cost unsecured debt. The loan interest rate, remaining tenure, EMI, expected retirement income and retirement corpus all matter.
So the objective is not necessarily to enter retirement with zero debt. It is to understand whether the debt you carry can comfortably fit into the retirement you are planning.
Does Having Debt Automatically Mean You Should Not Retire?
No. Being debt-free and being financially ready for retirement are two different things.
You could repay every outstanding loan and still have an inadequate retirement corpus. You could also enter retirement with a manageable home loan and have enough dependable income and savings to meet the EMI without compromising your essential expenses.
This is why debt needs to be considered alongside the rest of your retirement plan. The GreySmiles Retirement Readiness Test, for example, looks beyond the corpus number and considers areas such as income, healthcare, debt, housing and other retirement responsibilities.
The more useful question is therefore not simply, “Do I have debt?” It is, “Can my retirement plan comfortably carry this debt?”
First, Identify What Kind of Debt You Have
This is one of the most important distinctions to make before deciding whether you can retire with outstanding loans. Not all debt carries the same financial risk, and not all debt needs to be treated in the same way.
Look at each loan separately. Record the outstanding balance, interest rate, EMI and remaining tenure. Then consider whether the loan is secured against an asset, whether the borrowing is essential, and how much pressure it will put on your retirement income.
| Type of debt | What to consider before retirement |
|---|---|
| Credit-card debt | Revolving balances can be expensive. Carrying a substantial credit-card balance into retirement can create a continuing drain on cash flow and deserves close attention. |
| Personal loan | Personal loans are unsecured and can have relatively high interest costs. A large EMI may become harder to manage once salary income stops. |
| Car loan | Consider the outstanding amount, remaining tenure and whether the car is essential. A small balance close to the end of the loan may not justify using a large part of your retirement corpus to close it. |
| Education loan | Look at the interest cost, remaining tenure and who is responsible for repayment. A loan taken for a child can still become part of a parent’s retirement cash-flow burden. |
| Loan against property | The property is generally pledged as security. The outstanding balance, repayment schedule and ability to service the loan after retirement need careful consideration. |
| Home loan | A home loan does not automatically need to be cleared before retirement. The EMI, interest rate, remaining tenure and corpus available after repayment all need to be considered. |
| Family or informal borrowing | The financial cost may be low or zero, but the personal and family implications can still make repayment an important part of retirement planning. |
A useful rule of thumb is that high-cost, unsecured and cash-flow-heavy debt generally deserves more attention before retirement than a manageable, lower-cost loan that can comfortably be supported by retirement income. This is not a command to repay every personal loan or every unsecured loan immediately. The actual terms and your wider financial position still matter.
Which Loans Should You Try to Pay Off Before Retirement?
If you have several types of debt, prioritising them can be more useful than trying to become completely debt-free at any cost.
High-cost credit-card balances are usually worth addressing because the borrowing can become expensive very quickly when balances revolve from one billing cycle to another. Expensive personal loans can also deserve attention, particularly when the EMI takes up a meaningful portion of the income you expect to have after retirement.
Other unsecured borrowing should be looked at in the same way. If a loan carries a significant interest cost and creates a large fixed monthly obligation, removing it before retirement may improve your cash flow and reduce financial pressure.
Home loans require a different approach. A relatively manageable home loan may be perfectly compatible with retirement if the EMI is affordable, the remaining tenure is reasonable and you retain an adequate retirement corpus. Using a large portion of your savings simply to eliminate a manageable home loan can leave you with less liquidity for healthcare, living expenses and other retirement needs.
The key question is therefore not simply, “Which loan should I repay first?” It is “Which debt creates the greatest risk to my retirement cash flow?”
Why Debt Becomes Different After Retirement
The EMI does not become more expensive simply because you retire. What changes is your ability to generate additional income if the EMI becomes difficult to manage.
While you are working, salary increases, bonuses, consulting work or other employment income may provide some flexibility. Once you retire, your regular income may come from a pension, annuity, rental income, interest or withdrawals from your investments. Some of these sources may be relatively dependable, while others depend on your assets and how you manage them.
This is why an EMI that feels comfortable while you are earning should be tested against your expected retirement income. A ₹30,000 EMI may be manageable when the household has a strong salary, but it can feel very different when the only regular income is a pension and a modest rental income.
Your retirement budget should also include healthcare, insurance, home maintenance and other expenses that may not receive much attention in your current monthly budget. Our guide to how much you may need to spend in retirement looks at this broader expense question.
What If I Have a Home Loan?
The home loan is often the most difficult debt to evaluate because your home may be one of your most important assets and your largest financial commitment.
Suppose you have ₹20 lakh outstanding on a home loan and ₹60 lakh available in retirement savings. Paying the loan immediately would leave ₹40 lakh. Continuing the loan would preserve more savings, but the EMI would continue to reduce your monthly cash flow.
Neither option can be judged from those two numbers alone. You need to compare the cost of continuing the loan with the financial effect of reducing your corpus by ₹20 lakh.
Also consider how long the loan will continue. A home loan with three years remaining is a different retirement issue from one with fifteen years remaining. The longer the EMI continues, the more carefully you need to test whether your retirement income can support it.
A debt-free home can reduce your future housing costs, but it should not be treated as retirement income unless you actually intend to monetise it.
Should You Use Your Retirement Corpus to Repay Debt?
This is where the decision becomes more complicated. Repaying a loan can immediately reduce your monthly obligations and may make your retirement cash flow easier to manage. At the same time, the money used for repayment is no longer available as part of your retirement corpus.
That trade-off matters because retirement savings may need to support you for decades. The corpus may have to fund regular expenses, healthcare, emergencies, travel and other needs long after the loan has disappeared.
Consider the three broad choices:
| Choice | Potential benefit | Potential concern |
|---|---|---|
| Repay fully | The EMI disappears and monthly cash-flow pressure falls. | Your retirement corpus becomes smaller and liquidity may fall. |
| Continue the loan | More retirement savings remain available. | The EMI continues to reduce monthly cash flow. |
| Partly repay | May reduce the outstanding balance or repayment burden while retaining some liquidity. | The debt and EMI do not disappear completely. |
How Much Retirement Corpus Do You Need?
Before using a large part of your retirement savings to clear a loan, estimate the corpus you may need for the retirement years ahead. This gives the debt decision a wider context.
What If the Debt Continues Well Into Retirement?
Remaining tenure deserves as much attention as the outstanding balance. A loan that will be fully repaid within two years may not create the same retirement risk as one that continues for ten or fifteen years.
Start by looking at the period for which your retirement income will have to support the EMI. Then ask whether your regular income is sufficient to meet the EMI and your essential expenses without depending too heavily on investment withdrawals.
If the answer is no, you need to decide whether the loan should be reduced, repaid, refinanced where appropriate, or carried with a clearly understood withdrawal plan. The objective is not to eliminate debt mechanically. It is to prevent the debt from becoming a continuing source of financial stress.
What If I Have Several Loans?
Multiple loans can make the situation harder to understand because the combined EMI may matter more than any individual balance.
List every loan separately and record the outstanding amount, interest rate, EMI and remaining tenure. Then add the EMIs together and compare the total with the regular income you expect after retirement.
For example, a ₹3 lakh personal loan with a relatively high interest rate may deserve more immediate attention than a ₹20 lakh home loan with a lower rate and a manageable EMI. Similarly, a car loan with only six months remaining may not need the same treatment as a long-term loan that will continue through much of your retirement.
This exercise helps identify whether your real problem is the amount of debt or the monthly cash-flow burden created by that debt.
Can I Retire If My EMI Has to Come From My Retirement Corpus?
It is possible to use retirement savings to meet an EMI, but that should be treated as part of your retirement withdrawal plan rather than as a separate expense.
Suppose your retirement income covers your essential household expenses but leaves ₹20,000 a month short of the EMI. That ₹20,000 has to come from somewhere. If it comes from investments, your annual withdrawal requirement is higher than it would be without the loan.
This matters because your retirement corpus is not simply a bank balance to be drawn down whenever there is a shortfall. It may need to support you for many years, and withdrawals interact with market returns, inflation and the remaining portfolio.
If you expect to use systematic withdrawals from investments, you can explore the GreySmiles SWP Calculator to understand the withdrawal requirement. The calculator does not determine whether you should repay the loan, but it can help you examine the cash-flow side of the decision.
Debt Can Change How Much Retirement Corpus You Need
Your retirement corpus requirement is influenced by the expenses your investments will ultimately need to support. An EMI that continues after retirement is therefore part of that picture.
Consider an EMI of ₹30,000 a month continuing for five years. That represents ₹18 lakh of scheduled payments over the period before considering the interest component or any changes in the loan. You do not necessarily need ₹18 lakh sitting separately in cash, but the obligation cannot be ignored when you assess whether your retirement resources are sufficient.
This is one reason why a retirement corpus calculation should be based on your actual expected spending and income rather than on an arbitrary corpus target.
What If Paying Off the Debt Leaves Me With Too Little?
This is perhaps the most important question to ask before making a large lump-sum repayment.
Imagine that you have ₹80 lakh in retirement savings and ₹25 lakh outstanding on a loan. Repaying the loan would leave ₹55 lakh. The fact that you have eliminated a ₹25 lakh liability may feel reassuring, but the next question is whether ₹55 lakh is enough to support your retirement spending, healthcare requirements, emergencies and other commitments.
Retirement can last for decades. A large repayment made shortly before retirement can therefore have consequences that last much longer than the loan itself would have.
If you are unsure whether your existing resources are sufficient, look at the broader question of whether you have enough money to retire before committing a large part of the corpus to debt repayment.
What If Debt Makes Retirement Uncomfortable?
There is also a personal dimension to the decision. Two households with the same loan balance, EMI and retirement corpus may make different choices because their tolerance for financial commitments is different.
Some retirees may be comfortable carrying a manageable home loan when they have adequate regular income and liquidity. Others may prefer to remove the EMI before retirement because the certainty of lower monthly commitments matters to them.
That preference can be part of a sensible retirement plan, provided the financial consequences are understood. Becoming debt-free should not leave you without enough money to handle the years of retirement that follow.
GreySmiles Take
Debt is not automatically a retirement blocker. The type of debt, its cost and its impact on your retirement cash flow matter more than simply having a loan outstanding. High-cost, unsecured debt may deserve priority before retirement, while a manageable home loan can sometimes be carried if your income and corpus can support it. The aim is not merely to retire debt-free. It is to enter retirement with enough financial room for the years ahead.
A Simple Debt-and-Retirement Check
Before making a decision, put your expected retirement income and expenses on one page. Start with the income you can reasonably depend on and then subtract your essential household expenses, EMI and other fixed commitments.
| Monthly item | Amount |
|---|---|
| Regular retirement income | ₹ ______ |
| Essential retirement expenses | ₹ ______ |
| Loan EMI | ₹ ______ |
| Other recurring commitments | ₹ ______ |
If your regular retirement income comfortably covers essential expenses and the EMI, carrying the loan may be manageable. If there is a significant shortfall, work out how that gap will be funded and for how many years.
That is ultimately the central calculation. You are not simply deciding whether to carry debt. You are deciding whether your retirement income and retirement corpus can support the debt without compromising the rest of your retirement plan.
Debt-Before-Retirement Checklist
Before retiring with outstanding debt, make sure you know the answers to these questions:
- What type of debt do I have?
- What is the interest rate on each loan?
- How much do I owe today?
- What is the EMI for each loan?
- How many months or years remain on each loan?
- Which loans are creating the greatest monthly cash-flow pressure?
- What would my retirement corpus look like if I repaid each loan?
- How much regular income will I have after retirement?
- Will that income comfortably cover essential expenses and EMIs?
- If not, how much will I need to withdraw from my investments?
- After repaying the debt, will I still have enough liquidity for emergencies and healthcare?
Once you have these numbers, you can bring debt into your broader retirement planning process rather than treating it as a separate problem.
Frequently Asked Questions
Can I retire with a home loan?
Yes. A home loan does not automatically prevent retirement. The decision depends on the EMI, interest rate, remaining tenure, expected retirement income and the corpus you will retain while continuing the loan. A manageable EMI supported by dependable income may be very different from a large EMI that requires regular withdrawals from your retirement savings.
Which loans should I try to repay before retirement?
High-cost, unsecured and cash-flow-heavy debt generally deserves closer attention. Credit-card balances and expensive personal loans can be particularly important because they may combine relatively high borrowing costs with significant monthly obligations. That does not mean every such loan must be repaid immediately. The decision should also consider your available liquidity and the effect repayment would have on your retirement corpus.
Should I always repay my home loan before retirement?
No. A home loan should be evaluated on its actual terms. If the EMI is manageable, the remaining tenure is reasonable and you have sufficient retirement resources, continuing the loan may be possible. Repaying it may make sense when the EMI creates significant pressure or when eliminating the debt materially improves your retirement cash flow without leaving you short of savings.
Should I use my retirement corpus to clear my loan?
It depends on the loan cost, outstanding balance, EMI, remaining tenure and the corpus you will have left after repayment. Clearing expensive debt may reduce financial pressure, but using too much of your retirement savings can create a larger problem if the remaining corpus is insufficient for your future needs.
What if my EMI continues after retirement?
Include it in your retirement cash-flow calculation. The key is to understand whether your regular retirement income can cover the EMI along with essential expenses. If you need investment withdrawals to fund the EMI, those withdrawals should be included in your overall retirement-income plan.
Is it better to be debt-free or have a larger retirement corpus?
Neither is automatically better. Being debt-free can reduce fixed monthly commitments, but a larger corpus provides greater liquidity and may be important for long-term retirement spending. The better outcome is the one that leaves your overall retirement plan financially workable rather than simply maximising one number.
What if I have several different loans?
List each loan separately and compare its interest cost, EMI and remaining tenure. You may find that one relatively expensive loan is creating more retirement risk than a much larger but manageable home loan. Looking at the total EMI burden alongside the individual loans can help you decide where the greatest pressure lies.
Can I retire if my loan EMI has to come from my investments?
Possibly, but the withdrawal needs to be part of your retirement plan. If investment withdrawals are required to meet the EMI, your portfolio needs to support both your normal retirement spending and the additional debt obligation. The longer the loan continues, the more important this becomes.
Sources & References
- Reserve Bank of India, financial education and consumer banking resources.
- SEBI investor education resources.
- GreySmiles retirement planning resources and calculators.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.