
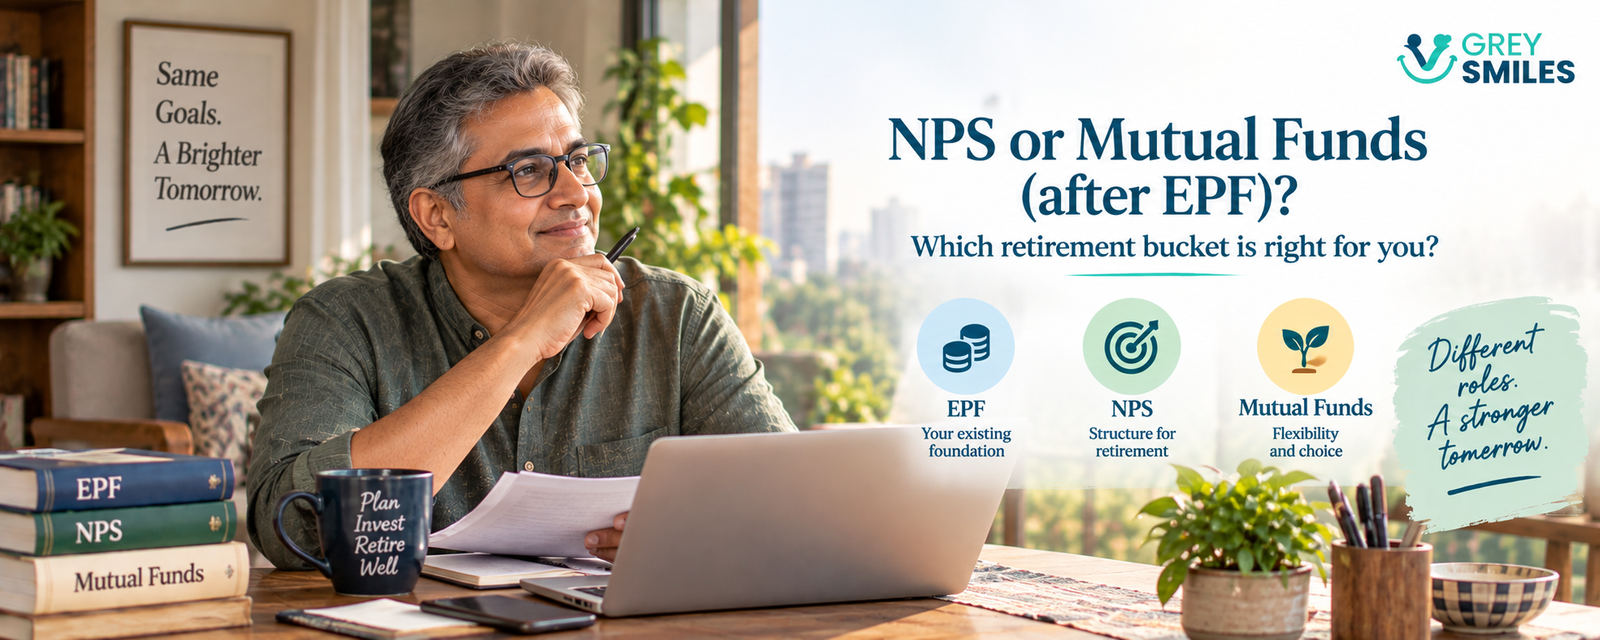
NPS and mutual funds can play different roles alongside EPF in a retirement plan
Written by Kartikey Gupta: He is a finance professional with 6+ years of experience across capital markets, insurance and financial services. He is a CMT and CFA Level II qualified professional and writes on retirement planning, investing and financial security.
These questions matter because NPS and mutual funds are not simply two products competing for the same money. They give you different combinations of structure, flexibility, investment choice and access.
At a Glance
NPS is built specifically around retirement savings and has its own rules for investment, withdrawal and exit. Mutual funds can also be used to build retirement wealth, but they generally give you more choice and flexibility over how the money is invested and accessed.
If you already have EPF, the decision may not be NPS versus mutual funds for your entire retirement corpus. It may be about deciding which part of your retirement money needs structure and which part needs flexibility.
Start With the Money You Already Have
This is where retirement investing often becomes unnecessarily complicated.
A salaried person may already have EPF building up through employment. There may also be PPF, existing mutual funds, bank deposits, property and other investments. Adding NPS to the mix does not automatically make the retirement plan better.
First look at the whole picture.
If EPF is already providing one relatively stable component of your retirement savings, your additional investments may have a different job. They may need to provide long-term growth, greater liquidity, diversification or eventually a source of retirement income.
That is why the same NPS contribution can make sense for one person and be less useful for another.
GreySmiles has already looked at this broader principle in smart investment options for retirement in India: the aim is not to collect investment products, but to build a portfolio in which each part has a clear role.
NPS and Mutual Funds Are Built Differently
NPS is a retirement-focused investment structure regulated by the Pension Fund Regulatory and Development Authority. You contribute to the account, choose from the investment options available within the NPS framework and build a retirement corpus subject to the applicable rules.
Mutual funds are investment schemes that can be used for many different goals, including retirement. Depending on the scheme, they can give you exposure to equity, debt or a combination of assets.
That distinction is important. NPS starts with the assumption that the money is meant for retirement. A mutual fund does not know what the money is for. You decide that.
For the latest information on the NPS framework, investors should refer to the PFRDA NPS All Citizen Model information.
The Real Comparison Is Not About Returns
It is tempting to compare the returns of NPS and a mutual fund and stop there. That can be misleading.
Neither NPS nor mutual funds have one single return. The outcome depends on the assets chosen, the allocation between them, the investment period and market performance. A better comparison asks what you are getting in exchange for the restrictions and flexibility of each approach.
| Consideration | NPS | Mutual Funds |
|---|---|---|
| Primary purpose | Retirement-focused investing | Can be used for retirement and other financial goals |
| Investment choice | Choices within the NPS framework | Wide range of schemes and asset categories |
| Access | Subject to NPS withdrawal and exit provisions | Generally more flexible, subject to scheme and applicable rules |
| Retirement discipline | Built into the structure | Depends largely on the investor |
| Tax treatment | Specific provisions may apply | Depends on fund type, holding period and prevailing tax rules |
| Role after retirement | Subject to the applicable NPS exit and withdrawal framework | Can provide a flexible pool from which withdrawals may be planned |
When NPS Can Make Sense
NPS can make sense when you want a part of your retirement savings to be clearly earmarked for retirement rather than remaining available for every financial goal that comes along.
That discipline can be useful. Money that is mentally labelled “retirement” can still be tempting to use for a child’s education, a house renovation or an unexpected family requirement. A retirement-focused structure creates a stronger boundary around it.
NPS can also be relevant when its tax treatment or an employer contribution makes it attractive in your particular circumstances. A tax benefit, however, should not be allowed to make the entire decision for you. The money still has to fit into the retirement plan you are building.
When Mutual Funds Can Make More Sense
Mutual funds may be more useful for the part of your retirement portfolio where you want greater choice and flexibility.
For example, you may want a long-term growth component while you are still 15 or 20 years away from retirement. Later, you may want to change the mix as retirement approaches or keep a portion of the corpus available for expenses that cannot be predicted today.
Mutual funds can also sit outside your retirement bucket. The same investment account may be used for another long-term goal, although mixing goals without a clear plan can make it harder to know whether you are actually on track for retirement.
That flexibility is useful, but it also means there is less structural discipline. You have to provide that discipline yourself.
If you are considering mutual funds specifically as part of your retirement portfolio, GreySmiles has a more detailed guide on how to choose mutual funds for retirement in India.
If You Already Have EPF, Think About the Gaps
This is where the comparison becomes much more relevant for salaried employees.
EPF may already be building a significant part of your retirement savings. Instead of automatically adding another retirement product, look at what the existing portfolio is missing.
Perhaps you need more long-term growth. Perhaps you need greater liquidity. Perhaps your retirement corpus is adequate but your expected retirement income is not. Or perhaps you are taking more investment risk than you realise because several of your holdings are exposed to the same asset class.
GreySmiles already makes this point in its retirement planning guide for salaried employees: EPF is an important building block, but it does not automatically mean the entire retirement plan is complete.
If you are relying heavily on EPF and wondering how far it can take you, it is also useful to understand the reality of retiring early with EPF rather than looking at EPF in isolation.
Don’t Build a Retirement Portfolio by Counting Products
You can have EPF, NPS, PPF, mutual funds, fixed deposits and gold and still have a poorly organised retirement portfolio.
The problem may not be the products. It may be the allocation.
Suppose most of your money is already in relatively stable assets. Adding another similar product may not solve the problem you actually have. On the other hand, if too much of your retirement money is exposed to market volatility and you are approaching retirement, adding still more growth-oriented investments may increase the risk you are trying to manage.
Look at the portfolio as one household balance sheet rather than a collection of accounts.
A Better Way to Think About Your Retirement Money
| Money needed for retirement | Should remain focused on the long-term retirement requirement. |
| Money needed before retirement | Needs appropriate liquidity and should not depend on retirement-only structures. |
| Money needed for growth | Needs a long enough horizon to absorb market fluctuations. |
| Money needed soon after retirement | Needs to be considered separately from money intended to remain invested for many years. |
Once you divide the problem this way, choosing between NPS and mutual funds becomes less about finding a winner and more about filling the right gap.
What About Tax Benefits?
Tax treatment can make NPS attractive, but it should be considered alongside liquidity and retirement needs rather than in isolation.
Your tax position can also change over your working life. The regime you use, your income, employer contributions and the applicable deductions can all affect the value of a particular tax benefit.
For example, the Income Tax Department’s current guidance sets out specific provisions relating to NPS contributions, including provisions under Section 80CCD. The applicable treatment depends on the circumstances and tax regime, so the latest Income Tax Department guidance should be checked before making a decision based primarily on tax savings.
Tax rules change. Before making a decision based primarily on tax savings, check the current provisions rather than relying on an older article or a rule remembered from a previous financial year.
GreySmiles also has a practical guide to tax planning for retirees if you want to understand how taxation fits into the broader retirement-income picture.
What Happens When You Actually Retire?
This is the part that often gets missed when people compare investments during their working years.
Building a corpus and using a corpus are two different problems.
With mutual funds, you generally have greater flexibility over when and how much you redeem, subject to the applicable scheme and tax rules. That can be useful when retirement expenses change from year to year.
NPS has its own exit and withdrawal framework. The rules have changed over time and were amended again in 2026, so an old assumption that retirement simply means “60% lump sum and 40% annuity” is no longer a sufficient description of the current framework.
For current NPS exit and withdrawal provisions, refer to the latest PFRDA regulations and guidance.
Whichever route you use, the bigger retirement question remains the same: how much income will your accumulated money need to generate, and for how long?
Once you start thinking about the corpus as a future source of income, Kartikey Gupta’s GreySmiles article on how much monthly income a retirement corpus can generate becomes a useful next step.
Don’t Forget the Income Gap
Imagine you expect to spend ₹1 lakh a month in retirement.
If pension and other dependable income cover ₹40,000, the investment portfolio has to provide the remaining ₹60,000. That gap is more important than whether the money happens to sit in NPS or mutual funds today.
You need to know whether the corpus can support that requirement, how inflation could change the amount and what happens if investment returns are poor during the early years of retirement.
Before choosing where the next retirement rupee should go, it is worth working out how much retirement corpus you may actually need.
The GreySmiles retirement calculators can then help you work through the corpus and withdrawal side of this planning exercise.
GreySmiles Calculator
Before Choosing Where to Invest, Know the Number
Your investment decision becomes much clearer when you know the retirement corpus you are trying to build. The GreySmiles Retirement Corpus Calculator lets you work from current expenses, inflation, retirement age and expected returns to estimate the corpus you may need.
Calculate Your Retirement Corpus →
Illustrative planning tool. Actual investment outcomes will vary.
So Where Should Your Retirement Money Go?
There is no reason to put every retirement rupee into NPS simply because it is designed for retirement. There is also no reason to put everything into mutual funds simply because they offer greater flexibility.
Look at what you already have first.
If EPF is already providing part of the retirement foundation, NPS may be useful for another defined portion of your retirement savings, particularly where its structure and applicable tax treatment fit your circumstances. Mutual funds may then provide the flexibility and investment choice needed elsewhere in the portfolio.
Someone with no EPF, a large retirement gap and a long investment horizon may reach a different conclusion. Someone five years from retirement with a substantial corpus may reach another.
The product should follow the retirement plan, not the other way around.
GreySmiles Take
NPS and mutual funds do not need to compete for the title of “best retirement investment”. They can do different jobs.
If you already have EPF, PPF or other retirement assets, start there. Understand what those assets already provide and then look at what is missing.
The better question is not “NPS or mutual funds?” It is “What does this next rupee of retirement money need to do for me?”
Frequently Asked Questions
Is NPS better than mutual funds for retirement?
Neither is automatically better. NPS provides a retirement-focused structure with specific exit and withdrawal provisions, while mutual funds generally provide greater choice and flexibility. The right combination depends on your existing retirement assets, time horizon, liquidity needs and retirement-income plan.
Can I invest in both NPS and mutual funds?
Yes. They can serve different purposes within the same retirement plan. For example, NPS may form one part of a dedicated retirement corpus while mutual funds provide additional flexibility and investment exposure.
If I already have EPF, do I need NPS?
Not necessarily. EPF is already an important retirement-building block for eligible employees. Whether NPS adds value depends on your overall corpus requirement, tax position, investment horizon, liquidity needs and the role you want each part of your retirement portfolio to play.
Which gives better returns, NPS or mutual funds?
There is no single answer. Both can have different asset allocations and investment choices, so returns depend on what you invest in and how long you remain invested. Comparing the labels alone does not tell you which option will work better for your retirement.
Can NPS and mutual funds be used to generate retirement income?
Yes, but they work differently when you reach retirement. Mutual funds can generally be used as a flexible investment corpus from which withdrawals may be planned, while NPS has its own exit and withdrawal provisions. Your retirement-income strategy should consider the entire corpus rather than one investment account in isolation.
Should tax saving be the main reason to choose NPS?
No. Tax treatment can be an important consideration, but retirement investments also need to fit your liquidity requirements, risk tolerance, time horizon and eventual income needs. A tax benefit is useful only if the underlying investment fits the broader plan.
Sources & References
- Pension Fund Regulatory and Development Authority (PFRDA): NPS All Citizen Model
- Pension Fund Regulatory and Development Authority (PFRDA)
- Income Tax Department of India
NPS provisions, tax rules and investment regulations can change. Check the latest information from the relevant official sources before making a financial decision. This article is intended for general educational purposes and does not constitute personalised financial advice.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.