
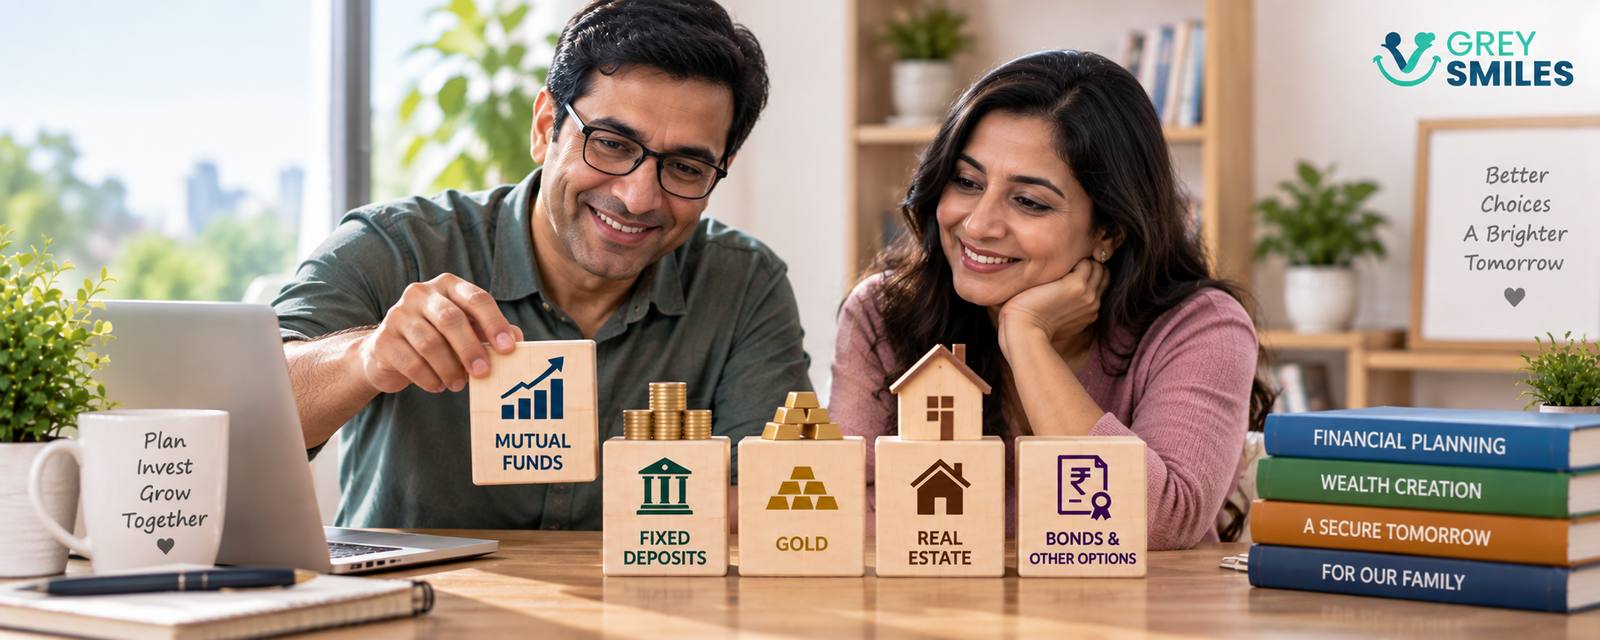
Different investment options can serve different roles in building and managing a retirement portfolio.
Choosing investments for retirement is often presented as a search for the “best” option. Should you buy stocks? Mutual funds? Fixed deposits? Real estate? Gold? NPS? PPF? The harder question is not which investment is best in isolation. It is what job each investment needs to perform inside your retirement plan.
A retirement portfolio has to do several things at once. It needs to grow over a long period, provide stability when markets fall, remain accessible when money is needed and eventually help generate income after employment stops. That makes retirement investing different from simply trying to maximise returns.
There Is No Single Best Retirement Investment
Every investment comes with a trade-off.
Equity can provide long-term growth but can fall sharply over shorter periods. Fixed-income investments can provide greater stability but may struggle to keep pace with inflation over very long periods. Real estate can create substantial wealth but may be difficult to sell when cash is needed. Gold can diversify a portfolio but does not generate regular income in the way an interest-bearing asset can.
The objective is therefore not to find one investment that does everything.
It is to combine investments so that the overall portfolio is capable of meeting the different demands of retirement.
Start With the Retirement Goal, Not the Product
Before deciding where to invest, establish what the portfolio eventually needs to fund.
Your retirement calculation should begin with expected spending, dependable retirement income, inflation, longevity and the assets already available to you.
GreySmiles’ retirement corpus calculation framework looks at this process in more detail.
This matters because an investor who needs ₹60,000 a month from investments after retirement has a different problem from someone who expects a pension of ₹50,000 and needs investments to provide only the remaining ₹10,000.
The size of the investment portfolio cannot be judged without understanding the income requirement it has to meet.
Think of Each Asset as Having a Job
A useful way to think about retirement investing is to stop asking whether an asset is “good” and instead ask what role it performs.
| Asset / Investment | Potential role | Important limitation |
|---|---|---|
| Equity | Long-term growth and inflation protection | Market volatility and potential capital loss |
| Equity Mutual Funds | Diversified access to equity markets | Returns are market-linked; fund selection still matters |
| Debt / Fixed Income | Stability, liquidity and income planning | Inflation and reinvestment risk |
| Gold | Diversification | No regular cash flow from simply holding the asset |
| Real Estate | Potential wealth creation and housing security | Illiquidity, maintenance and concentration risk |
| NPS / Retirement Schemes | Structured retirement accumulation | Rules, access and exit conditions apply |
The important point is that these assets do not have to compete with one another. They can perform different jobs within the same retirement strategy.
Equity: The Growth Engine
For someone with many years before retirement, equity can play an important role because retirement savings may need to grow faster than inflation over several decades.
That does not mean putting all retirement money into shares.
Equity markets can experience substantial declines. Someone who invests aggressively in equity shortly before needing the money may discover that a long-term growth strategy has created a short-term liquidity problem.
The value of equity therefore depends heavily on when the money will be needed and how much volatility the investor can tolerate.
For younger investors, the longer horizon can provide more time to recover from market declines. As retirement approaches, the portfolio needs to be reviewed rather than allowing an old allocation to continue automatically.
Mutual Funds: A Way to Implement the Strategy
Mutual funds are not really a separate answer to the asset-allocation question.
They are one way of gaining exposure to different underlying assets.
An equity mutual fund can provide exposure to shares. A debt mutual fund can provide exposure to fixed-income securities. Hybrid funds combine different asset classes according to their stated strategy.
This is why choosing a mutual fund should come after deciding what role that investment is supposed to play.
GreySmiles’ Mutual Funds for Retirement article explores how different mutual-fund categories can fit into a retirement strategy.
There is also a separate question of how to evaluate and select individual schemes. The GreySmiles framework for selecting mutual funds looks at factors such as investment objective, risk, costs, consistency and portfolio fit.
Fixed Income: The Stabiliser
Fixed-income investments can play an important role in a retirement portfolio because they can provide greater stability than equity.
Depending on the investor’s circumstances, the fixed-income portion may include instruments such as EPF, PPF, fixed deposits, bonds or suitable debt-oriented investments.
But “safe” does not mean “risk-free”.
Fixed deposits and other fixed-income products can face inflation risk and reinvestment risk. A rate that looks attractive today may not remain available when the investment matures.
Debt mutual funds also have different credit and interest-rate risks and should not automatically be treated as equivalent to bank deposits.
The role of fixed income is therefore broader than simply producing interest. It can also help prevent the investor from being forced to sell growth assets during an unfavourable market period.
Gold: Diversification, Not the Core Retirement Plan
Gold can have a role in a diversified portfolio because its price behaviour can differ from that of equities and fixed-income assets.
But gold does not need to become the centre of a retirement strategy.
It does not generate regular cash flow simply because you own it, and its price can also be volatile.
For most retirement investors, the more useful question is whether a modest allocation improves diversification rather than whether gold will outperform another asset over the next few years.
Real Estate: Valuable, But Not Automatically Retirement Income
For Indian households, real estate often represents a significant part of lifetime wealth.
But a valuable property and a retirement-income asset are not necessarily the same thing.
A house can provide security and remove rent from the retirement budget. An investment property may generate rental income. But property can also be illiquid, involve maintenance costs and concentrate a large portion of household wealth in one asset.
This creates an important distinction:
Your net worth can include your home without your home necessarily being available to fund your retirement spending.
If you intend to rely on property later in life, think through how that value would actually become usable income — through rent, downsizing, sale, reverse mortgage or another route.
NPS and Other Retirement-Focused Options
Retirement-focused schemes can form another part of the overall picture.
NPS, for example, is designed specifically around long-term retirement savings and provides exposure to different asset classes within its regulatory framework.
But a retirement plan should not automatically become an NPS-only plan simply because NPS is designed for retirement.
The relevant questions are still the same: how much do you need, when will you need it, what other assets do you have, how much liquidity do you require and how will your retirement income eventually be generated?
The Allocation Matters More Than the Product List
One of the easiest mistakes in retirement investing is accumulating products without understanding the overall portfolio.
You might have an equity mutual fund, an NPS account, EPF, PPF, several fixed deposits, a property and some gold and still have an unbalanced retirement portfolio.
Why?
Because the number of products does not tell you how much exposure you actually have to growth, stability, liquidity or a particular risk.
Asset allocation brings those holdings together.
There is no universal percentage split that every Indian investor should follow. Your appropriate allocation depends on your age, retirement horizon, existing corpus, income, liabilities, other sources of retirement income and ability to tolerate losses.
GreySmiles’ retirement asset-allocation framework explains why a portfolio should be built around these factors rather than a fixed percentage template.
Your Age Is Not the Only Variable
Age is useful, but it is not enough.
Two people aged 58 can have completely different investment requirements.
One may have a substantial pension, a debt-free home and a large retirement corpus. Another may have no pension, a smaller corpus and depend heavily on investments to meet everyday expenses.
Their portfolios should not necessarily look the same.
Similarly, a 35-year-old with unstable income and substantial debt may have a different risk capacity from another 35-year-old with stable income, low liabilities and a large emergency reserve.
Risk capacity and risk tolerance are not identical.
You may be emotionally comfortable with a market fall but financially unable to absorb it. Or you may have the financial capacity to take risk but be unable to stay invested when markets fall.
Keep Short-Term Money Out of the Retirement Growth Portfolio
Not every rupee you invest needs to serve retirement.
Emergency money, money needed for a child’s education, a house purchase or a known near-term expense should not be mixed casually with the money intended for a retirement that may be decades away.
This separation matters because it reduces the chance that a market decline in a long-term investment will force you to sell at precisely the wrong time to meet a short-term need.
What Changes When Retirement Gets Closer?
The investment strategy should evolve as the purpose of the money gets closer.
When retirement is 25 years away, a temporary equity-market decline may be uncomfortable but may not fundamentally alter the plan.
When retirement is two years away, the same decline can have much greater consequences if a large portion of the money is about to be withdrawn.
This does not mean that everyone approaching retirement should eliminate equity.
It means the portfolio needs to be assessed against the actual retirement-income requirement and the sequence in which different assets may need to be used.
Building the corpus is only one part of the job. Eventually, the question becomes how to use that corpus without exhausting it too quickly. GreySmiles’ guide to withdrawing from a retirement corpus explores this transition.
Five Questions to Ask Before Choosing an Investment
- What job will this investment perform?
Is it for growth, stability, liquidity, diversification or income? - When will I need the money?
A 20-year horizon and a two-year horizon require very different thinking. - What happens if the value falls?
Consider both the financial and emotional consequences of a significant decline. - How easily can I access the money?
Retirement portfolios need liquidity as well as long-term growth. - How does this investment fit with everything else I own?
A good investment can still create a poor portfolio if it duplicates risks you already have.
Common Mistakes in Retirement Investing
Chasing the Highest Recent Return
The investment that has performed best recently is not necessarily the investment that best fits your retirement plan.
Putting Everything in “Safe” Assets
Safety from short-term volatility can create a different problem if inflation steadily reduces purchasing power over a long retirement.
Treating Property as Cash
A property can be worth a great deal without being readily available to pay next month’s expenses.
Owning Too Many Products
More funds, deposits and accounts do not automatically create better diversification. Complexity can make the portfolio harder to understand and rebalance.
Ignoring the Withdrawal Phase
A portfolio designed only to accumulate wealth can look very different from one that eventually needs to provide regular retirement income.
Never Reassessing the Portfolio
Your income, family responsibilities, health needs, retirement date and risk capacity can all change. A portfolio that was appropriate five years ago may no longer be appropriate today.
A Practical Way to Build Your Retirement Portfolio
Instead of beginning with a list of products, work through the decisions in this order:
- Estimate your retirement spending.
- Identify dependable retirement income.
- Calculate the investment gap.
- Determine how much capital needs to be accumulated.
- Choose an asset allocation that matches your time horizon and risk capacity.
- Select appropriate products to implement that allocation.
- Review the portfolio as retirement approaches.
- Build a withdrawal strategy before you actually need to depend on the corpus.
This sequence is important.
Products should implement the retirement plan. They should not become the plan.
When the “Smart” Investment Is Actually Doing Less
There is a temptation to keep searching for the next better investment — the fund with a higher return, the property with a better yield, the stock that could multiply or the product offering a slightly higher interest rate.
But retirement investing is a long game.
A portfolio that you understand, can stick with and can adjust as your circumstances change may be more useful than a complicated portfolio built around constantly changing predictions.
The smartest investment decision may sometimes be to stop adding products and start understanding the portfolio you already have.
Final Thoughts
Retirement investing is not a contest to identify the highest-returning asset.
It is the process of putting together a portfolio that can support a future life — through market cycles, inflation, changing expenses and potentially several decades without a salary.
Equity can provide growth. Fixed income can provide stability. Mutual funds can provide diversified implementation. Gold can diversify. Real estate can provide housing or wealth. Retirement schemes such as NPS can form part of the long-term structure.
But none of these should be judged in isolation.
The right retirement portfolio is the one in which every major investment has a clear purpose, the overall risks are understood and the portfolio remains connected to the life it is supposed to fund.
Sources & References
Disclaimer: This article is for educational purposes only and does not constitute personalised investment advice. Investments are subject to market risks. Investment products, taxation, regulations and applicable rules can change. Verify current information and scheme-specific details before investing.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.