Health insurance can become an important part of retirement planning as employer coverage changes after retirement.
By Kartikey Gupta: Kartikey Gupta is a finance professional with 6+ years of experience across capital markets, insurance and financial services.
He is a CMT and CFA Level II qualified professional and writes on retirement planning, investing and financial security.
Retirement can change that.
When your employment ends, the health insurance you have been relying on may also change. Your employer’s policy may stop, there may be an option to move to another form of cover, or you may already have a personal policy that continues independently.
The exact position depends on your policy and insurer. The important thing is to understand what happens before you retire, rather than discovering it after your salary has stopped.
At a Glance
- Employer health insurance may not continue automatically after retirement. Find out exactly when your existing cover ends.
- Migration or portability may be relevant, but the option available depends on your policy, insurer and applicable rules.
- Your spouse and dependants need to be checked separately. Their coverage may also change when your employment ends.
- Personal health insurance changes the transition. If you already have your own policy, it can continue independently of your employment.
- Premiums become a retirement expense. If you have to fund the insurance yourself, that cost belongs in your retirement calculations.
- Insurance is only one part of healthcare planning. You also need to account for healthcare expenses that fall outside the policy.
What Happens to Employer Health Insurance When You Retire?
There is no single answer for every employer-sponsored health insurance policy. Your coverage after retirement depends on the arrangement between your employer, the insurer and the terms applicable to you.
That is why it is worth establishing the facts before your retirement date. Ask your employer or insurer when your existing coverage ends, who is covered, whether there is any option to continue or migrate the coverage, and what happens to your spouse and other dependants.
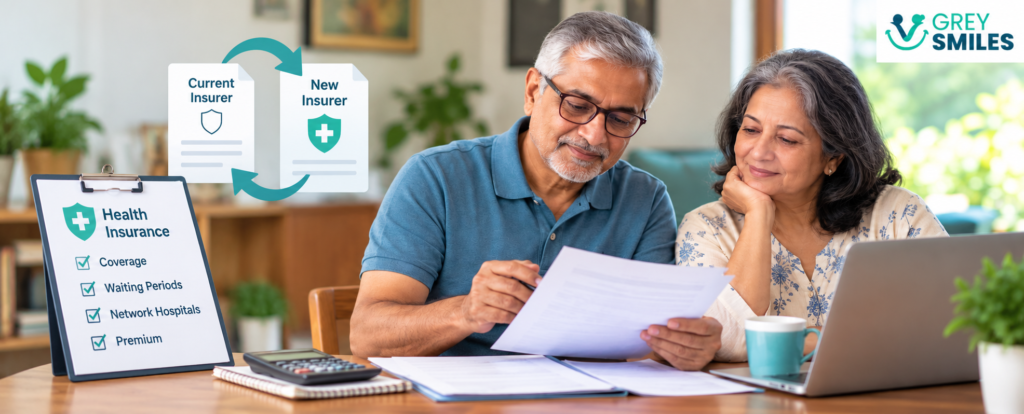
IRDAI recognises both migration and portability mechanisms in health insurance. Its guidance explains that migration can allow credits from an existing policy to be carried to another policy with the same insurer, while portability allows certain credits to move between insurers. The precise option available to you depends on the policy and applicable rules, so check the current terms rather than assuming that every employer policy works in the same way.
IRDAI’s health insurance guidance is a useful starting point when you want to understand the regulatory framework around migration, portability and continuity benefits.
What Should You Check Before You Retire?
The first step is to turn an employment benefit that you may not have had to think about into a clearly understood retirement expense.
| Check | What you need to know |
|---|---|
| End date | When exactly does your employer-sponsored health insurance stop? |
| Family coverage | Who is currently covered, and what happens to each person after retirement? |
| Migration or continuation | Does the insurer or employer arrangement provide an option to continue or migrate the cover? |
| Continuity benefits | What existing policy credits or waiting-period benefits may be carried forward? |
| Personal insurance | Do you already have an individual or family policy that will continue independently? |
| Future premium | What will the insurance cost once you are paying for it yourself? |
| Out-of-pocket costs | What healthcare expenses could still fall outside the insurance policy? |
Do not leave this exercise until the final month of employment. If you discover that your post-retirement arrangement is more expensive or less comprehensive than expected, you want enough time to reconsider your wider retirement plan.
Migration and Portability: What Is the Difference?
When employment-linked health insurance is coming to an end, you may hear terms such as migration and portability. They are not interchangeable.
Migration generally refers to moving from one health insurance policy to another policy with the same insurer, subject to the applicable rules. Portability refers to moving from one insurer to another while carrying certain continuity benefits, again subject to the applicable rules.
The important point is not to assume that either option will automatically be available in exactly the form you expect. Check your policy documents, speak to the insurer and refer to the current IRDAI guidance before acting.
What If You Already Have Your Own Health Insurance?
If you already maintain an individual or family health insurance policy, the transition may be easier because that cover is not dependent on your employment. Even so, retirement is a good point to review whether the policy remains suitable for the years ahead.
Look at the sum insured, co-payments, deductibles, exclusions, waiting periods, room-rent restrictions, renewal terms and the hospitals available to you. Also look at the premium and consider whether it remains affordable as part of your retirement spending.
If the question you are trying to answer is specifically whether your health insurance is enough for retirement, GreySmiles has a separate article devoted to that question. This article is concerned with the transition away from employer-linked cover and what that transition does to the wider retirement plan.
That distinction matters.
What Happens to Your Spouse and Dependants?
If your spouse or other family members are covered under your employer’s health insurance, do not assume that their protection will simply continue after you retire.
Find out who is currently covered, when their cover ends and whether there are continuation, migration or other options available. The household may need to make different arrangements for different family members.
This is particularly important if your spouse does not have independent health insurance. The retirement transition should be treated as a household insurance review, not just an individual one.
Insurance Is Not the Whole Healthcare Plan
Moving from employer cover to personal health insurance does not mean that every healthcare expense will now be covered.
Policy terms can still include exclusions, co-payments, deductibles, limits and other conditions. You may also have regular healthcare expenses that do not depend on hospitalisation or are not reimbursed under your policy.
That is why the transition from employer insurance should be considered alongside a broader healthcare plan. GreySmiles’ guide on planning healthcare costs in retirement looks at the wider relationship between regular healthcare spending, insurance and a healthcare reserve.
What About Rising Healthcare Costs?
Your retirement healthcare plan should not assume that today’s healthcare spending will remain unchanged for the rest of your life.
Insurance premiums can change, healthcare expenses can rise and your own healthcare needs may change over time. The objective is not to predict every future medical bill. It is to make sure that your retirement plan recognises healthcare as an ongoing financial consideration.
A separate healthcare reserve can also provide liquidity for expenses that insurance does not cover. The appropriate amount will depend on your circumstances, existing insurance and the level of financial flexibility you want to maintain.
Bring Healthcare Back Into Your Retirement Numbers
Employer health insurance can make healthcare look cheaper than it actually is from the perspective of your eventual retirement budget because part of the benefit is attached to employment.
Once you retire, you may have to pay the insurance premium yourself. You may also need money for healthcare expenses outside the policy.
That means your retirement calculations should reflect the post-retirement cost rather than simply carrying forward today’s household spending.
The GreySmiles Retirement Corpus Calculator can help you examine the wider retirement corpus question, while healthcare costs can be considered as one component of the spending you expect to fund.
What If Losing Employer Insurance Changes Your Retirement Plan?
Sometimes the result of this exercise is reassuring. You already have suitable personal cover, the premiums fit comfortably within your expected retirement spending and you have sufficient liquidity for expenses outside insurance.
Sometimes it reveals a gap.
You may find that the replacement premium is higher than expected. You may realise that your retirement spending estimate did not include insurance at all. Or you may decide that you want a larger healthcare reserve because you do not want an unexpected medical expense to force a large withdrawal from your long-term investments.
None of those discoveries means the retirement plan has failed. They simply give you information while you still have the ability to change something.
You might choose to work a little longer, save more, revise discretionary spending, increase your expected retirement income or reconsider how much liquidity you want to maintain.
Healthcare insurance therefore belongs within the broader question of retirement readiness. If losing employer cover materially changes whether the retirement numbers work, the issue is bigger than the insurance policy itself.
The GreySmiles Retirement Readiness Test provides a broader way to assess whether the pieces of your retirement plan are coming together, rather than looking at the corpus in isolation.
GreySmiles Take
Do not let your employer health insurance disappear from the retirement plan unnoticed.
Employer-sponsored cover can make healthcare feel simpler while you are working because the policy sits alongside your employment. Once the salary stops, the responsibility for arranging and funding that protection becomes much more visible.
Know when your employer cover ends. Understand what happens to your spouse and dependants. Review your personal insurance, account for premiums and healthcare expenses outside the policy, and then bring those numbers back into the wider retirement plan.
A Pre-Retirement Health Insurance Checklist
Before your last working day, make sure you can answer these questions from your actual policy documents rather than from memory:
- When exactly does my employer health insurance end?
- Who is currently covered under the policy?
- What happens to my spouse and dependants after I leave employment?
- Is migration, continuation or another transition option available?
- What continuity benefits or waiting-period credits may apply?
- What personal health insurance do I already have?
- What are the major exclusions, co-payments, deductibles and limits?
- What will the premiums cost after retirement?
- How much do I currently spend on healthcare outside insurance?
- Have I considered how those costs could change over time?
- How much accessible money do I want available for healthcare expenses insurance does not cover?
- Have these costs been included in my retirement spending and corpus assumptions?
What If Retirement Is Only a Few Years Away?
Do not wait until the final few months.
If retirement is within the next several years, start by documenting your current employer cover and your personal insurance. Find out exactly what changes when employment ends and estimate what the replacement arrangement will cost.
Then test those costs against your retirement spending and corpus assumptions. If the numbers are uncomfortable, you have time to make a deliberate change rather than being forced into one after retirement.
Frequently Asked Questions
Does employer health insurance automatically continue after retirement?
Not necessarily. The outcome depends on the employer’s arrangement and the applicable policy terms. Find out before retirement when your cover ends and whether any migration or continuation option is available.
Can I move from employer health insurance to an individual policy?
Health insurance regulations provide for migration and portability in specified circumstances, including provisions relating to group health insurance. However, the exact route available to you depends on your policy and insurer. Check the current terms and applicable IRDAI guidance before making a decision.
What happens to my spouse if my spouse is covered under my employer policy?
Check the policy terms before retirement. Your spouse’s cover may change when your employment ends, and the household should understand what replacement or continuation options are available.
Should I buy personal health insurance before retirement?
There is no universal answer, but if your employer cover is expected to end, it is sensible to understand your post-retirement options well before your last working day. This gives you time to evaluate the coverage and affordability rather than making a rushed decision after retirement.
Is health insurance enough to cover healthcare costs in retirement?
No policy should be assumed to cover every healthcare expense. Policy terms, exclusions, limits, co-payments and deductibles can all affect what you eventually pay yourself. That is why insurance and a broader healthcare plan need to be considered together.
Should health insurance premiums be included in retirement expenses?
Yes, if you expect to pay them yourself after retirement. Premiums are part of the household’s ongoing retirement spending and should be reflected in your retirement assumptions.
Should I keep a separate healthcare reserve if I have insurance?
A separate reserve can provide useful financial flexibility for healthcare expenses that insurance does not cover. The appropriate amount depends on your insurance, age, health needs, family circumstances and overall financial position.
The Bottom Line
Retirement can change more than your income. It can change how your household pays for healthcare and who is responsible for arranging that protection.
The sensible approach is to understand what happens to your employer health insurance before retirement, review your personal and family coverage, estimate the premiums and out-of-pocket costs you may face, and bring those numbers into the wider retirement plan.
You do not need to predict every medical expense you will ever have. You do need to make sure that losing an employment benefit does not become an unexpected financial problem at exactly the point when your salary stops.
Sources & References
- Insurance Regulatory and Development Authority of India (IRDAI) — Health Insurance guidance, including information on migration and portability.
- IRDAI — Health Insurance: Policy Holder, for policyholder guidance on renewal and portability.
- GreySmiles — How to Plan for Healthcare Costs in Retirement, for healthcare spending and planning.
- GreySmiles — Is My Health Insurance Enough for Retirement?, for assessing the adequacy of health insurance itself.
- GreySmiles — How Much Should You Keep Aside for Healthcare in Retirement?, for healthcare-reserve planning.
- GreySmiles — How to Calculate Your Retirement Corpus in India, for the relationship between healthcare spending and the wider retirement corpus.
Disclaimer: This article is for general educational purposes only and is not financial, insurance or medical advice. Health insurance policies, terms, premiums and regulations can change. Always check your current policy documents and applicable official information before making insurance or retirement-planning decisions.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.