At a Glance
- A healthcare reserve is the money you keep accessible for medical costs that insurance may not fully cover.
- There is no universal amount. Your reserve should reflect your healthcare needs, insurance, family situation and location.
- Your healthcare reserve is different from your general emergency fund and retirement corpus.
- Liquidity matters because medical expenses may need to be paid when markets or long-term investments are not convenient to access.
- Review the reserve regularly as your health, insurance and retirement circumstances change.
Having health insurance does not mean that every healthcare expense in retirement will be paid by the insurer. You may still have to pay for medicines, consultations, diagnostic tests, deductibles, co-payments, non-payable expenses and healthcare services that fall outside the policy.
That is why it can be useful to think about a separate healthcare reserve: money that is readily accessible when you need to pay for healthcare without disturbing the money set aside for your regular retirement expenses.
Why Do You Need a Healthcare Reserve?
Health insurance is an important layer of financial protection, particularly against large hospitalisation expenses. It does not necessarily cover every healthcare cost you may face during retirement.
Some expenses are relatively small but recurring. Medicines, consultations, tests, physiotherapy, dental care, vision care and other out-of-pocket costs can continue for years. Other expenses may be larger and arrive unexpectedly.
The purpose of a healthcare reserve is therefore not to replace insurance. It is to provide financial flexibility for the portion of healthcare spending that insurance does not fully absorb.
Healthcare Reserve vs Emergency Fund
A general emergency fund and a healthcare reserve may both be accessible savings, but they serve different purposes.
| Fund | Purpose |
|---|---|
| Emergency fund | Financial disruptions such as major home repairs, temporary income loss or unexpected family expenses. |
| Healthcare reserve | Medical and healthcare expenses that you need to pay yourself or before insurance reimbursement. |
Keeping the two purposes separate can make your financial plan easier to understand. If your general emergency savings are regularly being used for healthcare expenses, your overall financial protection may be lower than it appears.
How Much Should You Keep Aside?
There is no single amount that works for every retiree. A couple with comprehensive insurance and relatively low medical spending may have a very different requirement from someone managing regular medicines, chronic conditions or limited insurance coverage.
A more useful approach is to build the number from your own circumstances. Start with what you actually spend on healthcare today, identify the expenses you expect to continue, review what your insurance may not cover and then add a buffer for costs that are difficult to predict.
Your location can also matter. Healthcare costs can vary between cities, hospitals and providers, while the availability of family support may affect how much accessible money you want to keep available.
GREYSMILES CALCULATOR
Understand Your Future Healthcare Costs
Before deciding how much to keep aside, it can help to understand how your current healthcare spending could change over time. Use the GreySmiles Health Inflation Planner as a starting point for that exercise.
Use the Health Inflation Planner →
Illustrative planning tool only. Actual healthcare costs vary by individual circumstances, treatment, location, insurance and future medical needs.
What Should the Healthcare Reserve Pay For?
The reserve should be designed around the expenses that you may have to fund yourself or pay before an insurance claim is settled. The exact list will differ from one household to another.
- Regular medicines and consultations
- Diagnostic tests and outpatient treatment
- Deductibles and co-payments
- Non-payable hospital expenses and consumables
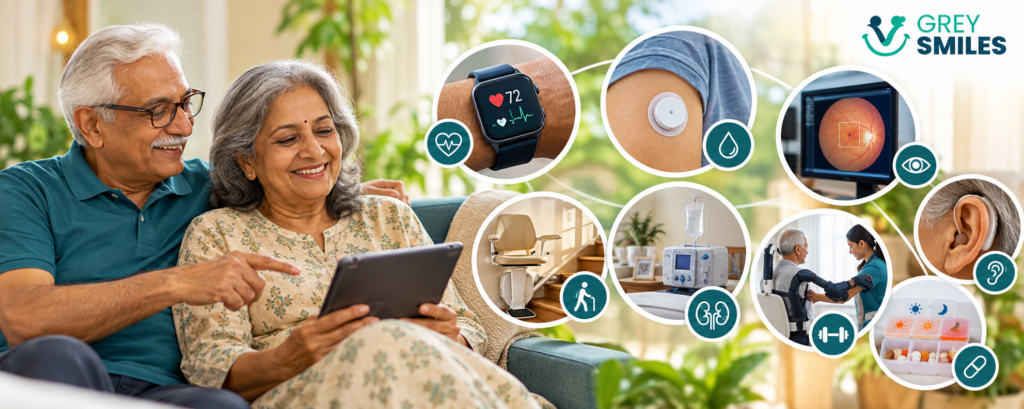
- Physiotherapy, rehabilitation or home nursing
- Medical equipment or mobility aids
- Expenses that arise during insurance waiting periods
You do not need to assume that every one of these expenses will occur. The point is to identify the healthcare costs that are realistic for your household and decide how much accessible money you would want available for them.
What Your Health Insurance Does Not Cover Matters
Your healthcare reserve should be considered alongside your insurance policy, not independently of it. The larger the potential gap between your healthcare needs and what your policy covers, the more important accessible savings may become.
Look at the policy terms rather than focusing only on the headline sum insured. Co-payments, deductibles, exclusions, waiting periods and limits on particular expenses can all affect the amount you eventually pay yourself.
If your question is broader than the reserve itself, read Is My Health Insurance Enough for Retirement?. That article focuses specifically on assessing insurance adequacy.
If you are approaching retirement with employer-provided health insurance, there is a separate issue to consider: what happens to your health insurance when you retire. Your post-retirement premium and coverage can also affect the amount you need to keep available.
Where Should You Keep the Healthcare Reserve?
A healthcare reserve has a different job from your long-term retirement portfolio. Its first priorities are accessibility and stability rather than maximising returns.
The money should be available when a healthcare expense arises. Depending on your circumstances and tax position, this could mean using readily accessible savings and other suitable liquid, lower-volatility instruments rather than relying on long-term investments that may need to be sold at an inconvenient time.
The money you may need for a medical expense should not depend on market conditions being favourable on the day you need it.
GreySmiles Take
A healthcare reserve is not about predicting your medical bills. It is about creating enough financial breathing room so that an unexpected healthcare expense does not force you to disturb money meant for your everyday retirement.
Insurance protects against part of the risk. The healthcare reserve gives you flexibility around the rest.
Should the Reserve Be Separate From Your Retirement Corpus?
The healthcare reserve can form part of your overall retirement financial plan, but it is useful to identify it separately because it has a different purpose and liquidity requirement.
Your broader retirement corpus is expected to support living expenses over many years. Money earmarked for immediate or unexpected healthcare needs may need to remain much more accessible.
If you are still calculating your overall retirement requirement, healthcare should also be reflected in that wider exercise. See How to Calculate Your Retirement Corpus in India for the broader retirement-corpus question.
Review the Reserve as You Grow Older
A healthcare reserve should not be treated as a number that you calculate once and never revisit. Your healthcare needs can change significantly during retirement, and your insurance arrangements can change as well.
Review the reserve at least annually and whenever there is a significant change in your health, insurance coverage, family circumstances or retirement income.
A large medical expense should also trigger a review. If you use a substantial portion of the reserve, decide how you will rebuild it rather than allowing the balance to remain permanently lower.
What Changes as You Get Older?
Healthcare spending may become more varied as retirement progresses. The requirement may shift from occasional consultations and medicines towards a combination of regular treatment, specialist consultations, rehabilitation, mobility support, home care or assistance with everyday activities.
This does not mean that everyone will experience higher healthcare spending in the same way. It simply means that a healthcare reserve should remain flexible enough to reflect changing circumstances.
Government healthcare schemes may also become relevant depending on your age and eligibility. These should be considered as one part of your overall protection rather than assumed to replace private insurance or personal savings.
A Simple Annual Healthcare Reserve Check
Once a year, take a fresh look at your healthcare position. Five questions can make the review practical:
- How much did we actually spend on healthcare during the past year?
- How much did insurance pay, and how much did we pay ourselves?
- Have our insurance policies or terms changed?
- Are there new health conditions, medicines or regular treatments to consider?
- If a large medical expense arose tomorrow, how much could we access without selling long-term investments?
The answers give you a more meaningful basis for reviewing your healthcare reserve than simply applying a generic percentage to your retirement corpus.
Healthcare Reserve Checklist
- Know your actual annual healthcare spending.
- Review the important gaps in your health insurance.
- Separate healthcare savings from your general emergency fund.
- Keep the reserve reasonably accessible.
- Consider regular as well as unexpected healthcare expenses.
- Review the reserve at least once a year.
- Have a plan for rebuilding the reserve after a major medical expense.
The Bottom Line
A healthcare reserve is one more layer of protection in a retirement plan. It does not need to be based on a universal number, and it does not need to predict every medical expense you might face.
Start with your own healthcare spending, understand what your insurance may leave you paying, consider your circumstances and keep an appropriate amount accessible. The objective is simple: when healthcare costs arise, they should not automatically force you to disturb the money you depend on for the rest of your retirement.
For the broader question of planning healthcare costs in retirement, including healthcare spending, insurance and healthcare inflation, read How to Plan for Healthcare Costs in Retirement.
FAQs
How much money should I keep aside for healthcare after retirement?
There is no universal amount. Your healthcare reserve should reflect your current healthcare spending, expected needs, insurance coverage, family circumstances and location. The objective is to create enough accessible money to deal with healthcare expenses without disrupting your regular retirement finances.
Is a healthcare reserve the same as an emergency fund?
No. An emergency fund is intended for a wider range of unexpected financial needs, while a healthcare reserve is specifically intended for medical and healthcare expenses that you may have to fund yourself.
Do I need a healthcare reserve if I already have health insurance?
Insurance can cover a substantial part of eligible medical expenses, but policy terms determine what is actually paid. A reserve can provide flexibility for deductibles, co-payments, non-covered expenses, medicines, consultations and other costs that fall outside or alongside an insurance claim.
Where should I keep my healthcare reserve?
The priority should generally be accessibility and stability rather than maximum returns. The appropriate arrangement depends on your circumstances, liquidity needs and tax position.
Should I increase my healthcare reserve as I get older?
Your healthcare needs and insurance arrangements can change over time, so the reserve should be reviewed regularly. A change in health, treatment, insurance or retirement income may justify changing the amount you keep accessible.
Sources & References
- Insurance Regulatory and Development Authority of India (IRDAI) – Health Insurance Guidance
- IRDAI – Health Insurance Policyholder Information
Disclaimer: This article is for general educational purposes only and is not financial, insurance, medical or tax advice. Insurance products, government schemes and regulations can change. Check the latest policy terms and official regulatory guidance before making decisions about your retirement finances.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.