
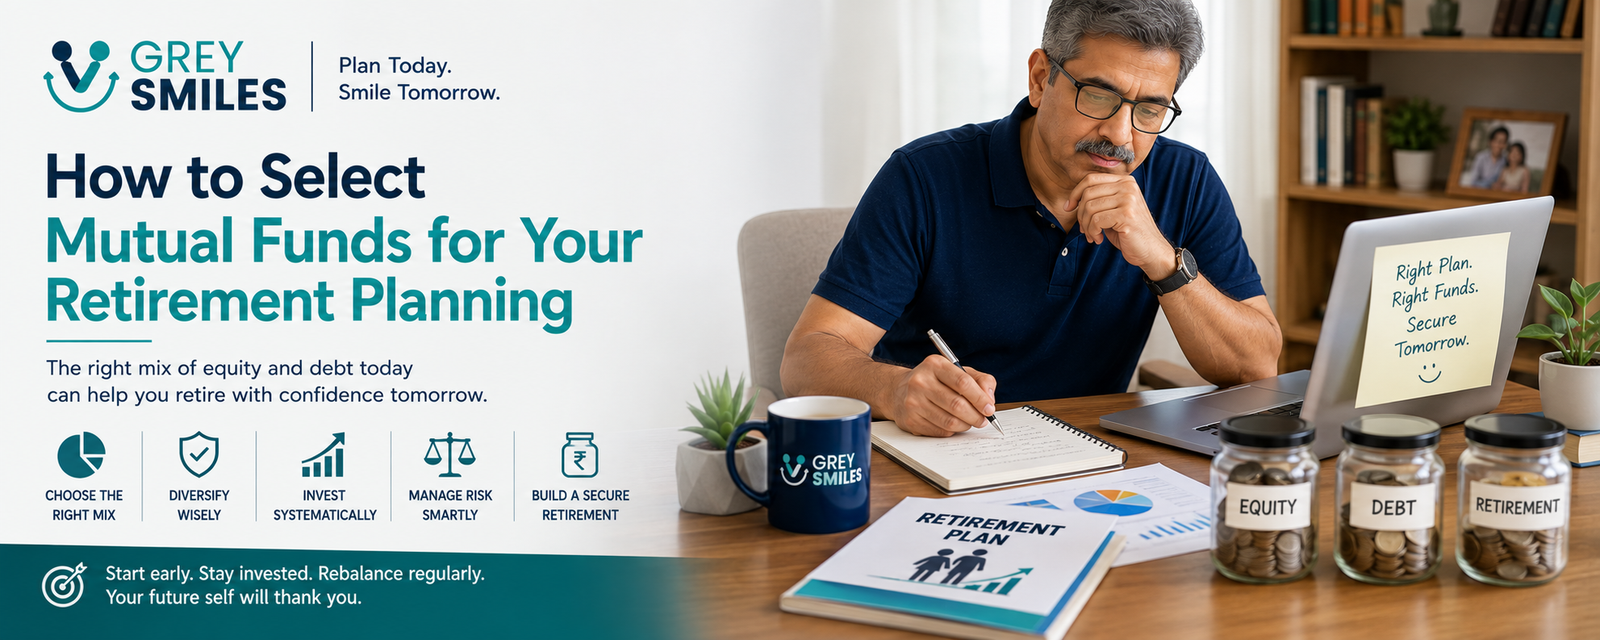
Choosing mutual funds for retirement is not simply about finding the fund that delivered the highest return over the last three or five years.
Retirement investing has a different job. The money may need to grow for decades, but eventually it also has to support spending, withstand market falls and be available when needed. That means the right mutual fund is not necessarily the one with the highest recent return. It is the one that fits the job your money needs to perform, your time horizon and your ability to live with the risk involved.
At a Glance
- Don’t choose retirement funds on recent returns alone. Start with the role the investment needs to play in your retirement plan.
- Time horizon matters. Money needed decades from now can usually take different risks from money you may need soon after retirement.
- Look at the whole portfolio. EPF, PPF, NPS, deposits, property and other assets affect how much risk your mutual funds need to take.
- Costs and diversification matter, but neither should be considered in isolation.
- The portfolio should evolve as retirement approaches. The job gradually shifts from accumulation alone to balancing growth, liquidity and future withdrawals.
Start With the Job the Investment Has to Do
Before comparing mutual funds, understand where the investment fits into your retirement plan. If retirement is 20 or 25 years away, the priority may be long-term growth. If retirement is only a few years away, protecting money that will soon be needed becomes more important.
This is why two people can reasonably choose different mutual funds for retirement even if they have similar incomes. Their existing assets, pensions, time horizons and dependence on the investment portfolio may be very different.
Before selecting a fund, ask when the money will be needed, how much of your retirement will depend on it, whether you can tolerate a substantial temporary fall in value and whether withdrawals are likely to begin soon after retirement. Those questions tell you more than a list of last year’s top-performing funds.
Equity, Debt or Hybrid: What Role Does Each Play?
Mutual funds are not one investment category. Different types of funds can perform very different jobs within a retirement portfolio.
| Fund Type | Potential Role in Retirement Planning | Main Consideration |
|---|---|---|
| Equity funds | Long-term growth | Higher market volatility |
| Debt funds | Relative stability and diversification | Interest-rate and credit risks still exist |
| Hybrid funds | Combination of growth and stability | The underlying asset mix matters |
| Index funds | Low-cost market exposure | Market-linked and not protected from falls |
The appropriate mix depends on the rest of your retirement portfolio. Someone who already has substantial fixed-income assets through EPF, PPF or other investments may look at an equity fund differently from someone whose savings are already heavily exposed to market risk.
Don’t Choose a Fund Only Because It Has Performed Well
Past performance tells you what happened; it does not tell you which fund will perform best next. A fund that has recently outperformed may have benefited from a particular market environment, sector exposure or investment style.
Look instead at what the fund invests in, the risk it has taken, its investment approach, costs and how it compares with an appropriate benchmark. Changes in fund management or investment strategy can matter too.
For retirement money, consistency of purpose can matter more than repeatedly switching to whichever fund currently sits at the top of a performance table.
Risk Matters More as Retirement Gets Closer
A market fall at 35 and a market fall at 59 are not necessarily the same financial event. At 35, there may be decades of earnings, fresh investments and recovery time ahead. Close to retirement, the same fall may occur just as the portfolio is about to start funding household expenses.
This does not mean that everyone should abandon equity as retirement approaches. A retirement itself may last 20 or 30 years, so some money may still have a long investment horizon. What changes is the need to distinguish between money required relatively soon and money that can remain invested for later years.
How Much Should Be in Equity Mutual Funds?
There is no equity percentage that works for every retirement investor. Age can provide context, but it is not enough to determine an asset allocation.
Someone with a substantial pension and significant fixed-income assets may be able to take a different level of investment risk from someone whose retirement spending will depend almost entirely on accumulated investments. Existing EPF, PPF, NPS and deposits, expected spending, healthcare reserves, other income and your reaction to market losses all matter.
The useful question is not “How much equity should a 50-year-old own?” but whether the overall portfolio has an appropriate balance between growth, stability and liquidity for that particular household.
An SIP Is a Method, Not a Fund-Selection Strategy
A systematic investment plan can make regular retirement investing easier, especially while you are earning a monthly salary. It automates the act of investing, but it does not decide where the money should be invested.
You still need to choose the type of fund, understand why you own it, decide how much risk is appropriate and see how it fits with the rest of your assets. An SIP is simply the mechanism through which money enters the investment.
Costs Matter, but Don’t Make Cost the Only Criterion
Expense ratios reduce the amount that remains invested, and even relatively small differences can matter over a long retirement-investment period. Costs therefore deserve attention.
But the lowest-cost fund is not automatically the right fund. Its investment strategy, risk, diversification and suitability still matter. Cost should help you compare appropriate choices rather than determine the choice by itself.
Direct or Regular Plan?
Direct and regular plans of the same mutual fund scheme differ in their cost structure. A direct plan does not include distributor commission in the same way as a regular plan, which generally results in a lower expense ratio.
That does not make the decision purely about price. Someone comfortable selecting, monitoring and managing investments independently may view the choice differently from someone who values ongoing intermediary support. What matters is understanding what you are paying for and whether that support is useful to you.
Look at Your Entire Retirement Portfolio
Mutual funds may be only one part of your retirement assets. EPF, PPF, NPS, deposits, bonds, property and other investments can substantially change the risk profile of the household.
Looking at each investment separately can therefore produce a misleading picture. Before adding another mutual fund, look at how much of the total retirement portfolio is already in equity, fixed income, property and cash or near-cash assets.
The exercise becomes much more meaningful once you know approximately how large that retirement pool needs to be. GreySmiles’ retirement corpus guide explains the factors behind that number and how spending, inflation and retirement duration affect it.
GREYSMILES CALCULATOR
Retirement Corpus Calculator
Before deciding how retirement money should be invested, it helps to know what you are trying to build. The GreySmiles Retirement Corpus Calculator can give you an indicative estimate based on your current spending, retirement age and planning assumptions.
Estimate Your Retirement Corpus
Illustrative planning tool. Your actual retirement requirement will depend on your circumstances and the assumptions used.
How Many Mutual Funds Do You Need?
Owning more funds does not automatically create better diversification. Two or three equity funds can hold many of the same companies, leaving you with a more complicated portfolio without meaningfully changing its underlying exposure.
Each fund should have a reason for being in the portfolio. If you cannot explain what a fund adds that the existing investments do not already provide, it is worth asking whether the additional complexity is necessary.
When Should You Review a Retirement Mutual Fund?
A retirement portfolio does not need to be redesigned every time markets move. Frequent switching can make a long-term investment plan harder to follow and may encourage decisions based on recent performance.
A review becomes more useful when something meaningful changes: your retirement date moves, your income or responsibilities change substantially, the fund’s strategy changes, or your overall asset allocation has moved significantly away from where you intended it to be.
In many cases, rebalancing the portfolio back towards its intended allocation is a more disciplined response than searching for a new top-performing fund.
What Changes as Retirement Approaches?
As retirement gets closer, part of the investment discussion shifts from accumulation to access. Money that may be required for the first few years of retirement has a different job from money intended for much later.
This is where fund selection begins to connect with retirement cash-flow planning. Some assets may continue to seek longer-term growth while other portions of the portfolio are positioned for greater liquidity and stability.
GreySmiles’ article on how to withdraw from a retirement corpus looks at what happens when accumulated savings begin funding actual retirement spending. For retirees who want greater visibility over when portions of their money become available, laddering for retirement offers another way to think about the timing of future cash requirements.
Retirement Income Changes the Investment Decision
A person who expects a pension covering most essential expenses may not need the investment portfolio to produce the same cash flow as someone who will depend almost entirely on savings.
This is why mutual fund selection should eventually connect to the wider retirement-income plan. The portfolio has to support the gap between what the household spends and the income it can reasonably count on.
GreySmiles’ guide to generating income after retirement looks at how pensions, investments and withdrawals can work together rather than expecting one investment product to provide the entire solution.
Five Mistakes Worth Avoiding
Choosing funds solely on recent returns. A strong recent performance does not automatically make a fund suitable for a 15- or 20-year retirement objective.
Holding too many funds. More schemes do not necessarily mean more diversification, particularly when their portfolios overlap.
Ignoring the rest of your assets. Mutual funds should be assessed alongside EPF, NPS, PPF, deposits, property and other retirement investments.
Taking risk simply because retirement is far away. A longer horizon can provide more recovery time, but it does not make every level of risk appropriate.
Changing investments whenever markets fall. Volatility is part of market-linked investing. A market decline by itself does not necessarily mean the reason for owning a fund has changed.
There May Never Be One “Best” Retirement Fund
Funds change, markets change and your own circumstances change. More importantly, the job your money needs to perform changes as retirement gets closer.
A fund that makes sense while you are building the corpus does not automatically have to remain in the same role when you begin drawing from it. What matters is whether each investment still fits the time horizon, risk and purpose for which you hold it.
GreySmiles Take
The search for the “best” mutual fund can distract from the more important retirement decision. Start with the retirement plan, then give each investment a job within it. A fund should earn its place because it adds the growth, stability or diversification the portfolio needs — not because it happens to be leading a performance table today.
Frequently Asked Questions
Which mutual fund is best for retirement?
There is no single mutual fund that is best for every retirement investor. The appropriate choice depends on time horizon, risk tolerance, existing assets, expected retirement income and the role the fund needs to play in the overall portfolio.
Are equity mutual funds suitable for retirement planning?
They can be suitable for money with a sufficiently long investment horizon and for investors able to tolerate market volatility. Their appropriate role depends on the rest of the retirement portfolio and when the money is likely to be needed.
Should I stop investing in equity mutual funds when I retire?
Not automatically. Retirement can last several decades, so some money may still have a long horizon. The appropriate allocation depends on spending needs, other income, liquidity requirements, risk tolerance and the overall portfolio.
How often should I change my mutual funds?
A fund should not normally be changed simply because another fund has recently performed better. A review is more useful when your circumstances, asset allocation or the investment itself has changed materially.
Should retirement mutual funds be selected before calculating the corpus?
It is useful to first understand your retirement objective, expected spending and approximate corpus requirement. That gives the investment portfolio a clearer purpose and helps determine how much growth, stability and liquidity may be required.
Further Reading
- How to Calculate Your Retirement Corpus
- Generating Income After Retirement in India
- How to Withdraw From a Retirement Corpus
- Laddering for Retirement
Sources & References
- Securities and Exchange Board of India (SEBI) — investor education material on mutual funds, investment risk and investor protection.
- Association of Mutual Funds in India (AMFI) — investor education material on mutual funds, SIPs, direct and regular plans and scheme information.
Disclaimer: This article is for educational purposes only and does not constitute investment advice or a recommendation of any mutual fund or scheme. Mutual fund investments are subject to market risks. Investment choices should reflect your individual circumstances, time horizon, risk tolerance, liquidity requirements and other assets.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.