Balancing today’s responsibilities with tomorrow’s retirement takes early planning.
At a Glance
- Retirement gets postponed because today’s responsibilities feel more urgent than tomorrow’s needs.
- A higher salary does not automatically mean greater financial security.
- Waiting for a perfect time to start can become a habit that lasts for years.
- You do not need to solve your entire retirement plan today. You need to take the first step.
Why Retirement Keeps Losing to Everything Else
Most financial goals come with a visible deadline. School fees have to be paid. A home loan has a monthly instalment. An emergency fund protects you against unexpected expenses. Even a holiday has a date attached to it.
Retirement is different. It may be 15, 20 or 30 years away. There is no monthly bill reminding you to prepare for the day your salary stops. The consequences of postponing it are difficult to see in the present.
That makes it easy to believe that one more year will not matter much.
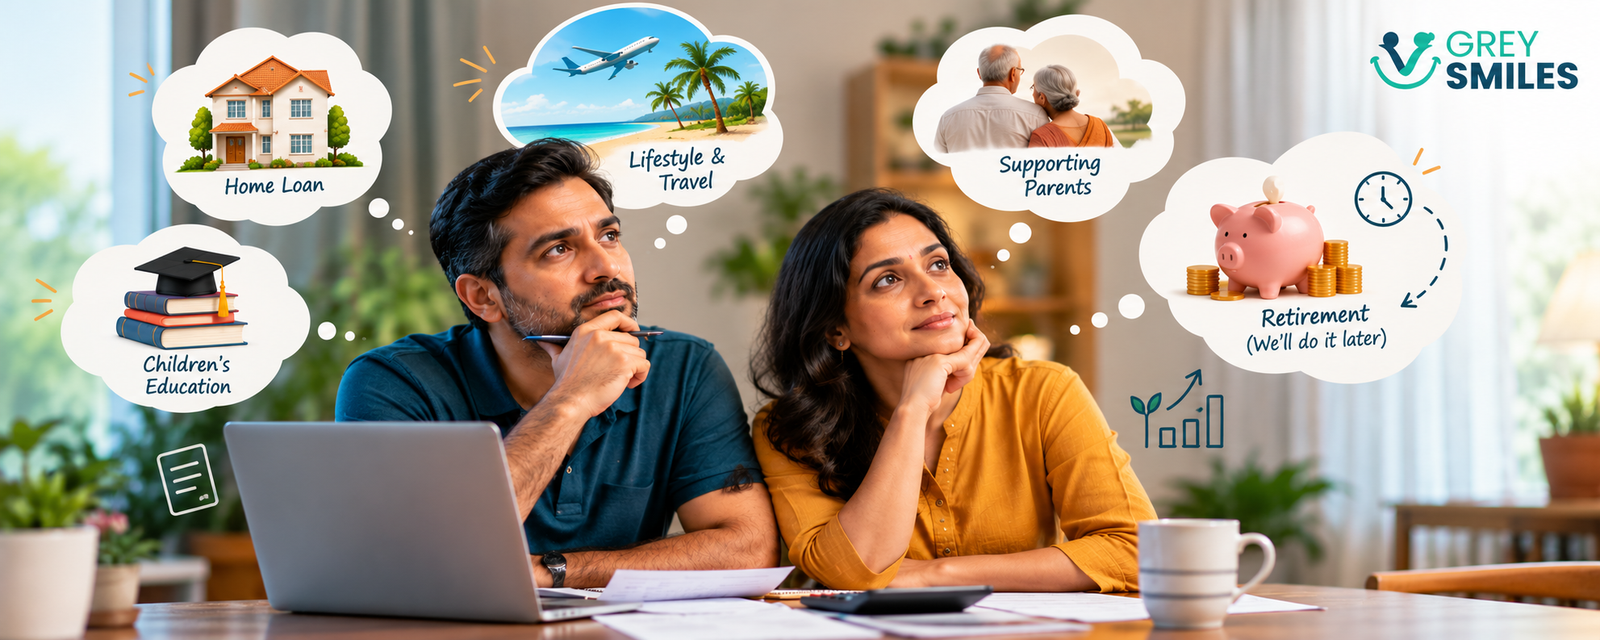
There is also a more personal reason. In your 30s and 40s, you are often building the life you once hoped to have. You may be buying a home, raising children, progressing in your career or taking better care of your parents. These are not frivolous expenses. They are important parts of life.
Retirement planning can therefore feel like a competing demand rather than something that supports the life you are building.
The challenge is to make room for both: the responsibilities you have today and the financial independence you may want tomorrow.
Five Habits That Keep Us Postponing Retirement
1. Waiting for Life to Become Less Expensive
You may be waiting for your salary to increase, your home loan to reduce or your children’s education expenses to settle down. Once those things happen, you expect to have more room to save.
Sometimes that works. Often, one responsibility gives way to another. A loan ends just as higher education expenses begin. A salary increase brings a bigger home, more travel or other lifestyle upgrades. Supporting your children may overlap with helping your parents.
There may never be a period when every other financial goal is fully taken care of.
Instead of waiting for that ideal moment, consider whether you can start with a manageable contribution and review it as your circumstances change. The objective is to give retirement a place in your financial life, even when the amount has to remain modest for now.
2. Assuming a Higher Salary Will Solve Everything
Think about how much your income may have grown since your first job. You may be earning several times what you did in your 20s. Your lifestyle may have improved, too.
That progress is worth appreciating. The difficulty is that spending often grows alongside income. A more comfortable home, better schooling, a newer car, holidays and everyday conveniences can absorb much of each salary increase.
You may be earning more than ever without feeling much more financially secure.
When your income rises, it is worth asking whether your long-term savings are rising as well. You do not have to direct every increment towards retirement. Even allocating a portion of each increase can help prevent your future savings from being left behind by your present lifestyle.
3. Assuming Existing Investments Are Enough
You may already have EPF, PPF, mutual funds, fixed deposits, property or other investments. It is reassuring to see these assets accumulate, and they may form an important part of your retirement preparation.
However, having investments is not the same as knowing whether you are on track.
Some savings may be intended for your children’s education. Your home may provide security without giving you readily available income. Other investments may be needed for emergencies or different financial goals.
Instead of looking only at the total value of your assets, ask how much is intended for retirement and whether it is likely to support the life you want later.
If you are ready to examine the bigger picture, the GreySmiles retirement planning guide explains how savings, investments, future expenses and retirement income fit together.
4. Feeling Overwhelmed by the Numbers
Retirement planning can appear complicated before you even begin. You hear about inflation, healthcare expenses, investment returns, life expectancy and the size of the retirement corpus you may need.
The numbers can feel so large that it becomes tempting not to calculate anything at all.
Yet avoiding the calculation does not make the challenge smaller. It simply leaves you without a starting point.
You do not need a perfect forecast of your life 25 years from now. Begin with a broad estimate of your future expenses, your existing retirement savings and the contributions you are making. The first calculation is there to help you understand the direction, not predict the future with certainty.
When you are ready, use the GreySmiles retirement corpus calculation guide to explore how much you may need and how different assumptions affect the estimate.
5. Thinking Retirement Belongs to Your Older Self
In your 30s, retirement can feel too distant to worry about. In your 40s, you may still have years of professional growth ahead of you. Work is part of your identity, your routine and your income. It can be difficult to picture a life in which those things change.
Try thinking about retirement differently. It does not have to mean choosing a date when you will stop working forever. It can mean building the financial ability to make choices about work later in life.
You might continue working, consult, start something new or stop full-time employment. A stronger financial foundation gives you more room to make that decision on your own terms.
What Postponement Can Cost You
Delaying retirement planning does not automatically lead to a poor retirement. Your income may rise, investments may grow and your circumstances may work out favourably.
The risk is that you leave yourself with fewer ways to respond if they do not.
Starting earlier generally gives you more time to build savings, increase contributions gradually and adjust your plans as life changes. If your first estimate reveals a shortfall, you have more time to consider your options.
Starting later may mean having to save more each month, reconsider your expected retirement age or adjust your future spending. These options may still be available, but they can require more substantial changes.
The real cost of postponement is the possibility of losing flexibility. The aim is not to frighten yourself into saving. It is to give your future self more choices.
If you want to understand how retirement priorities evolve over your working life, read the six stages of retirement planning. It explores how financial priorities change as you move from building wealth to preparing for retirement and managing income afterwards.
A Small First Step Is Better Than Another Year of Waiting
You do not need to solve retirement in a single weekend. You do not have to decide exactly when you will stop working, choose every investment or know the precise amount you will need decades from now.
Start by setting aside half an hour to answer three questions:
- What do I have today? Identify the savings and investments you intend to use for retirement.
- What kind of future am I preparing for? Think about when you might want work to become optional and what your lifestyle could look like.
- What is my next step? Review your current contributions, check when you last assessed your retirement position and decide what deserves attention first.
You may find that you have made more progress than you realised. You may discover a gap that needs attention. Either way, you will have replaced an assumption with a starting point.
If you want a structured way to assess your position, take the GreySmiles Retirement Readiness Test. It can help you identify areas that may need more attention.
Frequently Asked Questions
Is your 30s too early to start retirement planning?
No. Your 30s can be a useful time to establish retirement-saving habits while you still have many working years ahead. You do not need to begin with a large amount. Start with what your circumstances allow and review it as your income and responsibilities change.
Can you plan for retirement while paying a home loan?
Yes, although the balance will depend on your income, loan commitments, emergency savings and other responsibilities. Retirement planning does not necessarily mean prioritising investments over every other goal. It means understanding the trade-offs and deciding whether a manageable contribution can fit into your overall financial plan.
What if you are in your 40s and have not started planning?
You can still begin. Focus on understanding your current savings, estimating your retirement needs and identifying the changes available to you. Avoid spending more time worrying about the years that have passed. A realistic plan today is more useful than another year of postponement.
GreySmiles Take
In your 30s and 40s, retirement can feel like the one financial goal that can always wait. There is always another bill to pay, another family responsibility to manage or another milestone to reach.
Those priorities are real. Preparing for retirement does not mean putting your present life on hold.
It means recognising that your future self will have financial needs too, and that the choices you make during your working years can influence how much freedom you have later.
You do not need a perfect plan to begin. You need to stop leaving retirement to whatever happens to be left over.
Continue Your Retirement-Planning Journey
If this article has prompted you to think more seriously about retirement, choose the next step that best fits where you are today:
- Retirement Planning in Your 30s: 10 Principles — practical habits for building retirement savings as your income and responsibilities change.
- Retirement Planning in India: A Complete Guide — a broader guide to preparing financially for life after work.
- Retirement Corpus Calculation — explore the amount you may need to fund your future expenses.
GreySmiles provides general information and educational tools, not personalised financial, investment, tax, legal or medical advice. Calculator results are estimates based on assumptions and are not guarantees of future outcomes. Consider qualified professional advice before making important financial decisions.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.