
Why the Indian Context Changes the Rules
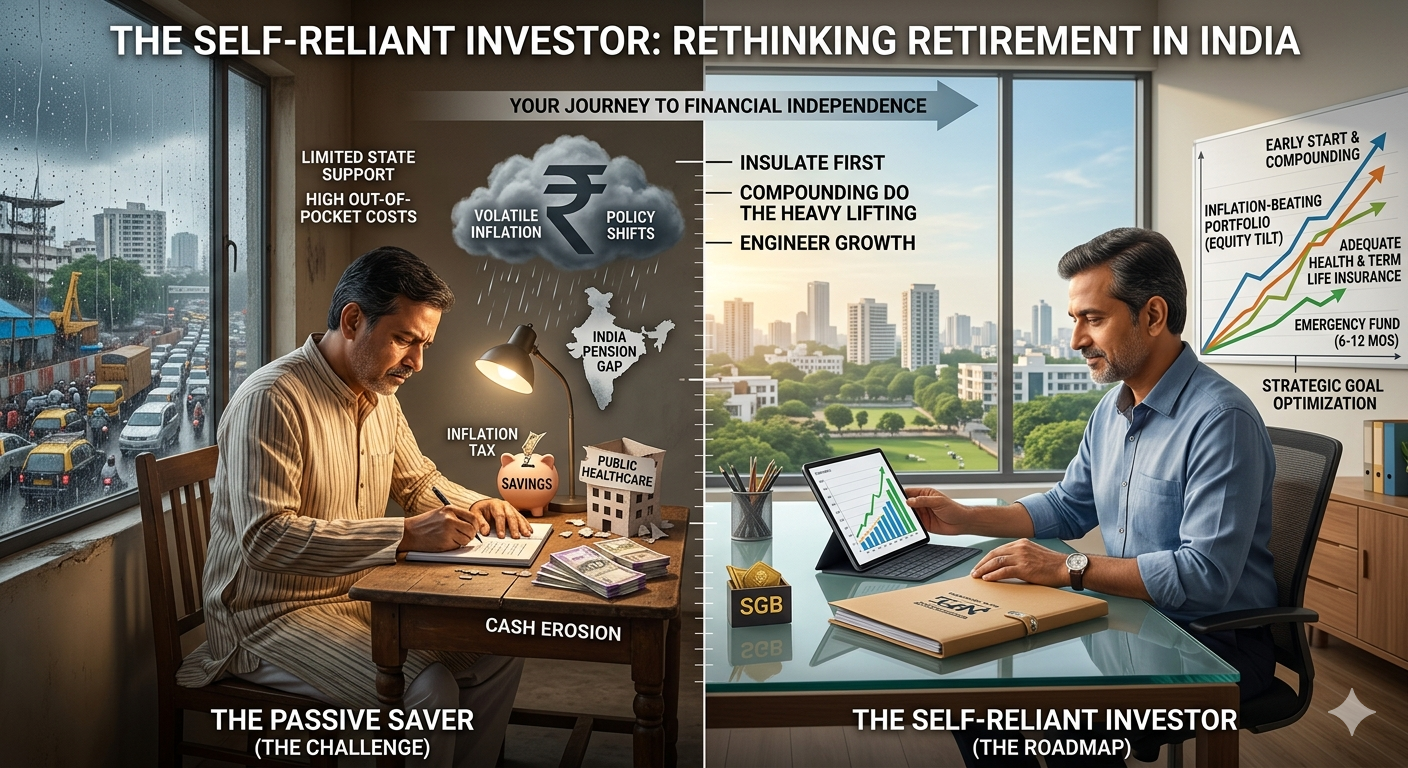
- The Public Provision Deficit: Competing fiscal priorities mean that universal healthcare, subsidized higher education, and state-funded welfare operate on a limited scale. You must fund these milestones privately.
- The Pension Gap: Formal mechanisms like the EPF and NPS cover only a fraction of the population. For the rest, a retirement income stream must be built from scratch.
- The Silent Tax (Inflation): Volatile inflation quickly dilutes fixed-income returns. Without assets that yield inflation-beating growth, your purchasing power will shrink dramatically over a 25-to-30-year retirement window.
- Policy and Interest Rate Volatility: Regulatory updates, shifting tax slabs, and fluctuating interest rates on traditional safety nets mean your plan must be dynamic, not set-and-forget.
A 4-Step Blueprint for Financial Independence
The system places the responsibility on you, but that also gives you total agency. India’s deepening financial markets and low-cost digital platforms offer all the tools required to build a resilient nest egg.
1. Insulate Before You Invest
Before chasing returns, build a defensive shield:
- Healthcare & Life: Secure a comprehensive health insurance policy (family floater + super top-up) and a pure term life plan.
- Liquidity: Maintain a liquid emergency fund covering 6 to 12 months of living expenses to ensure an unexpected crisis doesn’t force you to liquidate long-term equities.
2. Make Compounding Do the Heavy Lifting
Time is a multiplier that capital cannot easily replace. Starting early—even with modest Systematic Investment Plans (SIPs) in diversified equity mutual funds or low-cost index funds—allows compounding to turn small, disciplined contributions into a multi-crore corpus over two to three decades.
3. Engineer an Inflation-Beating Portfolio
Traditional fixed deposits (FDs) will struggle to preserve wealth against real inflation. A robust retirement asset allocation should tilt toward growth:
- Growth Assets: Equities and equity mutual funds to capture economic growth.
- Stability Assets: Public Provident Fund (PPF), Voluntary Provident Fund (VPF), and high-quality debt instruments for capital preservation.
- Hedging Assets: Gold exchange-traded funds (ETFs) or sovereign alternatives as a structural hedge.
4. Optimize for Goals, Not Just Tax Breaks
While maximizing allocations to tax-saving instruments (NPS, PPF, ELSS) makes strategic sense, do not let tax incentives dictate your entire investment thesis. Your primary driver should always be your net risk profile and long-term liquidity needs.
Also read: The New Wealth Code: Why 2026 is the Year to Buy Your Freedom
Also read: Laddering for Retirement: A Practical Guide

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.