
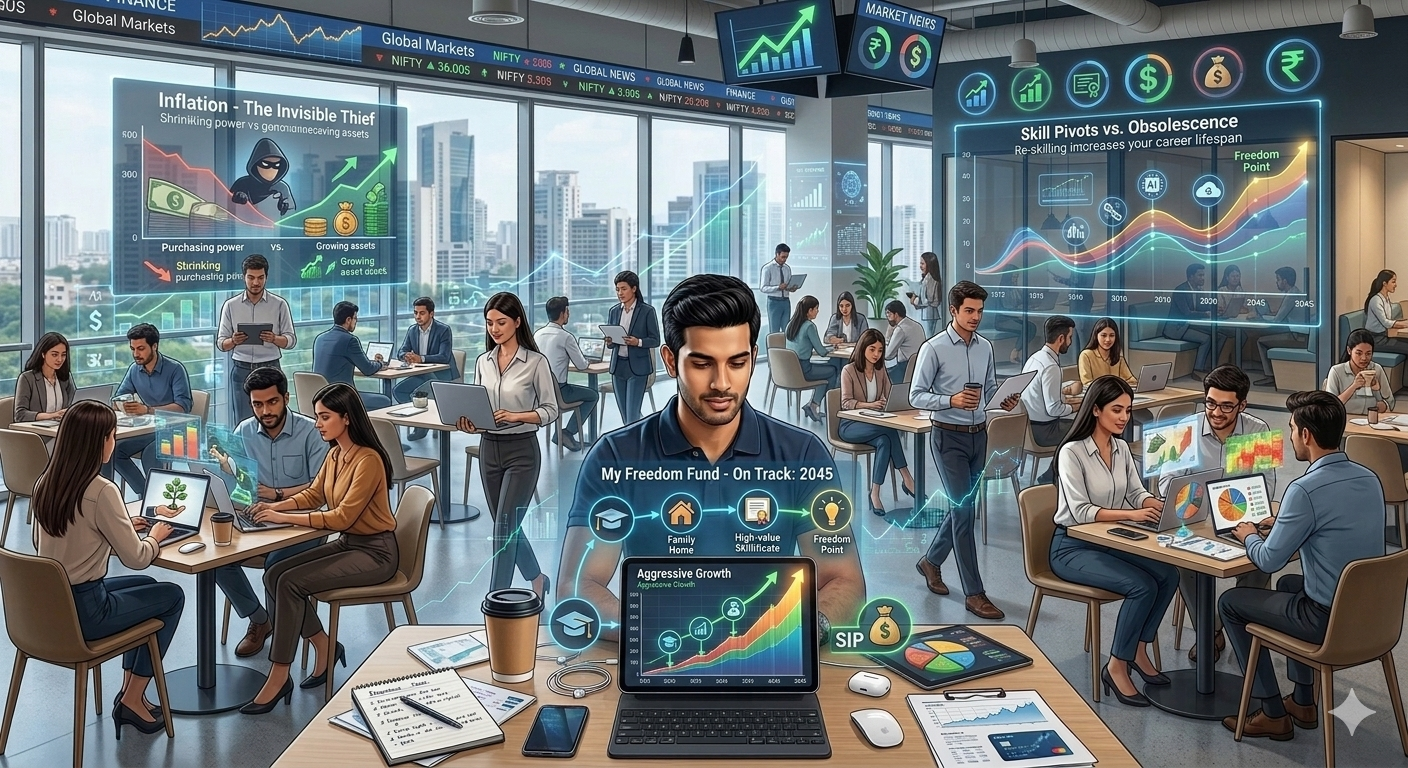
1. The “Subscription” Trap: Your 20s are the Beta Test
We live in a “Subscription Economy.” From Netflix to Gym memberships and even leased cars, your monthly income is being nibbled away by a thousand tiny bites.
The Strategy: Treat your retirement fund as your “Lifetime Subscription.”
Instead of paying a corporation for a service, you are paying your “Future Self” for the right to say “No” to a toxic boss or a soul-crushing commute. If you can afford a ₹999 premium coffee or a weekend binge-order on Zomato, you can afford a SIP.
- The Play: Automate an “Aggressive Growth” SIP (Small-cap or Mid-cap) the same day your salary hits. If it’s automated, it’s a bill. If it’s a bill, you’ll pay it. If you wait until the end of the month to “save what’s left,” you’ve already lost.
2. Inflation is a Thief (And You’re Leaving the Door Open)
Most Indian youth think keeping money in a Savings Account or a Fixed Deposit (FD) is “safe.” It’s not. It’s a slow-motion robbery. With India’s real inflation often hovering near 6–7% and FDs offering similar rates (pre-tax!), your purchasing power is actually shrinking. To stay ahead, you need to be an Owner, not a Loaner.
- The Difference: When you put money in an FD, you are loaning money to the bank. When you invest in an Index Fund or Equity, you own a piece of the companies that are hiking prices.
- The Math of 2045: That ₹100 Pizza today will likely cost ₹450 by the time you’re 45. If your money isn’t growing at 12%+, you aren’t saving; you’re just losing money slowly.
3. The “Portfolio of One” vs. The Index
The biggest risk for the Indian youth today isn’t a market crash—it’s Skill Obsolescence. AI is changing the job market faster than we can rewrite our CVs.
The Radical Approach: Your retirement plan must include a “Re-skilling Corpus.” True retirement planning in 2026 involves two buckets:
- The Financial Bucket: Compounding stocks/mutual funds to pay your bills.
- The Intellectual Bucket: A liquid fund used specifically to buy 3–6 months of time every five years to learn a new high-value skill.
By planning for “Career Pivots” now, you ensure that you never actually have to retire because you’re too tired to keep up. You retire because you choose to.
The “First Paycheck” Challenge
Don’t wait for a “stable” salary. The most legendary portfolios in India didn’t start with lakhs; they started with ₹500 and a boring, consistent habit. How to start today:
- Audit your “Leisure Tax”: Calculate how much you spent on apps/dining last month. Redirect just 20% of that into an Equity Mutual Fund.
- The 10% Step-Up: Every time you get a 10% raise, increase your investment by 10%. Your lifestyle stays the same, but your “Freedom Date” moves five years closer.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.