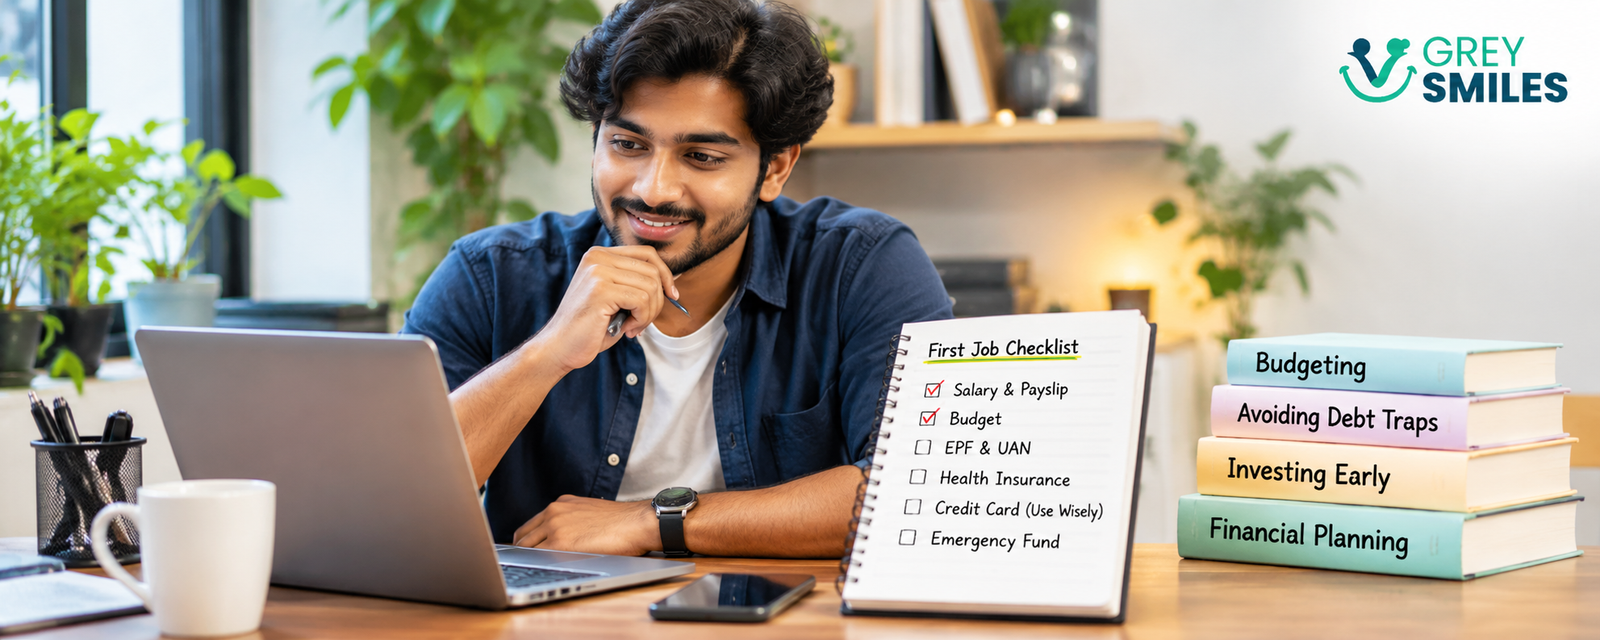
Important financial decisions to make when starting your first job.
Financial planning for your first job in India is about more than deciding how much to save or where to invest. It begins with understanding your salary, managing everyday expenses, using credit responsibly and making informed financial choices. The habits you develop in your first few years of employment can influence your financial independence for a long time.
At a Glance
Your first salary is more than a monthly credit in your bank account. It is the beginning of your financial life. The decisions you make now can influence your ability to save, borrow, invest and prepare for the future.
- Understand your salary structure, deductions and take-home pay.
- Build a realistic monthly budget before increasing your lifestyle spending.
- Avoid expensive purchases funded through multiple EMIs or Buy Now, Pay Later schemes.
- Be mindful of frequent food delivery, restaurant meals and other recurring discretionary expenses.
- Understand EPF, income tax, health insurance and credit before making financial commitments.
- Start building an emergency reserve and develop a regular savings habit.
Getting your first job is an important milestone. It brings financial independence, new responsibilities and the freedom to make your own spending decisions. For many young professionals, it is also the first time they have a regular income that they can manage independently.
It is natural to want to enjoy that freedom. You may want to buy a better phone, upgrade your laptop, travel, eat out more often or move into a better apartment. There is nothing wrong with enjoying what you earn. The challenge is ensuring that today’s choices do not quietly become tomorrow’s financial constraints.
Financial planning does not have to begin with complicated investment products or large savings targets. It begins with understanding your income, managing expenses, using credit responsibly and making a few sound decisions consistently.
Here are eight financial decisions worth getting right early in your career.
1. Financial Planning for Your First Job: Understand Your Salary
Your offer letter may mention an attractive Cost to Company (CTC), but the amount credited to your bank account every month will usually be lower. This is because CTC can include components that are not paid directly as monthly take-home salary.
Before planning your expenses, understand the difference between your CTC, gross salary and net take-home pay.
Pay attention to the following components:
- Fixed salary: The regular salary components payable to you.
- Variable pay: Performance-linked payments that may depend on individual or company performance.
- Employee Provident Fund (EPF): Your contribution towards retirement savings, where applicable.
- Employer contributions: Certain employer contributions may be included in the CTC but are not part of your monthly take-home salary.
- Gratuity: This may be included in the CTC structure, subject to applicable rules and eligibility.
- Tax deductions: Tax deducted at source (TDS) may reduce the amount credited to your account.
Read your first salary slip carefully. Check the deductions, understand the salary components and retain your payslips. They are useful records when applying for loans, changing jobs or completing financial documentation.
Do not build your monthly spending commitments around your CTC or an expected bonus. Plan using the salary that actually reaches your bank account.
2. Budgeting: The Foundation of Financial Planning
One of the most common mistakes is allowing spending to happen first and saving whatever remains at the end of the month. In the early years of employment, this can become a habit that is difficult to reverse as income and expenses increase.
Start with a simple monthly cash-flow plan. List your take-home income and divide your expenses into broad categories:
- Essential expenses: Rent, groceries, transport, utilities, basic communication costs and other necessary payments.
- Financial commitments: Existing EMIs, insurance premiums, family support and other obligations.
- Savings and investments: Emergency savings, long-term investments and money set aside for specific goals.
- Discretionary expenses: Dining out, shopping, entertainment, holidays, subscriptions and other lifestyle choices.
A useful starting point is to distinguish between needs, wants and desires. Needs are essential for living and working. Wants improve your quality of life but are not essential. Desires are often aspirational purchases that may be expensive or difficult to justify financially.
This distinction does not mean that you should never spend on wants or desires. It means that you should recognise what you are spending on and make room for it without compromising essential needs, savings or important goals.
The GreySmiles guide to creating a budget for millennials and Gen Z explains how budgeting can help connect everyday spending with longer-term financial goals.
Try setting aside a predetermined amount for savings soon after receiving your salary. Even if the amount is modest initially, consistency matters. Increase it as your income grows.
3. Avoid Lifestyle Traps: Expensive Purchases, EMIs and Everyday Spending
Your first salary can create a strong temptation to upgrade your lifestyle. You may feel that a better phone, premium laptop, expensive watch, new vehicle or branded wardrobe is a reasonable reward for getting your first job. Sometimes it is. But making several such purchases within a short period can put pressure on your finances before you have built a savings base.
Do not judge affordability by the monthly EMI alone
A phone costing ₹80,000 may appear affordable when the payment is divided into monthly instalments. The same may be true of a laptop, television, bike or car. But the EMI is only one part of the decision.
Before making an expensive purchase, consider:
- The full purchase price, including interest and other charges.
- Whether the product is genuinely necessary for your work or daily life.
- Whether a less expensive alternative would meet the same need.
- How many other EMIs you are already paying.
- Whether the monthly commitment will restrict your ability to save or handle an unexpected expense.
A ₹3,000 EMI may look small in isolation. But three or four such commitments can consume a significant part of your monthly take-home salary. The problem is not necessarily one purchase; it is the accumulation of commitments.
Be careful with Buy Now, Pay Later
Buy Now, Pay Later (BNPL) and similar payment options can make purchases feel almost effortless. You receive the product immediately and postpone the payment. However, deferred payment is still a financial obligation.
Do not use BNPL simply because the option is available at checkout. Avoid using it to fund routine purchases, shopping you have not budgeted for or a lifestyle you cannot comfortably afford. Understand the repayment date, fees and consequences of missing a payment before accepting the arrangement.
Watch the cost of eating out and ordering food
Another expense that can quietly grow after starting a job is food. Ordering lunch through an app, buying coffee and snacks during the workday, eating out several times a week and choosing fine-dining restaurants on weekends may each seem like a small indulgence.
But frequent spending adds up. A meal ordered for convenience, a daily coffee, weekend restaurant visits and occasional fine dining can together become a substantial monthly expense.
This is not an argument against enjoying restaurants or ordering food. It is about recognising the frequency and cost. If eating out is important to you, include it in your monthly discretionary budget rather than allowing it to become an unplanned daily expense.
Do not automatically increase spending every time your salary increases
As your income grows, you may move to a better apartment, buy a more expensive vehicle, upgrade gadgets and increase discretionary spending. These changes can be reasonable, but allowing every salary increase to be absorbed by lifestyle upgrades can leave your savings unchanged.
This is lifestyle inflation. The article Medical Inflation vs Lifestyle Inflation: Impact on Households explains how rising lifestyle expenses can affect a household’s ability to save and prepare for future costs.
If you tend to make unplanned purchases, the GreySmiles guide to impulsive shopping and financial discipline offers practical ways to pause and reconsider discretionary purchases before spending.
A useful habit is to wait 24–48 hours before making a non-essential expensive purchase. This gives you time to consider whether you need it, whether it fits your budget and what else that money could achieve.
4. EPF and UAN: Start Your Retirement Planning Early
If your employer provides coverage under the Employees’ Provident Fund (EPF), understand how the scheme works. EPF is an important retirement savings mechanism for eligible employees. It helps build a long-term corpus through contributions made by the employee and employer, subject to applicable rules.
There are a few things you should do when you start your first job:
- Understand the employee and employer contributions shown in your salary structure.
- Ensure that your Universal Account Number (UAN) is correctly linked to your employment records.
- Check that your personal details, including your name and date of birth, are accurate.
- Understand the process for transferring your EPF account when you change jobs.
- Keep your registered mobile number and other account details updated.
Do not view EPF only as a salary deduction. It is part of your long-term financial planning. Avoid making premature withdrawals without understanding the rules, tax implications and impact on your retirement savings.
As your career progresses, EPF can become one component of a broader investment and retirement strategy. You can read more about this in Building Your Retirement Corpus: Should You Rely Only on EPF?
5. Understand Income Tax Before the First Filing Season
Your first job may also be your first experience of income tax, tax declarations and filing an income tax return. Do not wait until the end of the financial year to understand how these work.
Start by understanding the following:
- Your estimated annual taxable income.
- The tax regime applicable to you and the differences between the available regimes.
- The deductions or exemptions that may be relevant to your circumstances.
- The tax declarations and investment proofs requested by your employer.
- The tax deducted at source (TDS) shown in your salary slips.
Do not make an investment or purchase simply because someone tells you that it will save tax. First understand whether the product suits your financial needs, time horizon and risk tolerance. Tax benefits should not be the only reason for making a financial commitment.
Keep your Form 16, salary slips, investment proofs and other relevant documents organised. Check your tax information and file your income tax return within the applicable timelines when required.
Tax rules can change, so refer to the official Income Tax Department portal for the applicable provisions and current requirements.
6. Do Not Depend Entirely on Your Employer’s Health Insurance
Many employers provide group health insurance as part of their employee benefits. This is valuable, particularly when you are beginning your career. However, it is important to understand what the policy actually covers.
Check the sum insured, room-rent limits, waiting periods, exclusions, co-payments and the process for making a claim. Also understand whether your parents or other family members are covered, and whether the policy provides any continuity if you leave the organisation.
Employer-provided insurance is linked to your employment. If you change jobs or take a career break, the coverage may change or end, depending on the policy terms.
Consider your personal health insurance needs independently of your employer’s benefits. The right decision will depend on your age, circumstances, existing coverage and financial capacity.
Do not assume that a group policy will automatically be sufficient for every future need. Understanding the limits early can help you avoid gaps in protection later.
7. Managing Credit and Debt in Your First Job
Your first job may make you eligible for a credit card or personal loan. Access to credit can be useful when managed carefully, but it can also encourage spending beyond your actual capacity.
Pay your credit card bill in full
Paying only the minimum amount due may help you avoid an immediate missed-payment status, but it does not mean that the outstanding balance has been cleared. Interest and other charges can accumulate on unpaid balances.
Use a credit card only when you can manage the repayment from your available income. Track your transactions and pay the full outstanding amount by the due date whenever possible.
Borrow for a reason, not because credit is available
Before taking a personal loan, consumer loan or other form of credit, ask whether the borrowing is necessary. Compare the interest rate, total repayment amount, tenure, processing charges, late-payment fees and prepayment conditions.
Do not borrow simply to buy a more expensive phone, take a holiday or maintain a lifestyle that your current income cannot support. A loan converts today’s spending into a future repayment obligation.
It is also important to understand how your different loan commitments affect your monthly cash flow. The total EMI burden matters more than looking at each loan separately.
If you already have multiple debts, understand the repayment approaches available. The GreySmiles guide to debt repayment strategies in India explains the Avalanche and Snowball methods and how they can be used to prioritise repayment.
Also read Everything Can Be Financed with a Loan. Except Retirement. It explains why borrowing commitments can gradually reduce the money available for long-term financial goals.
8. Organise Your Financial Documents and Build an Emergency Reserve
Financial independence also means being able to access and manage your important financial information. From your first job, create a secure system for storing your documents and maintaining accurate records.
Keep track of:
- Offer letters, employment contracts and salary slips.
- PAN, Aadhaar and bank account details.
- EPF and UAN information.
- Health insurance policy documents and details of coverage.
- Credit card statements, loan agreements and repayment schedules.
- Investment account details and relevant tax documents.
Check the nominee details in your bank accounts, insurance policies and eligible financial accounts. A nomination is an important administrative step, although it does not necessarily replace the legal process for determining ownership or succession.
Start an emergency fund
An unexpected job loss, medical expense, family emergency or urgent relocation can disrupt your finances. An emergency reserve helps you manage such situations without immediately turning to credit cards or high-interest loans.
A commonly used starting guideline is to build a reserve equivalent to three to six months of essential living expenses. Your actual requirement may be higher or lower depending on job stability, dependants, existing liabilities and other circumstances.
Keep emergency money accessible and separate from your long-term investments. It should be available when needed, rather than exposed to unnecessary market risk.
A First-Job Financial Checklist
Use this checklist to review the basic financial arrangements you should have in place during your first year of employment.
- Understand your CTC, gross salary and monthly take-home pay.
- Read your salary slip and identify all deductions.
- Create a monthly budget based on actual take-home income.
- Set a regular savings amount and automate it where practical.
- Understand your EPF contributions and UAN.
- Review your income tax position and retain relevant documents.
- Understand the coverage and limitations of employer-provided health insurance.
- Pay credit card bills in full and avoid unnecessary borrowing.
- Evaluate the total cost before taking on an EMI or BNPL commitment.
- Track discretionary expenses, including food delivery and dining out.
- Build an emergency reserve.
- Review nominee details and organise important financial documents.
The GreySmiles Take
Your first job is an opportunity to establish financial habits that can support you for decades. You do not need to become an aggressive saver or avoid every purchase that gives you pleasure. You need to understand the difference between enjoying your income and committing your future income before you have earned it.
Be careful about the expensive phone bought on EMI, the credit card balance that is never fully paid, the frequent food orders that are not tracked or the lifestyle upgrades that follow every salary increase. These decisions may seem manageable individually, but together they can restrict your financial choices.
Start with the basics: understand your income, budget your expenses, save regularly, borrow carefully and protect yourself against unexpected events. As your income and responsibilities change, review your financial plan rather than allowing old habits to dictate new decisions.
Financial independence is not created by one investment or one large salary increase. It is built through a series of informed decisions made consistently over time.
Frequently Asked Questions
How much should I save from my first salary?
There is no single savings percentage that works for everyone. Start with an amount that is realistic after accounting for essential expenses and financial obligations. The important thing is to make saving a regular part of your monthly plan and increase it as your income grows.
Should I buy an expensive phone or laptop on EMI after getting my first job?
Consider whether the purchase is necessary, whether a less expensive option will meet your needs and whether the EMI fits comfortably within your budget. Do not judge affordability only by the monthly instalment. Consider the total cost and all your existing commitments.
Is Buy Now, Pay Later a good option for young professionals?
BNPL can defer payment, but it does not make a purchase free. Understand the repayment terms, charges and consequences of delayed payment. Avoid using it to fund routine expenses or purchases that you cannot afford from your current income.
Should I start investing as soon as I get my first salary?
Starting early can help develop a long-term savings and investment habit. However, first understand your cash flow, manage high-cost debt and begin building an emergency reserve. Investment choices should reflect your goals, time horizon and ability to take risk.
Is employer-provided health insurance enough?
It depends on the policy’s coverage, limits, exclusions and your personal circumstances. Employer coverage is valuable, but it may change when you leave the organisation. Review the policy carefully and assess whether you need separate personal health insurance.
Why should I start retirement planning so early in my career?
Starting early gives you more time to build savings and benefit from compounding. It also helps you develop the habit of connecting present spending with future needs. Retirement may seem distant when you start working, but the financial foundation is easier to build gradually than to create later.
Sources & References
- NISM – Managing Your Income and Expenses
- NISM – Budgeting
- NISM – Understanding Needs, Wants and Desires
- NISM – Investment Adviser Level 1 Curriculum
- SEBI Investor – Think Before You Borrow Money
- Employees’ Provident Fund Organisation
- Income Tax Department
- Insurance Regulatory and Development Authority of India
Disclaimer: This article is intended for general financial awareness and education. It does not constitute personalised investment, tax, insurance or legal advice. Readers should assess their individual circumstances and consult qualified professionals where necessary.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.