
When your parents live in India and you live abroad, their finances can become strangely difficult to see.
You may know that they have a house, some investments and a pension. You may occasionally transfer money to them. But do you know which bank accounts they use, where their investments are held, when their insurance renews or what happens if one parent suddenly has to manage everything alone?
Financial planning across countries is not about taking over your parents’ money. It is about making sure that the family understands the financial picture before there is a crisis.
At a Glance
- Parents should retain control over their finances for as long as they are able to manage them.
- Children abroad should understand the broad picture: income, investments, property, insurance, liabilities and important documents.
- Nominations and estate documents should be reviewed rather than assumed to be correct.
- Emergency access and financial visibility are different from giving someone unrestricted control over assets.
- The aim is continuity: if one parent becomes ill or dies, the family should know what needs to happen next.
Start With Visibility, Not Control
There is an important difference between knowing what your parents own and controlling what they own. Your parents may be perfectly capable of managing their investments. They may simply need someone else in the family to know where everything is in case of an emergency.
That is a much healthier starting point than asking for access to every account. If your parents are financially capable, their independence should be respected while ensuring that the family has enough information to provide help when it is genuinely needed.
What Should the Family Map?
You do not need a complicated financial statement. A simple family financial map can help the family understand the broad picture without turning the exercise into an attempt to manage every financial decision.
| Area | What to Record |
|---|---|
| Bank accounts | Banks, account type and regular income/expenses |
| Retirement income | Pension, EPF, EPS, NPS and other income |
| Investments | Mutual funds, deposits and other financial assets |
| Insurance | Health, life and other relevant policies |
| Property | Ownership, documents and loans |
| Estate planning | Will, nominations and important documents |
The purpose is not to create a record of every rupee your parents spend. It is to answer a few basic questions if something unexpected happens: what do they have, what do they owe, what income comes in, which expenses need to continue, where are the documents and who needs to be contacted?
GREYSMILES CALCULATOR
How much retirement corpus may be needed?
Use the GreySmiles Corpus Calculator to explore how retirement spending, income and other assumptions can affect the corpus you may need.
Don’t Assume the Children Need to Manage Everything
One of the easiest mistakes for an NRI child to make is to think that because they live abroad, they need to organise their parents’ finances from a distance. They don’t necessarily.
If your parents are financially capable, their independence should be respected. Your role may simply be to help them organise information, review important documents and know who to contact when necessary.
The arrangement may change over time. A parent who manages everything independently today may need more support a few years from now, but planning for that possibility does not mean assuming that they are incapable today.
What Happens If One Parent Dies First?
This is where a little preparation can make an enormous difference. The surviving spouse may suddenly have to deal with bank accounts, investments, insurance claims, property documents, pensions and tax matters while also dealing with grief.
Knowing in advance where the important information is kept can remove some of that burden. A useful family exercise is to sit together and discuss what the surviving parent would need to know if one spouse suddenly became unavailable.
What About Power of Attorney and Access?
These are matters where families should be careful. Giving another person authority over financial matters can have significant legal consequences, and the appropriate arrangement depends on the circumstances.
It is therefore better to discuss the need with a qualified professional than to create informal arrangements simply because a child lives abroad. The principle is straightforward: create the minimum authority necessary for the situation, rather than assuming more access is always better.
Having access to information is also not the same as having authority to operate an account or make decisions on someone else’s behalf.
Protect the Family From Financial Mistakes
Ageing parents can become more vulnerable to financial fraud, unsuitable investments or pressure from people they trust. That does not mean children should monitor every financial decision.
A periodic conversation about major investments, unusual requests for money and changes in financial circumstances can provide a useful second layer of protection without removing parental independence.
Keep the Information Somewhere Sensible
A financial map is useful only if the family can find it when needed. Parents and children should agree where important documents and contact details are recorded and who should know about them.
Security matters too. Sensitive financial information should not simply be circulated across multiple messaging groups because a child lives overseas. The family can instead maintain a secure record of where information is held and who should be contacted, with actual access arranged separately where necessary.
Don’t Make Every Financial Conversation About Money
Parents may already feel that their children are worried about them because they are getting older. Repeated questions about bank balances, investments and property can unintentionally make those conversations feel intrusive.
It can help to make financial planning part of a broader conversation about life after retirement. Talk about healthcare, who will help if one parent is hospitalised, where important papers are kept and who can help if everyday banking becomes difficult.
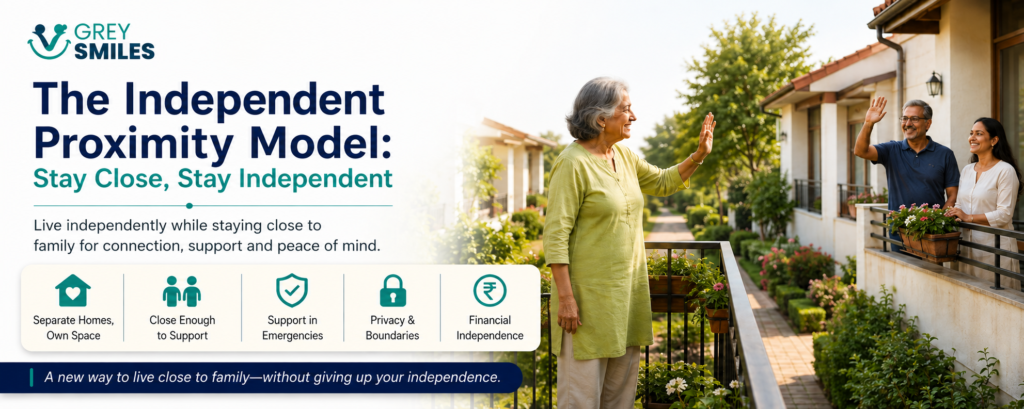
This wider perspective is also important for independent living. Children living abroad do not automatically mean that parents need more financial control or a change in their living arrangements. What matters is whether the wider support system around them is strong enough for the life they want to lead.
This is closely connected to the thinking behind the GreySmiles Independent Proximity framework, which looks at independence, family proximity and practical support as connected parts of later life.
Keep an Eye on Cross-Border Complications
Living in another country can add another layer to family finances. Parents may have investments, pensions, property and bank relationships in India, while their children have income, assets and financial obligations overseas.
The child may also occasionally send money to India to support parents or pay for specific expenses. This does not automatically mean that the family’s finances need to be combined; it simply means that everyone should understand which financial responsibilities belong to whom.
Where significant money is being transferred between countries, or where the child is becoming involved in managing Indian assets, it is sensible to obtain appropriate tax, legal or financial advice rather than relying on informal family arrangements.
What If the Current Support Arrangement Stops Working?
A support system that works today may not work five years from now. Parents’ health can change, a trusted neighbour may move away, a spouse may pass away or children may find themselves unable to provide the same level of support from abroad.
That does not mean the family has failed. It simply means the arrangement may need to change, whether through additional home support, a trusted local contact, more family involvement or, eventually, a different living arrangement.
The right answer will depend on health, finances, preferences, family circumstances and the kind of life parents want. The important point is that support should be considered because the current arrangement no longer works, not simply because the children live abroad.
Families who want to think more systematically about independent living can also explore the Independent Proximity approach and the wider questions around ageing independently in India.
Use Numbers to Support the Conversation
Sometimes the family conversation will reveal a second question: is the retirement income and corpus actually sufficient for the life the parents want to maintain?
That is where calculators can complement the conversation without replacing professional advice.
GREYSMILES CALCULATOR
Explore retirement withdrawals
If your parents are already drawing from investments, the GreySmiles SWP Calculator can help you explore how withdrawals may behave under different assumptions.
GREYSMILES CALCULATOR
Plan for future healthcare costs
Healthcare can become an important part of retirement spending. The GreySmiles Health Planner can help families bring potential healthcare costs into the wider retirement conversation.
Review the Financial Map Once a Year
The family financial picture will change. A new bank account may be opened, an investment may mature, a policy may be renewed or replaced, a property may be sold, a loan may be repaid or a nomination may need updating.
This is why creating the map once is not enough. A short annual review can be useful, perhaps around the same time each year, simply to ask what has changed and whether the important information is still current.
The review does not need to become a formal family meeting. Even a short conversation can help confirm that the surviving parent would know what to do if the other parent were suddenly unavailable and that everyone understands who to contact when necessary.
GreySmiles Take
The best financial arrangement between parents and NRI children is not necessarily the one where the child has the most access. It is the one where everyone knows enough to act when necessary, while the parents retain as much control and independence as they can safely manage.
A Simple Family Checklist
If you are living abroad and your parents are in India, start with these questions rather than trying to organise everything at once. You do not need to solve every issue in one conversation; the objective is simply to identify the gaps that matter most.
- Do we know where their main bank accounts are?
- Do we know what regular income they receive?
- Do we have a broad idea of their investments and property?
- Do we know which health and other important insurance policies they have?
- Do we know where the important documents are kept?
- Have they reviewed their nominations and Will?
- Would the surviving parent know how to manage the household finances if the other parent were suddenly unavailable?
- Do we know whom to contact locally in an emergency?
- Have we discussed what kind of help our parents actually want from us?
Have the Conversation Before You Need the Information
You don’t need to ask your parents to hand over their financial lives. Start with something much simpler: “If something happened to either of you, would we know where everything is?”
If the answer is no, begin there. The goal is not to build a system where children living abroad control their parents’ finances from thousands of kilometres away. It is to build enough understanding that distance does not become a problem when help is suddenly needed.
For many families, that may be the most practical form of financial planning they can do together.
Sources & References
GreySmiles’ related guides on retirement planning, independent living, family support, estate planning and assisted living provide additional context for families working through these questions.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.