
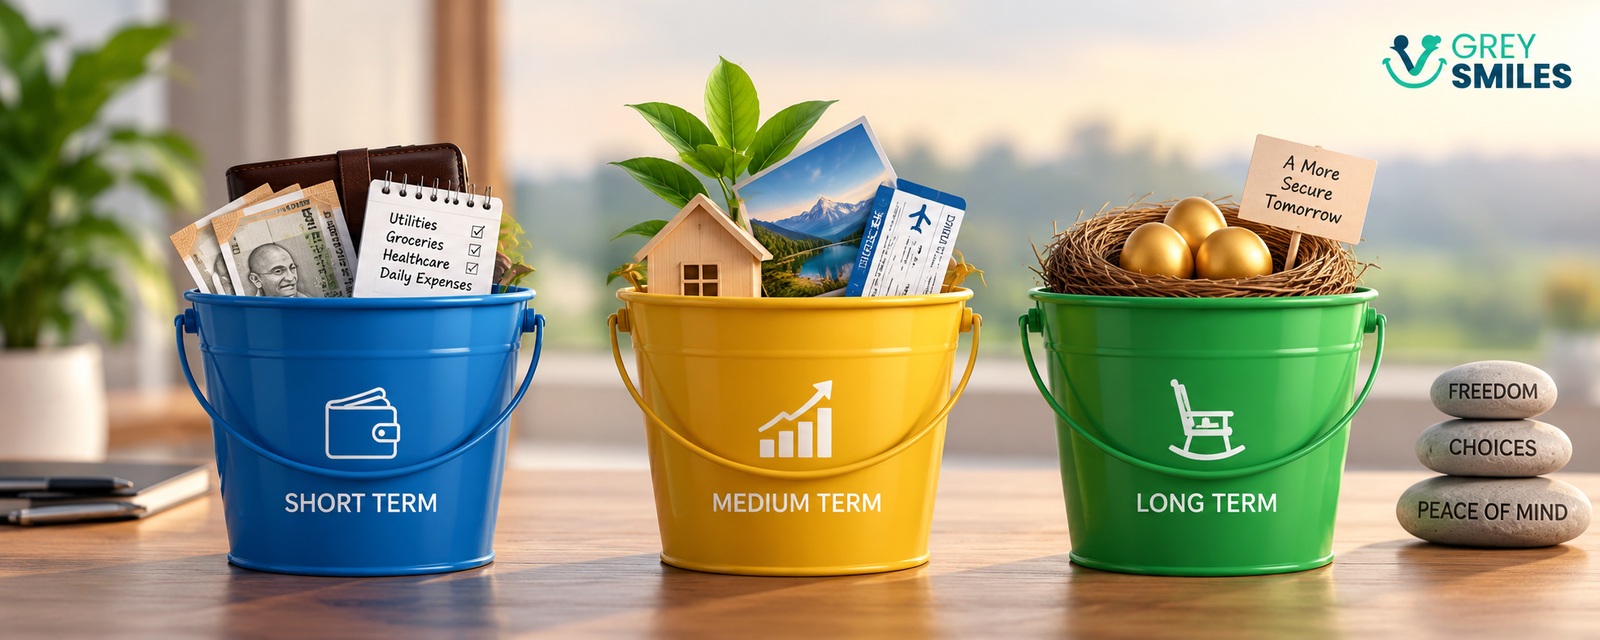
Three-bucket strategy for retirement showing short-term, medium-term and long-term money
Retirement changes the job your money has to do. While you are working, most of your financial attention is usually on earning, saving and building wealth. After retirement, the focus shifts. Your investments may need to provide regular cash flow while still retaining enough growth potential to support a retirement that could last for decades.
That creates a difficult balance. Keeping everything in very safe investments may limit growth. Keeping too much in growth assets can expose money that you may need soon to market volatility.
The 3-bucket strategy is one way of organising a retirement portfolio around these different jobs. Instead of treating the entire corpus as one pool of money, it separates the portfolio into three broad buckets based on when and how the money is expected to be used.
At a Glance
- Bucket 1 is for near-term spending and liquidity.
- Bucket 2 is intended to provide stability for the medium term.
- Bucket 3 is the longer-term growth portion of the portfolio.
- The buckets are not three completely separate portfolios. They are parts of one retirement-income strategy.
- There is no universal percentage split that works for every retiree.
- The strategy works only if you have a process for spending, reviewing and replenishing the buckets.
What Is the 3-Bucket Strategy?
The basic idea is straightforward: divide retirement assets according to their expected time of use.
| Bucket | Primary job | Typical time horizon |
|---|---|---|
| Bucket 1 | Near-term spending and liquidity | Short term |
| Bucket 2 | Stability and funding for the following years | Medium term |
| Bucket 3 | Long-term growth | Long term |
The exact investments used in each bucket can vary. What matters is the job assigned to the money.
This distinction is important because a bucket strategy is not simply a recommendation to own cash, debt and equity in three equal portions. It is a way of connecting asset allocation with the timing of future withdrawals.
Bucket 1: Money You Expect to Spend Soon
The first bucket is designed for money that you expect to need in the relatively near future.
This is the part of the portfolio where avoiding unnecessary market volatility becomes particularly important. If money is required for household expenses next month or next year, you do not want its availability to depend entirely on what equity markets happen to do that week.
Depending on your circumstances, this bucket may include cash, savings accounts, short-term deposits or other relatively liquid and lower-volatility instruments.
The objective is not to maximise returns. It is to provide liquidity and stability.
What should Bucket 1 cover?
There is no universal number of months or years that every retiree should hold. Your requirement will depend on your dependable income, spending pattern, other assets and comfort with market volatility.
It can be useful to start with expenses that genuinely need to be funded from the portfolio.
For example, if pension or other dependable income covers a substantial portion of essential household expenses, the amount that needs to sit in the first bucket may be lower than it would be for someone whose portfolio must fund almost all regular spending.
This is one reason why a retirement-income plan should begin with cash-flow needs rather than an arbitrary bucket percentage.
Bucket 2: The Stability Layer
The second bucket sits between immediate spending and long-term growth.
Its role is to provide a relatively stable source from which the first bucket can be replenished over time.
This may include instruments such as high-quality fixed-income investments, deposits or other investments chosen for their role in providing stability rather than maximum growth.
The idea is to avoid forcing the long-term growth portion of the portfolio to fund every withdrawal immediately.
However, “stable” does not mean “risk-free”. Interest-rate risk, credit risk, reinvestment risk, inflation and taxation can all affect fixed-income investments.
The second bucket therefore needs to be evaluated as carefully as the growth bucket.
Bucket 3: The Long-Term Growth Engine
The third bucket contains money that is intended to remain invested for the longer term.
This is where growth assets may have a role.
For a retirement that could last 20, 25 or even 30 years, keeping every rupee in low-growth assets can create another risk: the portfolio may lose purchasing power over time.
Equity and other growth-oriented investments can potentially help the portfolio keep pace with long-term inflation and support spending later in retirement.
But this bucket should not be viewed as a pot of money that can never be touched. It is still part of the overall retirement portfolio, and its value will fluctuate.
The key distinction is that you are giving this money more time to recover from periods of market decline.
The Three Buckets Are Connected
This is where many explanations of the strategy become too simplistic.
You do not create three buckets once and then leave them untouched.
They should work together.
In a simplified example:
- Regular retirement expenses are funded from Bucket 1.
- Bucket 1 is replenished periodically from Bucket 2 or other income sources.
- Bucket 2 is replenished over time using the broader portfolio and available income.
- Bucket 3 remains invested for long-term growth and may eventually be used to replenish the more conservative portions of the portfolio.
The actual sequence will depend on market conditions, tax considerations, income sources and your personal withdrawal plan.
Why Use Buckets at All?
The biggest attraction of the bucket strategy is psychological as much as financial.
A retiree who needs money every month can become uncomfortable when the market falls sharply. If the same portfolio is also expected to provide today’s spending and tomorrow’s growth, a market decline can create pressure to sell investments at an inconvenient time.
A bucket structure can create a buffer between immediate spending and long-term investments.
That does not eliminate investment risk. It changes how the portfolio is organised around that risk.
It can also make retirement finances easier to understand. Instead of asking whether the entire portfolio is “safe”, you can ask whether the money required in the near term is appropriately positioned, whether the medium-term reserve is adequate and whether enough capital remains invested for the later years.
How Much Should You Put in Each Bucket?
This is the question for which generic 3-bucket articles often provide an overly neat answer.
You may see allocations such as one-third in each bucket or a fixed percentage in cash, debt and equity.
There is no reason to assume that those percentages are appropriate for everyone.
A better starting point is to calculate your expected withdrawals and dependable income.
For example, consider two retirees:
| Retiree | Situation | Possible implication |
|---|---|---|
| A | Has a dependable pension covering most essential expenses | May need less of the portfolio dedicated to immediate withdrawals. |
| B | Depends heavily on investments for monthly expenses | May need a larger liquidity and stability reserve. |
The right allocation therefore starts with cash-flow requirements, not bucket percentages.
What About Inflation?
Holding too much money in the safest possible instruments can create an inflation problem.
Suppose your retirement spending rises over time while the purchasing power of your conservative assets does not keep pace. A portfolio can appear stable in rupee terms while becoming less useful in real terms.
This is why the third bucket matters.
Long-term retirement planning needs some exposure to assets that have the potential to grow over time. The appropriate amount will depend on the individual, but avoiding all volatility is not the same as avoiding risk.
There are two different risks to consider:
- Market risk: the value of investments can fall.
- Purchasing-power risk: money that grows too slowly may buy less in the future.
A sensible retirement portfolio has to recognise both.
The Biggest Risk: Selling Growth Assets After a Market Fall
One reason the bucket approach can be useful is that it can reduce the need to sell growth investments during a temporary market decline.
Imagine a retiree whose portfolio is heavily invested in equity. Markets fall 25% just as the retiree needs to fund household expenses.
If there is no other source of liquidity, some investments may have to be sold despite the fall.
A separate near-term reserve can provide more room to wait for markets to recover.
That does not guarantee a better investment outcome. Markets may remain weak for longer than expected, and a reserve can itself lose purchasing power. But the structure can reduce the pressure to make a forced decision at a difficult time.
How Do You Refill the Buckets?
A bucket strategy is incomplete without a replenishment process.
There are several possible approaches.
When markets are doing well
You may choose to realise some gains from longer-term investments and replenish the more conservative buckets, depending on your allocation and tax situation.
When markets are falling
You may allow the near-term bucket to fund spending for a period rather than selling growth assets immediately.
When dependable income increases
A pension increase, rental income or another dependable cash-flow source may reduce the amount that needs to be withdrawn from investments.
During your annual review
You can reassess the size of each bucket against your updated spending, portfolio value, expected income and retirement horizon.
There is no single refill rule that must be followed. The important thing is to have a rule rather than making every decision emotionally after a market move.
Where Do Mutual Funds Fit?
Mutual funds are not a bucket by themselves.
A mutual fund is an investment vehicle. Its role depends on what the fund invests in and why you are holding it.
For example, an equity mutual fund may form part of the long-term growth bucket, while certain debt-oriented funds may play a role in a more stable portion of the portfolio.
The same product should not automatically be treated as “retirement safe” simply because it is being used for retirement.
The important question is what the investment is expected to do inside the overall plan.
GreySmiles explores this distinction in more detail in Mutual Funds for Retirement.
Where Do NPS and Other Retirement Products Fit?
NPS, provident fund balances, deposits, annuities and other retirement products can all form part of a broader retirement plan.
But they should not automatically be assigned to a bucket simply because they are labelled as retirement products.
For example, the part of your financial resources that provides dependable retirement income may reduce the amount your investment portfolio needs to generate. Similarly, money with restrictions on access may not be suitable for meeting a near-term liquidity requirement.
The product’s liquidity, risk, expected return, tax treatment and income characteristics should be considered before deciding what role it plays.
What the 3-Bucket Strategy Does Not Solve
A bucket strategy is a portfolio organisation method. It is not a complete retirement plan.
It does not tell you:
- how much money you need to retire;
- what your ideal retirement spending should be;
- which investment product you should buy;
- what withdrawal rate is guaranteed to be sustainable;
- how much healthcare may cost you;
- how your taxes will change your cash flow; or
- whether you are financially ready to retire.
Those are separate decisions.
The bucket strategy becomes useful only after those questions have been considered.
Three Common Mistakes With Bucket Strategies
1. Treating the buckets as fixed percentages
A 33%-33%-33% portfolio may look tidy, but neat percentages do not necessarily correspond to your actual cash-flow needs.
2. Making Bucket 1 too large
Keeping a very large amount in low-growth assets can create a different problem: the portfolio may struggle to maintain purchasing power over a long retirement.
3. Ignoring the replenishment process
Even a well-designed first bucket will eventually run down. Without a plan for replenishing it, the strategy is only delaying the decision.
How the Strategy Changes as Retirement Progresses
Your bucket structure does not have to remain identical throughout retirement.
Before retirement, you may have a long accumulation period and relatively little need for a dedicated spending bucket.
As retirement approaches, the focus can shift towards establishing enough liquidity for the early years and clarifying how the portfolio will generate income.
Later in retirement, healthcare needs, longevity and changing spending patterns may become more important.
The appropriate structure can therefore evolve with your life rather than following a fixed formula.
A Simple Way to Build Your Own Bucket Framework
- Estimate your retirement spending. Separate essential and discretionary expenses where useful.
- Identify dependable income. Include pension and other income you can reasonably rely on.
- Calculate the amount your portfolio needs to provide.
- Decide how much near-term liquidity you need.
- Set aside a medium-term stability layer.
- Invest the remaining long-term capital according to your overall asset allocation.
- Create rules for withdrawals and replenishment.
- Review the structure periodically.
This approach prevents the buckets from becoming an arbitrary exercise in dividing a corpus into three equal parts.
How the 3-Bucket Strategy Fits Into Retirement Planning
The bucket approach sits relatively late in the retirement-planning process.
First, you need to understand what retirement may cost. Then you need to estimate the corpus required, consider dependable income and decide how your assets should be positioned.
Only then does the question of how to organise the portfolio for withdrawals become particularly useful.
If you are still working out your overall retirement requirement, start with retirement corpus calculation.
Once the corpus is clearer, a withdrawal strategy becomes the next important consideration. You can also read How to Withdraw From Your Retirement Corpus to understand the transition from accumulated wealth to retirement income.
A Practical Bucket Checklist
- ☐ I know approximately how much I expect to spend each year in retirement.
- ☐ I have separated essential expenses from discretionary spending.
- ☐ I know how much dependable income I expect after retirement.
- ☐ I know how much my investment portfolio needs to provide.
- ☐ I have enough accessible money for near-term requirements.
- ☐ I have considered how the medium-term portion of the portfolio will provide stability.
- ☐ I still have enough long-term growth exposure to address inflation and longevity risk.
- ☐ I know how the first bucket will be replenished.
- ☐ I have considered taxes and liquidity restrictions before assigning investments to a bucket.
- ☐ I review the strategy rather than changing it emotionally after every market movement.
The Point of the Buckets
The 3-bucket strategy is not about finding three perfect investments.
It is about giving different parts of your retirement money different jobs.
Money you need soon should not have to behave like long-term growth capital. At the same time, money that may be needed 15 or 20 years from now does not necessarily need to sit entirely in the safest available asset.
Separating those jobs can make a retirement portfolio easier to manage and can create more room to stay invested when markets become uncomfortable.
But the strategy works best when it is built around your actual spending, income, retirement horizon and risk capacity — not around a fashionable percentage split.
Sources & References
- SEBI Investor – Retirement Planning
- SEBI Investor – Financial Goal Planner
- PFRDA – National Pension System
Disclaimer: This article is for educational and informational purposes only and should not be treated as personalised financial advice. Retirement outcomes depend on individual circumstances, investment performance, inflation, taxation, spending and longevity. Investment values can rise or fall. Product features, tax rules and regulations can change, so verify current information from the relevant official source before making financial decisions.


Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.