
At a Glance
Your FIRE number is an estimate of the financial resources you may need before employment becomes optional. It is useful because it turns the idea of financial independence into something you can plan around.
- Start with the life you want to fund, not an arbitrary corpus number.
- The 25X rule can be a useful starting point, but it is not a guarantee.
- Your FIRE number can change with inflation, healthcare, housing, family responsibilities and the age at which you want work to become optional.
- The earlier you want to stop working, the more carefully you need to think about how long the money may have to last.
- The useful calculation is not just “How much do I need?” but also “What would have to be true for this number to work?”
What Does a FIRE Number Actually Tell You?
The appeal of FIRE is easy to understand. You want enough financial independence that work becomes a choice rather than something you must continue doing to pay the bills.
The difficult part is deciding what “enough” means.
Your FIRE number is the approximate corpus you are aiming for. But it has meaning only in relation to the life that corpus is expected to fund. Someone who wants to retire at 42, travel regularly and support family members may need a very different number from someone who plans to work until 50, owns a debt-free home and expects to continue earning some income.
That is why a FIRE calculation should be treated as a planning exercise rather than a magic number.
GreySmiles’ broader guide to the FIRE movement in India looks at the wider idea. This article focuses on the narrower question: how do you work out your own FIRE number?
The 25X Rule Is a Starting Point, Not the Answer
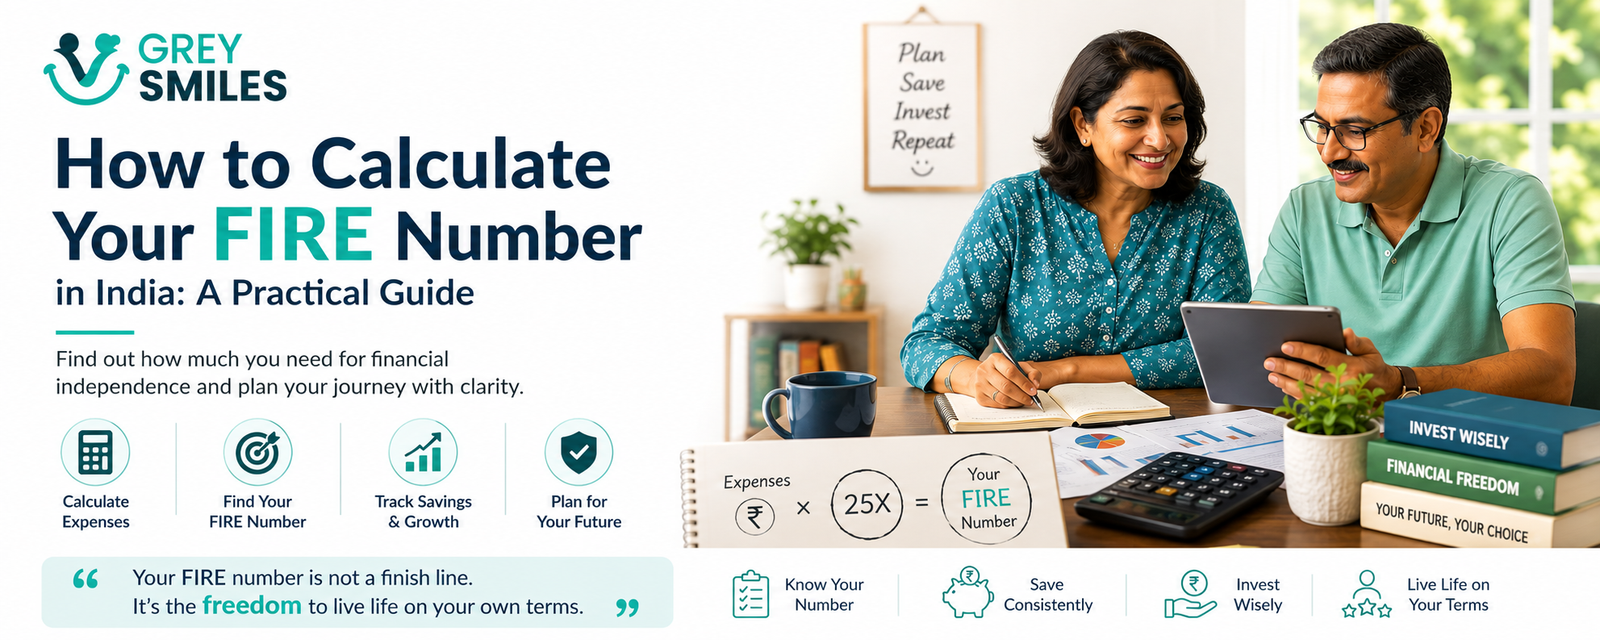
The simplest FIRE calculation is:
FIRE number = expected annual spending × 25
If you expect to spend ₹6 lakh a year, 25X would give you a starting target of ₹1.5 crore.
That is easy to calculate. The harder question is whether ₹1.5 crore would actually support the life you have in mind.
The 25X idea is linked to a roughly 4% initial withdrawal framework. It is widely used as a FIRE planning heuristic, but it should not be treated as a promise that a particular portfolio will last for a particular person’s lifetime. Your investment mix, withdrawal pattern, inflation, taxes, market conditions and retirement duration all matter.
For someone planning a conventional retirement, a rough multiple may be a useful first conversation. For someone hoping to leave work in their 30s or 40s, the assumptions deserve considerably more attention.
Before You Multiply Anything, Work Out What You Want to Spend
This is where many FIRE calculations become detached from real life.
People often take today’s annual spending, multiply it by 25 and declare a target. But today’s spending may not be the spending you want once work becomes optional.
Look at your actual household spending first. Then separate it into broad groups:
| Expense | What to think about |
|---|---|
| Essential | Housing, food, utilities, insurance, basic transport and other costs you would still need to meet. |
| Lifestyle | Travel, hobbies, dining out, entertainment, memberships and other things that make retirement enjoyable. |
| Family | Support for children, parents or other family members that you expect to continue. |
| Healthcare | Insurance premiums, medicines, consultations, treatment and expenses that may not be fully covered. |
| Irregular | Home repairs, vehicles, large purchases, family events and other costs that do not appear every month. |
The GreySmiles guide on what you may actually need to spend in retirement goes deeper into this exercise. The same thinking is useful for FIRE: the number should describe the life you are trying to fund.
Then Bring Inflation Into the Picture
If you are 35 and hoping to become financially independent at 45, today’s expenses are not necessarily the expenses your portfolio will have to fund at 45.
Suppose your household spends ₹10 lakh a year today. If you simply multiply that by 25, you get ₹2.5 crore. But if ten years of inflation have materially increased the cost of the same lifestyle, the future spending number will be higher.
The calculation therefore needs to reflect when you expect to achieve financial independence, not just how much you spend today.
Do not treat an assumed inflation rate as a forecast. It is a planning assumption that should be reviewed as your circumstances and actual spending change.
How Early Is “Early”?
The age at which you want work to become optional matters enormously.
Leaving work at 45 is financially different from leaving at 60. Your portfolio may need to support you for much longer, and you may have fewer years of employment income and contributions before withdrawals begin.
This is also why a FIRE number should not be copied from somebody else’s journey. Their age, spending, housing situation, family responsibilities and expected income may be completely different from yours.
The question is not simply whether you can reach a particular corpus. It is whether that corpus can support the period of life you are asking it to fund.
What Assets Should Count Towards Your FIRE Number?
Start by listing the financial assets that are genuinely available for your financial-independence plan.
- Bank savings and deposits
- Mutual funds
- Stocks and other market-linked investments
- PPF and other long-term savings
- EPF, where the money will actually be available for your intended plan
- NPS, subject to the applicable withdrawal and exit rules
- Other assets that you genuinely intend to use to fund financial independence
Be careful with assets that have value but cannot realistically fund your planned lifestyle. Your primary home, for example, may be a substantial asset, but it does not automatically provide spendable retirement income unless you intend to sell it, downsize or otherwise use its value.
The useful distinction is between wealth you own and wealth that can actually fund the life you are planning.
Your Savings Rate Matters as Much as Your Target
Once you know what you are trying to build, look at how quickly you are currently building it.
A simple starting point is:
Annual savings rate = annual savings ÷ annual income
For example, if take-home income is ₹18 lakh and annual savings are ₹6 lakh, the savings rate is about 33%.
A higher sustainable savings rate can bring financial independence closer. But there is an important word in that sentence: sustainable.
Saving so aggressively that you resent your present life, avoid reasonable experiences or repeatedly abandon the plan is not necessarily a better FIRE strategy. The point of financial independence is to create choices, not to postpone living indefinitely.
Investment Growth Helps — But Don’t Turn It Into a Promise
Your FIRE corpus can grow through both new contributions and investment returns.
A basic compound-growth formula can help explain the mechanics:
Future value = P × (1 + r)n
But actual portfolios do not grow at a fixed rate every year. Contributions happen at different times, markets rise and fall, taxes and costs affect outcomes, and the return sequence matters particularly once you begin withdrawing.
So use return assumptions to explore scenarios, not to manufacture certainty.
A Simple Example
Suppose someone is currently spending ₹10 lakh a year and wants financial independence.
The basic 25X calculation gives:
₹10 lakh × 25 = ₹2.5 crore
That is a useful starting point. It is not yet a complete FIRE plan.
If financial independence is still 15 years away, the spending figure needs to be considered in future terms. The person also needs to look at the corpus already accumulated, future savings, investment strategy, healthcare, taxes, family responsibilities and how long the portfolio may need to support them.
That is why a good FIRE calculation should end with questions, not just a number.
GreySmiles Take
A FIRE number is useful when it helps you understand what needs to change. It becomes less useful when it turns into a score you feel compelled to hit at any cost.
The number should serve the life you want to create — not become the reason you stop enjoying the life you have.
Use the GreySmiles Retirement Corpus Calculator as a Second Check
Once you have worked out your expected spending and retirement timing, you can use the GreySmiles Retirement Corpus Calculator to explore how current expenses, retirement age, inflation and expected return affect a broader retirement-corpus estimate.
It is not a dedicated FIRE calculator, so don’t treat its result as a FIRE verdict. Use it as another way of testing your assumptions.
GREYSMILES CALCULATOR
Calculate Your Retirement Corpus
Explore how your current spending, retirement age, inflation and expected return affect the corpus you may need.
Reaching the Number Is Not the End
There is an important second stage that is easy to overlook.
Once work becomes optional and you start using the portfolio, the question changes from “How fast can I build this?” to “How do I make this money last?”
That means thinking about withdrawals, inflation, market falls and how much spending can be adjusted when circumstances change.
The GreySmiles SWP Sustainability Calculator can help you explore this next-stage question. It is particularly useful for seeing how a planned withdrawal may behave over a selected period under different assumptions.
What Can Move Your FIRE Number?
Your FIRE number is not permanent. It can move in either direction as your life changes.
| Change | Possible effect |
|---|---|
| Higher lifestyle spending | Raises the amount your portfolio needs to support. |
| Working longer | Can provide more time to save and fewer years for the portfolio to fund. |
| Dependable income | Can reduce the amount that investments need to provide. |
| Housing changes | A paid-off home, rent, downsizing or relocation can materially change spending. |
| Family responsibilities | Continuing support for children or parents can increase the required financial cushion. |
| Healthcare | Insurance, out-of-pocket costs and changing healthcare needs can alter the amount required. |
Don’t Turn FIRE Into a Spreadsheet Competition
There is a temptation to keep moving the target. First it is ₹2 crore. Then ₹3 crore. Then perhaps ₹5 crore because someone online says that is the “safe” number.
There is an equally unhelpful temptation to do the opposite: find the smallest possible number and convince yourself that it is enough.
Neither approach is particularly useful.
A sensible FIRE plan should help you answer three practical questions:
- What kind of life do I want to fund?
- When could my finances realistically support it?
- What happens if my assumptions are wrong?
The last question matters. Markets can disappoint. Expenses can rise. Family circumstances can change. You may also discover that you do not actually want to stop working completely.
Financial independence gives you the freedom to change the answer.
FIRE Does Not Have to Mean Never Working Again
Financial independence and early retirement are related, but they are not identical.
You may reach a point where you can leave a demanding corporate job but still want to consult. You may move to part-time work, build a small business, volunteer, teach, travel for part of the year or simply work because you enjoy the work.
That matters because even modest income can change the amount your investment portfolio needs to provide.
The goal is not necessarily to stop all work as early as possible. It is to create enough financial resilience that you have more control over what you do next.
Frequently Asked Questions
What is the 25X rule?
It is a common FIRE planning heuristic that multiplies expected annual spending by 25 to create an initial corpus target. It is a starting point, not a guarantee that the money will last for a particular retirement.
Is 25X enough to retire early in India?
It may be a useful starting point, but there is no universal multiple that guarantees a successful early retirement. The earlier you retire, the longer the portfolio may need to support you, which makes the assumptions around spending, inflation, investment risk and withdrawals particularly important.
Should EPF and NPS count towards my FIRE number?
They may form part of the plan, but only to the extent that the money will actually be available to support your financial-independence goal when you need it. Applicable withdrawal and exit rules matter.
Can my FIRE number change?
Yes. Your spending, retirement age, housing, family responsibilities, healthcare needs and other income sources can all change. Your FIRE number should therefore be reviewed rather than treated as a permanent target.
Further Reading
- Retirement Corpus Calculation: How Much Do You Really Need?
- How Much Will I Actually Need to Spend in Retirement?
- GreySmiles Retirement Readiness Test
- Should You Rely Only on EPF for Your Retirement Corpus?
This article is for general educational purposes and does not constitute personalised financial, investment or tax advice. FIRE calculations depend on assumptions that can change, and investment returns are not guaranteed.


Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.