By Kartikey Gupta: Kartikey Gupta is a finance professional with 6+ years of experience across capital markets, insurance and financial services. He is a CMT and CFA Level II qualified professional and writes on retirement planning, investing and financial security.
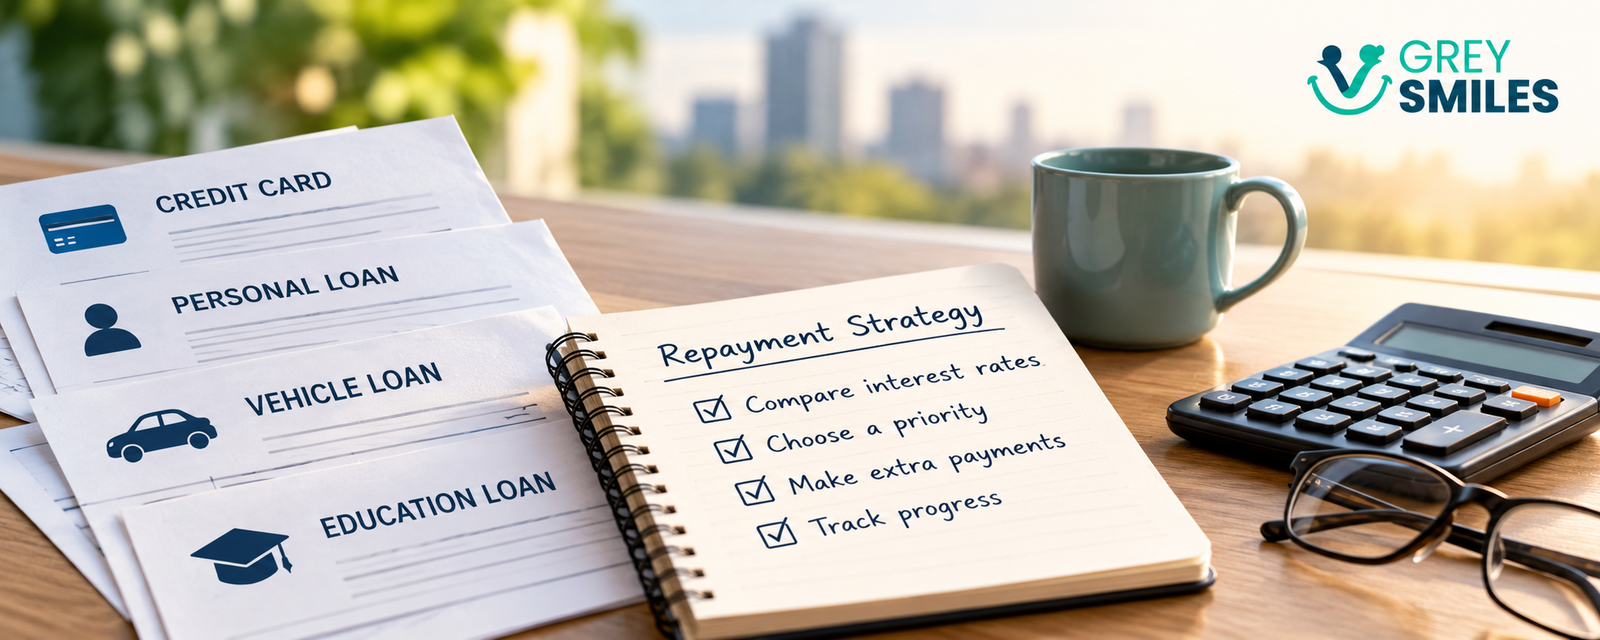
When you have more than one loan, deciding which one to repay first can be surprisingly difficult. Should you close the smallest loan to free up an EMI, focus on the loan with the highest interest rate, or use surplus money to reduce a home loan?
The right approach depends on each loan’s cost, your monthly cash flow, repayment terms and the amount you need to keep accessible. This becomes particularly important in your 50s, when repayments may compete with retirement savings and other financial priorities.
This guide compares two widely used strategies—the debt avalanche and debt snowball—and explains how to adapt them to common borrowing situations in India.
At a Glance
- Debt avalanche: Prioritise the loan with the highest interest rate after meeting all required EMIs.
- Debt snowball: Prioritise the smallest outstanding balance to build momentum and potentially free up an EMI sooner.
- Credit-card balances: Revolving balances can be expensive, so examine them carefully.
- Home loans: Compare interest cost, prepayment terms and the impact on liquidity rather than automatically prioritising them.
- Before extra repayments: Keep an emergency reserve and understand applicable prepayment charges.
- Approaching retirement: Consider the effect on monthly cash flow and future savings.
1. Start by Listing Every Loan
Before choosing a repayment strategy, establish exactly what you owe. It is easy to focus on the largest outstanding loan while overlooking a smaller loan with a much higher interest rate.
For every loan, record the outstanding principal, interest rate, EMI, remaining tenure and any conditions or charges that apply to early repayment. Also note whether the rate is fixed or floating and whether the lender permits part-prepayment or foreclosure.
| Loan | Outstanding | Interest rate | Monthly EMI |
|---|---|---|---|
| Credit card | ₹60,000 | Check card terms | Varies |
| Personal loan | ₹2,00,000 | Check loan terms | As scheduled |
| Home loan | ₹15,00,000 | Check current rate | As scheduled |
The balances above are illustrative, not market averages. Use your actual loan statements and current interest rates.
Separate required EMIs from the additional amount you can afford to repay. Both strategies below assume that you continue making all required payments on time.
2. The Debt Avalanche Method: Focus on the Highest Interest Rate
Under the debt avalanche method, make the required payment on every loan and direct available extra money towards the loan with the highest interest rate. When it is repaid, redirect the freed-up payment towards the next-highest-rate loan.
All else being equal, reducing the balance of a more expensive loan first can lower the total interest you pay. This makes the avalanche method a useful starting point when your primary objective is to minimise borrowing costs.
How it works
- Pay the required EMI or minimum amount due on every loan.
- Identify the loan with the highest effective borrowing cost.
- Put available extra repayment towards that loan, subject to the lender’s terms.
- When it is cleared, redirect the amount towards the next-highest-cost loan.
- Continue until the remaining loans are repaid or your plan changes.
If you have a credit-card balance, a personal loan and a home loan, and the card has the highest effective interest cost, the avalanche approach would generally direct extra repayments there first while keeping the other loans current.
Credit-card interest can accumulate quickly when balances revolve. The Reserve Bank of India has cautioned consumers about the consequences of paying only the minimum amount due. Understand your outstanding balance, applicable charges and the payment needed to stop further revolving debt.
Who may benefit from the avalanche method?
This method may suit borrowers who want to focus on interest savings and can follow a longer-term plan. However, the highest stated interest rate is not the only consideration. Check fees, prepayment restrictions, relevant tax implications and whether the extra payment will reduce principal.
3. The Debt Snowball Method: Clear the Smallest Balance First
The debt snowball method directs extra money towards the loan with the smallest outstanding balance, regardless of whether it has the highest interest rate. Continue making required payments on all loans.
Once the smallest loan is cleared, add the amount previously allocated to it to the extra payment on the next-smallest loan. As each debt disappears, the amount available for the next repayment can grow.
Why it can work
Eliminating a loan quickly provides a visible result for some borrowers and may make the plan easier to sustain. For example, if a vehicle loan has ₹45,000 outstanding and a personal loan has ₹2 lakh outstanding, the snowball method would generally prioritise the vehicle loan even if the personal loan has a higher rate.
The trade-off is that snowball can cost more in interest when more expensive debt remains outstanding for longer. Its value lies in the possibility of making the plan easier to follow—not in a guarantee that it is cheaper.
Who may benefit from the snowball method?
It may suit someone who feels overwhelmed by several loans, needs early milestones to maintain motivation or wants to simplify monthly payments. Compare the likely interest cost of delaying repayment on more expensive debt before choosing it.
4. Debt Avalanche vs Debt Snowball: Which Is Better?
| Consideration | Avalanche | Snowball |
|---|---|---|
| First priority | Highest interest rate | Smallest outstanding balance |
| Main objective | Reduce borrowing costs | Create early progress and momentum |
| Potential advantage | Can reduce total interest, all else equal | Can simplify repayments sooner |
| Potential drawback | The first loan may take longer to clear | More interest may accrue on expensive debt |
Neither method is universally right. If interest-rate differences are substantial, avalanche may have a clear financial advantage. If a small loan can be cleared quickly and that progress helps you stick to the plan, snowball may be more practical.
Avoid missing scheduled payments on other loans to fund the priority repayment. Late-payment charges, additional interest and potential effects on your credit history can undermine the benefit.
5. Which Loans Should You Prioritise in India?
The avalanche and snowball methods provide a framework, but real borrowing decisions require a closer look at loan terms.
Credit-card balances
Revolving credit-card debt that is accruing interest often deserves urgent attention because its borrowing cost can be high. Focus on the total outstanding balance rather than treating the minimum amount due as a repayment plan. If you cannot pay the full balance, contact the issuer to understand available options and costs.
Credit utilisation and repayment history can affect your credit profile. Paying down a balance may improve utilisation, but no specific increase in your credit score is guaranteed.
Personal loans
Personal loans can have relatively high interest costs, but the actual rate depends on the lender, borrower and product. Compare the rate and any foreclosure or part-payment charges before directing a large extra payment towards the loan.
If considering a new loan to consolidate existing debts, compare the total cost, fees and repayment period. A lower EMI does not necessarily mean a lower overall cost if the tenure is extended considerably.
Vehicle loans
Consider the outstanding principal, remaining tenure, EMI and applicable prepayment terms. A loan close to completion may not be the best target for a large lump sum if another loan is substantially more expensive.
Education loans
Education loans may have course-period or moratorium provisions, and interest treatment varies by scheme. Review the lender’s repayment schedule and terms before deciding how to prioritise it against other debts.
Home loans
A home loan should not automatically be placed first or last. Compare its current interest rate, remaining tenure, EMI and prepayment terms with those of other loans. Consider any tax implications applicable to your circumstances and whether prepayment would leave sufficient accessible savings.
For people nearing retirement, can the EMI be comfortably supported by expected retirement income? Our guide to whether you can retire with outstanding debt explores the broader question, including the trade-off between becoming debt-free and retaining enough retirement savings.
6. Should You Make Extra Loan Repayments or Build Savings First?
Extra repayments can reduce interest costs, but money used to repay a loan is no longer available for emergencies. Before committing surplus cash, maintain an appropriate emergency reserve and account for near-term expenses, insurance premiums and other essential commitments.
This matters particularly for households approaching retirement. A large repayment may remove an EMI but leave too little readily available money for healthcare, home repairs or an unexpected loss of income.
If reviewing your wider finances, GreySmiles’ guide to money management for retirees in India provides broader context on managing expenses and resources after work.
7. Is a Lump-Sum Prepayment Better Than Small Extra Payments?
A lump-sum part-prepayment can reduce outstanding principal immediately, subject to how and when the lender credits it. Smaller additional payments may also reduce principal over time, but the outcome depends on timing, the loan’s interest calculation and lender processing rules.
For a home loan, ask the lender whether a part-prepayment reduces the EMI, shortens the tenure or gives you a choice. If your aim is to reduce total interest, a shorter tenure may produce a different result from a lower EMI.
Do not assume every loan can be prepaid free of charge. Charges and restrictions depend on loan category, lender, purpose, contract and applicable rules. Check your agreement and obtain a current foreclosure or part-prepayment statement before deciding.
Distinguish between paying extra towards principal and merely advancing an instalment. Ask the lender to confirm how the payment will be applied and request an updated repayment schedule.
8. How to Choose a Repayment Strategy When You Are Over 50
In your 50s, debt repayment may compete with building your retirement corpus, funding healthcare, supporting family members and retaining liquidity. The best strategy is one that fits these obligations rather than treating debt elimination as the only objective.
Identify the costliest debt and the surplus cash you can consistently direct towards repayments. Estimate how long the plan may take and how much accessible savings will remain. If unsure whether your overall plan is on track, the GreySmiles Retirement Readiness Test can help assess broader areas of retirement preparedness.
Revisit expected retirement expenses using our guide to how much you may need to spend in retirement and assess the corpus required through the retirement corpus calculation guide.
These checks help ensure that extra loan repayments do not unintentionally compromise longer-term financial security.
9. A Practical Checklist Before You Make an Extra Repayment
- Have I listed the current outstanding balance and interest rate for every loan?
- Am I keeping all required EMIs and minimum payments up to date?
- Have I checked prepayment terms and applicable charges?
- Will the extra payment reduce principal, and how will the lender apply it?
- Will I retain an adequate emergency reserve after repayment?
- Have I compared avalanche and snowball against my actual loans?
- If retirement is approaching, have I considered the effect on my corpus and monthly cash flow?
- Have I avoided taking on new expensive debt to fund an extra repayment?
The GreySmiles Take
The debt avalanche and snowball methods solve the same problem in different ways. Avalanche focuses on reducing borrowing costs; snowball focuses on clearing smaller balances and building momentum. Start with the actual terms of your loans, keep required payments current and protect your emergency savings. If retirement is approaching, assess every extra repayment against the income and liquidity you will need in the years ahead. The goal is not simply to clear loans as quickly as possible. It is to build a more resilient financial position.
Frequently Asked Questions
Which loan should I repay first?
After keeping required payments current, avalanche directs extra money towards the highest-interest loan, while snowball targets the smallest balance. Compare the actual costs and your ability to sustain each approach.
Is the debt avalanche method always better?
It can reduce total interest compared with snowball when other conditions are comparable. Fees, loan terms and repayment behaviour can affect the outcome. A theoretical low-cost strategy is useful only if you can follow it consistently.
Should I repay my credit card before my home loan?
If the credit-card balance is revolving at a much higher effective interest rate, prioritising it will often make financial sense. Continue meeting the home-loan EMI and check both facilities’ terms.
Should I close a small loan even if another loan has a higher interest rate?
That is the trade-off between snowball and avalanche. Clearing the small loan may free up a payment and provide motivation, but delaying repayment of higher-cost debt can increase interest. Compare both outcomes using your actual figures.
Should I use my savings to repay a loan early?
Only after considering interest saved, applicable charges, your emergency reserve and upcoming expenses. Using all available savings to repay debt can leave you exposed to an unexpected expense and force you to borrow again.
Should I prioritise debt repayment over retirement investing?
There is no universal answer. Compare the loan’s effective cost with your broader goals, recognising that investment returns are uncertain and loan interest is a contractual cost. Preserve sufficient liquidity and consider your retirement timeline.
Important note: This article is for financial education and general information. It is not individual investment, tax or legal advice. Loan interest rates, repayment rules, tax treatment and prepayment charges vary by product and lender. Verify current loan terms and consider qualified professional advice before making a major financial decision.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.