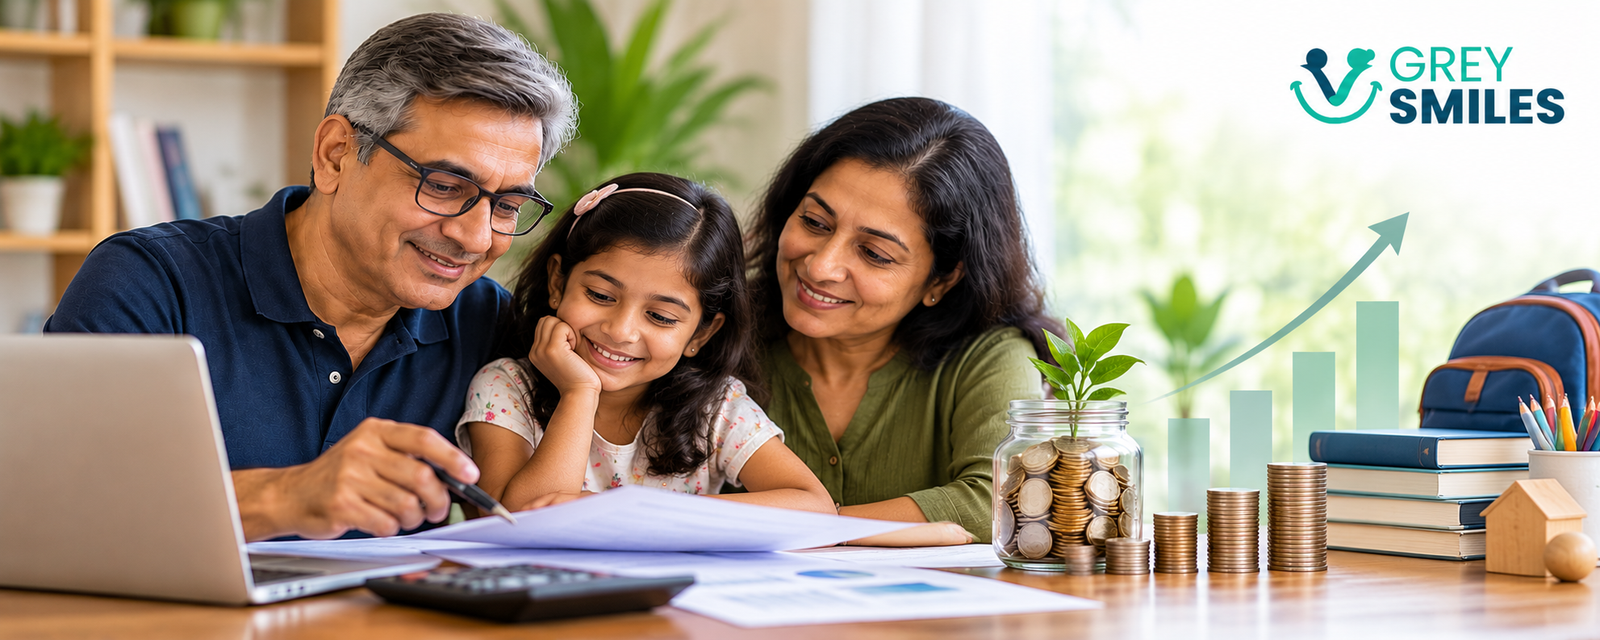
Planning investments for a child can help build a financial foundation for future needs.
For many parents in India, planning for a child’s future starts with a simple concern: how will we meet the large expenses that are likely to come several years from now? Education, in particular, can require substantial savings when the time finally arrives.
Mutual funds can be one way of building a long-term corpus for such goals. Parents can invest through a Systematic Investment Plan (SIP) or make lump-sum investments, depending on their circumstances, time horizon and comfort with investment risk.
This article looks at the idea of child care gift plans through mutual funds, what parents should understand before investing, and the factors that matter when money is being set aside for a child’s future.
At a Glance
- There is no single mutual fund category called a “child care gift plan”. Parents can use different types of mutual funds to build savings for a child’s future goals.
- The goal should come first. Education, higher studies and other future expenses may have different time horizons and therefore require different approaches.
- SIPs can bring discipline. Investing a fixed amount regularly can make long-term saving easier, although it does not remove market risk.
- Mutual funds are market-linked investments. Returns are not guaranteed, and the value of an investment can rise or fall.
- Investing in a child’s name has specific rules. A minor’s mutual fund investment is held in the minor’s name and operated by a parent or legal guardian until the child attains majority.
- Tax treatment depends on the investment and applicable rules. Parents should consider taxation before choosing a fund or investment structure rather than assuming that every child-oriented investment receives a special tax benefit.
Understanding Child Care Gift Plans
The phrase “child care gift plans” can sound as though there is a single, standard mutual fund product designed specifically for children. In practice, parents may use different mutual fund schemes to build a corpus for a child’s future needs.
The objective is usually to invest over a reasonably long period and build money for a defined future goal. That goal could be higher education, a professional course, a significant milestone or another expense the family expects to meet when the child is older.
Some mutual fund houses may offer schemes with “children”, “education” or similar names. However, the name of a fund does not by itself make it suitable for every child’s goal. The fund’s investment strategy, risk level, time horizon, costs and taxation all need to be understood before investing. Our guide to selecting mutual funds for child education goals looks more closely at the available approaches.
Why Start Investing Early for a Child?
Starting early gives parents more time to build a corpus. A longer investment period can also make it easier to spread investments over many years rather than trying to accumulate a large amount shortly before the money is needed.
For example, parents who begin planning when a child is young may have many years before higher education expenses arise. This gives them more time to save, review the investment and gradually adjust the strategy as the goal approaches.
Early investing, however, does not mean that returns are guaranteed. Mutual funds remain market-linked investments, and the actual outcome will depend on the scheme, market conditions, investment period and other factors.
GreySmiles Take
Start with the child’s future expense, not with the name of the investment product. Once you have an idea of what you are saving for and when the money may be needed, it becomes easier to think about the amount, time horizon and level of investment risk you can reasonably accept.
Benefits of Using Mutual Funds for a Child’s Future
1. Potential for Long-Term Wealth Accumulation
Mutual funds can provide exposure to different asset classes, including equity and debt. Over a sufficiently long period, equity-oriented investments may offer greater growth potential than traditional savings products, although they also carry greater market risk.
This makes the investment horizon particularly important. Money that will not be needed for many years may have more room to absorb market fluctuations than money required in the near future.
2. Professional Fund Management
Mutual funds are managed by professional fund managers who make investment decisions according to the scheme’s stated objective. For parents who do not want to select and manage individual securities themselves, this can make investing more convenient.
Professional management, however, does not eliminate investment risk. A fund manager cannot guarantee a particular return or prevent the value of a market-linked investment from falling.
3. Flexibility in Investing
Parents can invest through a SIP or make lump-sum investments depending on their financial circumstances. A SIP can be useful when the family wants to set aside a fixed amount from monthly income, while lump-sum investments may be relevant when there is a larger surplus available.
The contribution can also be reviewed as income, expenses and the child’s future needs change.
4. Goal-Oriented Saving
Giving the investment a specific purpose can make long-term saving easier to follow. Instead of simply accumulating money without a clear objective, parents can work towards a defined target such as higher education or another major future expense.
It is also useful to review the target periodically because the expected cost of education and other goals can change substantially over time.
Popular Ways to Use Mutual Funds for a Child’s Future
There is no single investment route that will suit every family. The appropriate choice depends on the time available, the financial goal and the level of investment risk the family can accept.
SIP in Mutual Funds
A SIP allows parents to invest a fixed amount at regular intervals. This can create a disciplined savings habit and spread investments across different market levels rather than relying on a single investment date.
A SIP does not guarantee profits or protect the investor from market declines. Its main benefit is the discipline it can bring to regular investing.
Equity-Oriented Mutual Funds
For goals that are many years away, equity-oriented mutual funds may be considered because they provide exposure to shares of companies and therefore have higher long-term growth potential than many lower-risk investments.
They also carry higher market risk. Parents should therefore avoid assuming that an equity fund will deliver a fixed return simply because the investment is being made for a long-term goal.
Debt-Oriented Mutual Funds
Debt mutual funds invest primarily in fixed-income securities. They may have a role in a child’s financial plan where the priority is relatively lower market volatility or where the goal is getting closer.
Debt funds are not the same as guaranteed-return products, however. They can also be affected by interest-rate movements, credit risk and other factors, and therefore should not be described as providing guaranteed capital protection.
Hybrid Mutual Funds
Hybrid funds combine equity and debt exposure within the same scheme. They may therefore be relevant for investors looking for a mix of growth potential and comparatively lower equity exposure than a pure equity fund.
The actual risk can vary considerably between different hybrid fund categories, so the scheme’s investment strategy needs to be understood before investing.
Investing in a Mutual Fund in a Child’s Name
Parents sometimes assume that investing in a child’s name is simply a way of creating a separate investment account. There are specific rules governing investments made for minors.
A mutual fund investment made in the name of a minor is held in the minor’s name and is operated by a parent or legal guardian until the child reaches majority. The relevant account and documentation requirements need to be completed with the mutual fund or registrar.
When the child turns 18, the account needs to be regularised in accordance with the applicable requirements. The child then becomes responsible for operating the investment as the major unit holder.
Parents should therefore think about the ownership structure before making the investment rather than treating the minor’s name simply as a label on the account.
How Much Might You Need for the Goal?
Before choosing a mutual fund, it can be useful to estimate the size of the future corpus you may need. Education costs, for example, can be very different depending on the course, institution, location and number of years before the expense arises.
The GreySmiles Corpus Calculator can help you explore how your target corpus changes when you change assumptions such as the amount available for investment, time period and expected growth.
GREYSMILES CALCULATOR
Start With the Corpus You May Need
Before deciding how much to invest every month, it can help to work backwards from the amount you may eventually need. The GreySmiles Corpus Calculator allows you to explore different assumptions and understand how the target corpus can change.
Use the result as a planning illustration, not as a prediction or a guaranteed investment outcome.
Key Considerations Before Investing
1. Investment Horizon
The first question should be when the money is likely to be needed. A goal that is 15 years away is very different from one that is only three years away.
The longer the time available, the more opportunity there may be to tolerate short-term market fluctuations. As the goal approaches, however, the priority may shift towards protecting the money already accumulated.
2. Risk Appetite
Different mutual funds carry different levels of risk. Parents should consider how comfortable they are with seeing the investment value fall temporarily, particularly when the money is earmarked for an important future expense.
The fact that the investment is for a child does not make the underlying fund less risky. The fund’s actual portfolio and investment strategy remain the key considerations.
3. Taxation
Tax treatment can vary depending on the type of mutual fund, the period for which the investment is held and the applicable tax rules. Parents should understand the tax implications of both investment and eventual redemption before choosing a fund.
It is also important not to assume that an investment marketed around a child’s future automatically receives a special tax benefit. The tax treatment depends on the applicable rules and the nature and ownership of the investment.
4. Regular Review
A child-related investment may run for many years, during which both family circumstances and financial goals can change. Review the investment periodically to check whether the amount being saved remains appropriate for the expected goal.
A review can also be useful as the goal approaches, particularly when the priority gradually moves from growing the corpus to protecting money that will soon be required.
5. Diversification
Putting all your savings for a child’s future into a single investment can create unnecessary concentration. Diversification across suitable investments may help spread risk, although diversification itself cannot eliminate market losses.
A Child’s Future Is a Goal, Not a Product
It is easy to start with the question, “Which mutual fund should I buy for my child?” A better starting point is to ask what the money is actually meant to achieve and when it will be needed.
Once the goal, time horizon and approximate corpus requirement are understood, parents can then consider the investment options that fit those requirements. This keeps the focus on the child’s future need rather than on a particular product or fund name.
For a more detailed look at mutual funds specifically for education goals, see GreySmiles’ guide to selecting mutual funds for child education goals. That article goes deeper into fund selection and the different investment approaches that may be considered.
GreySmiles Take
The best child investment is not necessarily the fund with the highest recent return. The more important questions are how much you may need, when you will need it, how much risk you can live with and whether the investment continues to fit the goal as the years pass.
Conclusion
Mutual funds can be one way for parents to build a financial corpus for a child’s future. Their flexibility, professional management and potential for long-term growth make them worth considering for suitable goals, particularly when the investment horizon is long enough to accommodate market fluctuations.
At the same time, there is no single “child care” mutual fund that is automatically appropriate for every family. Parents need to look at the goal, investment horizon, risk level, taxation and ownership structure before deciding how to invest.
Starting early can provide more time to build the required corpus, but the investment should be reviewed as the child gets older and the goal gets closer. The objective is not simply to accumulate money, but to have the right amount available when the child actually needs it.
Sources & References
For information on mutual fund investing and investor processes, refer to the Association of Mutual Funds in India (AMFI). For applicable tax provisions, refer to the Income Tax Department.
Mutual fund investments are subject to market risks. Tax rules and investment regulations can change, so the applicable provisions should be checked at the time of investment and redemption.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.