
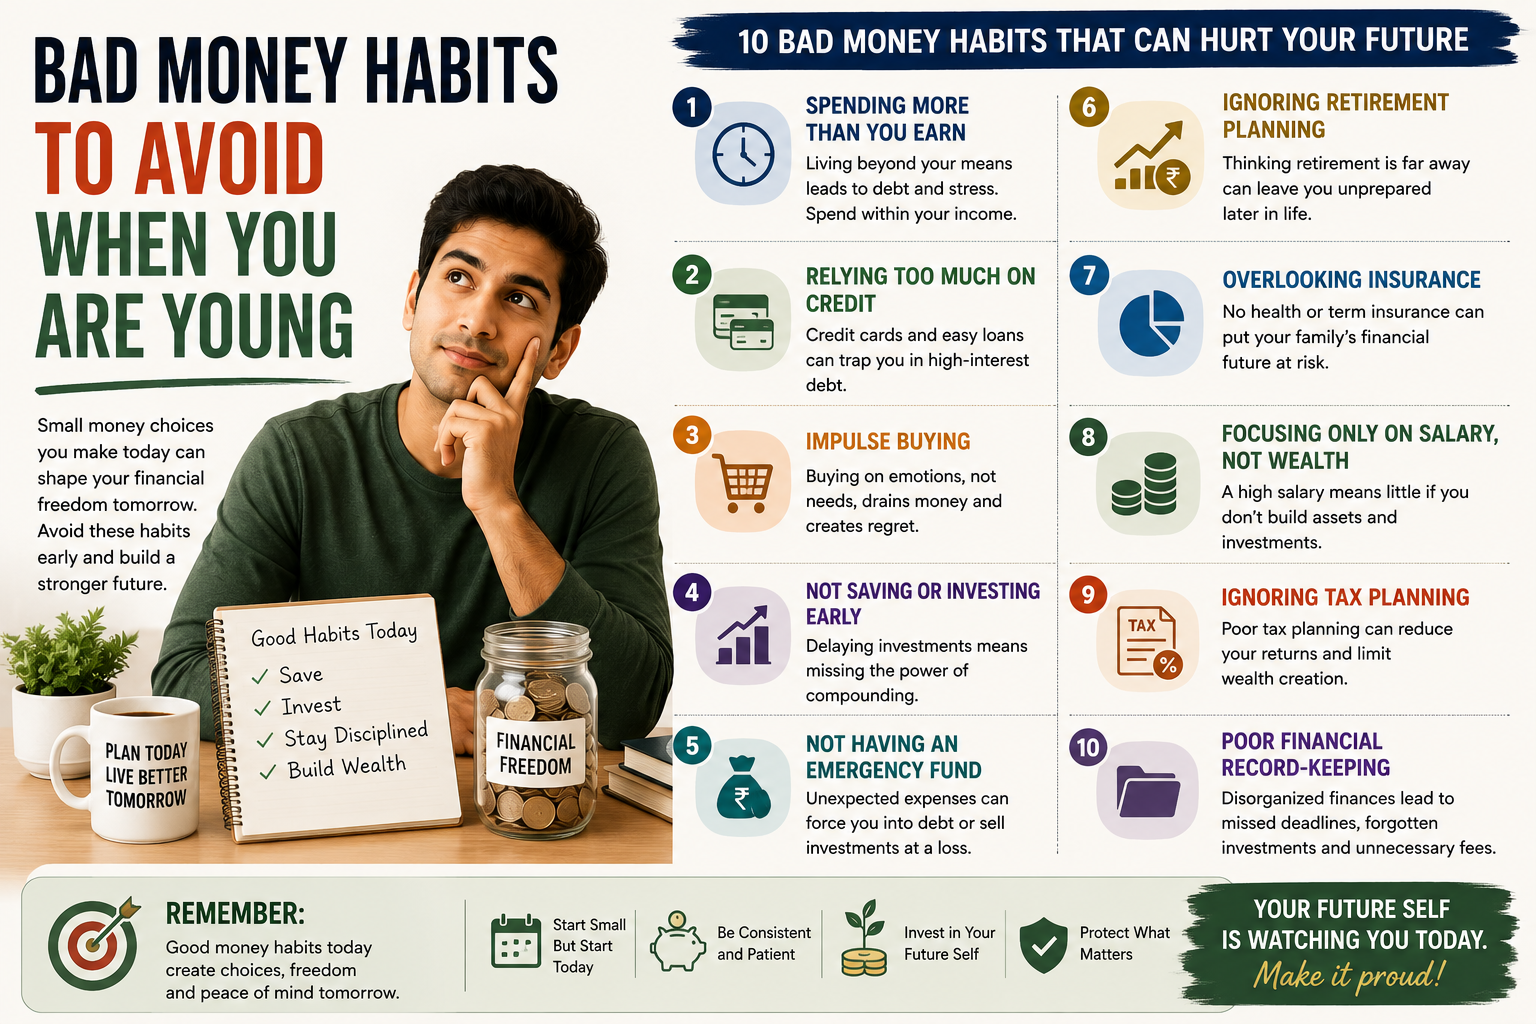
Building lasting wealth is not simply about choosing the right mutual fund, buying property or earning a higher salary. It is also about avoiding the financial decisions that quietly eat away at your future security.
For many Indian families, financial priorities compete constantly: home loans, children’s education, supporting parents, lifestyle expenses, insurance and unexpected medical costs. Retirement can easily become the goal that gets whatever is left over.
That is why it is worth looking at the mistakes that can derail retirement security—and the practical alternatives that can put you back on track.
In this guide: 10 financial mistakes | Practical steps | What to build towards | FAQs
10 Financial Mistakes That Can Derail Your Retirement
1. Delaying Saving and Investing
Why it hurts: Time is one of the biggest advantages an investor has. Every year of delay reduces the period available for compounding.
Better approach: Start with an amount you can sustain and automate it. SIPs, EPF/VPF, PPF and other suitable investments can help turn saving into a habit. Increase contributions as your income grows.
2. Living Without a Spending Plan
Why it hurts: Without a clear view of cash flow, lifestyle spending can expand quietly until there is little left for long-term goals.
Better approach: Track income, EMIs, household expenses, insurance, family commitments, savings and investments. You don’t need a complicated budget—just a realistic picture of where your money is going.
3. Carrying High-Interest Debt for Too Long
Why it hurts: Credit-card balances and expensive personal loans can erode wealth quickly. Paying high interest while trying to build investments can leave you running hard just to stand still.
Better approach: Prioritise high-interest debt using either the avalanche or snowball method, stop adding unnecessary balances and avoid borrowing for lifestyle purchases wherever possible.
4. Treating Retirement as the Money Left Over
Why it hurts: In many Indian households, retirement savings come after children’s education, home purchases, family obligations and lifestyle spending. That can leave too little time or money to build an adequate retirement corpus.
Better approach: Give retirement its own allocation from the beginning. EPF can provide an important foundation for salaried employees, while NPS, PPF and mutual funds may have roles depending on individual circumstances.
Your family’s needs matter—but your retirement needs to be funded alongside them, not only after them.
5. Putting Too Much Wealth Into One Asset
Why it hurts: A large exposure to one company, sector, property or asset class can make your financial future dependent on a single outcome.
Owning a home, for example, can provide security and long-term value, but it does not automatically provide the liquidity or regular income required during retirement.
Better approach: Diversify appropriately across equity, fixed income, gold and other suitable assets according to your goals, time horizon and risk tolerance.
6. Allowing Lifestyle Inflation to Consume Every Raise
Why it hurts: A higher salary can create the illusion of greater wealth while spending rises just as quickly.
Better approach: When your income increases, increase your savings and investments before upgrading your lifestyle. Enjoy your money, but don’t let every raise become a new recurring expense.
The goal isn’t to live like a retiree today. It’s to avoid becoming financially trapped tomorrow.
7. Having No Emergency Fund
Why it hurts: A job loss, medical expense, family emergency or major repair can force you to borrow or sell investments at the wrong time.
Better approach: Build around 3–6 months of essential expenses in reasonably liquid savings. Those with irregular income, dependants or a single household income may need more.
Your retirement portfolio should not be your emergency fund.
8. Ignoring the Tax Cost of Your Financial Decisions
Why it hurts: What matters is not the headline return but what remains after tax, costs and inflation.
Better approach: Understand the current tax treatment of investments such as equity mutual funds, debt investments, PPF, EPF and NPS before investing. Tax rules can change, so verify current provisions when making significant decisions.
9. Keeping Your Financial Records Disorganised
Why it hurts: As your financial life becomes more complicated, it is easy to lose track of investments, insurance policies, nominees, loans, bank accounts and important documents.
This can become particularly difficult for a spouse or family member who has to step in during an emergency.
Better approach: Maintain a secure record of your major financial assets and liabilities, including bank accounts, EPF, NPS, PPF, insurance, loans, property documents, nominees and important tax records.
Review these details annually and make sure your spouse knows where essential information is kept.
10. Avoiding Professional Advice When It Matters
Why it hurts: Some financial decisions become complicated when investments, taxation, insurance, property, inheritance and family structures overlap.
Better approach: Consider qualified professional advice around major milestones such as marriage, children, a home purchase, starting a business, receiving an inheritance, moving abroad or approaching retirement.
What You Can Do Now
You don’t need to fix everything at once. Start with five practical actions:
- Know your numbers: Calculate essential expenses, debt, investments and existing retirement savings.
- Automate saving: Make investments happen before discretionary spending.
- Create an emergency buffer: Aim for around 3–6 months of essential expenses.
- Separate financial goals: Don’t routinely raid retirement money for holidays, children’s education or lifestyle purchases.
- Review annually: Revisit investments, insurance, debt, savings and your retirement target at least once a year.
What Financial Security Should Look Like
You don’t need to have a perfect portfolio or a huge corpus immediately. What matters is steadily building the foundations that will give you choices later.
- Regular retirement contributions
- An emergency fund
- Adequate health insurance
- Term insurance where dependants need income protection
- Manageable debt
- Diversified investments
- Separate savings for major family goals
- A savings rate that increases as income grows
Also Read
Retirement Planning in Your 30s
Mutual Funds for Retirement: Complete Guide
Common Emotional Mistakes to Avoid With Your Retirement Fund
A New Era for Retirement: How Millennials and Gen Z Must Evolve Their Financial Planning
Frequently Asked Questions
What is the biggest financial mistake that can affect retirement?
There is no single mistake for everyone, but delaying retirement saving, carrying expensive debt and allowing lifestyle costs to rise faster than savings can have a significant long-term impact.
Is it too late to start planning for retirement?
It is rarely too late to improve your retirement position. The strategy may need to change depending on your age, existing savings, income and expected retirement date, but starting now is generally better than delaying further.
Should I prioritise children’s education over retirement?
Both goals matter, but retirement should not automatically be sacrificed for every family goal. Education may have multiple funding options; retirement income is much harder to replace once you stop working.
How much should I keep as an emergency fund?
A common starting point is around 3–6 months of essential expenses. Your appropriate amount may be higher if your income is irregular, you have dependants or your household relies primarily on one income.
How often should I review my financial plan?
An annual review is a useful minimum. You should also revisit it after major life events such as marriage, children, career changes, a major loan, inheritance or a change in your expected retirement age.
Final Thought
Financial security is rarely destroyed by one bad decision. More often, it is weakened by small decisions repeated for years—saving later, spending every raise, carrying expensive debt or assuming retirement will somehow take care of itself.
The good news is that the opposite is also true.
Small, consistent financial decisions can compound into something much more valuable than wealth: the freedom to choose how you want to live later in life.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.