At a Glance: Before the First Salary
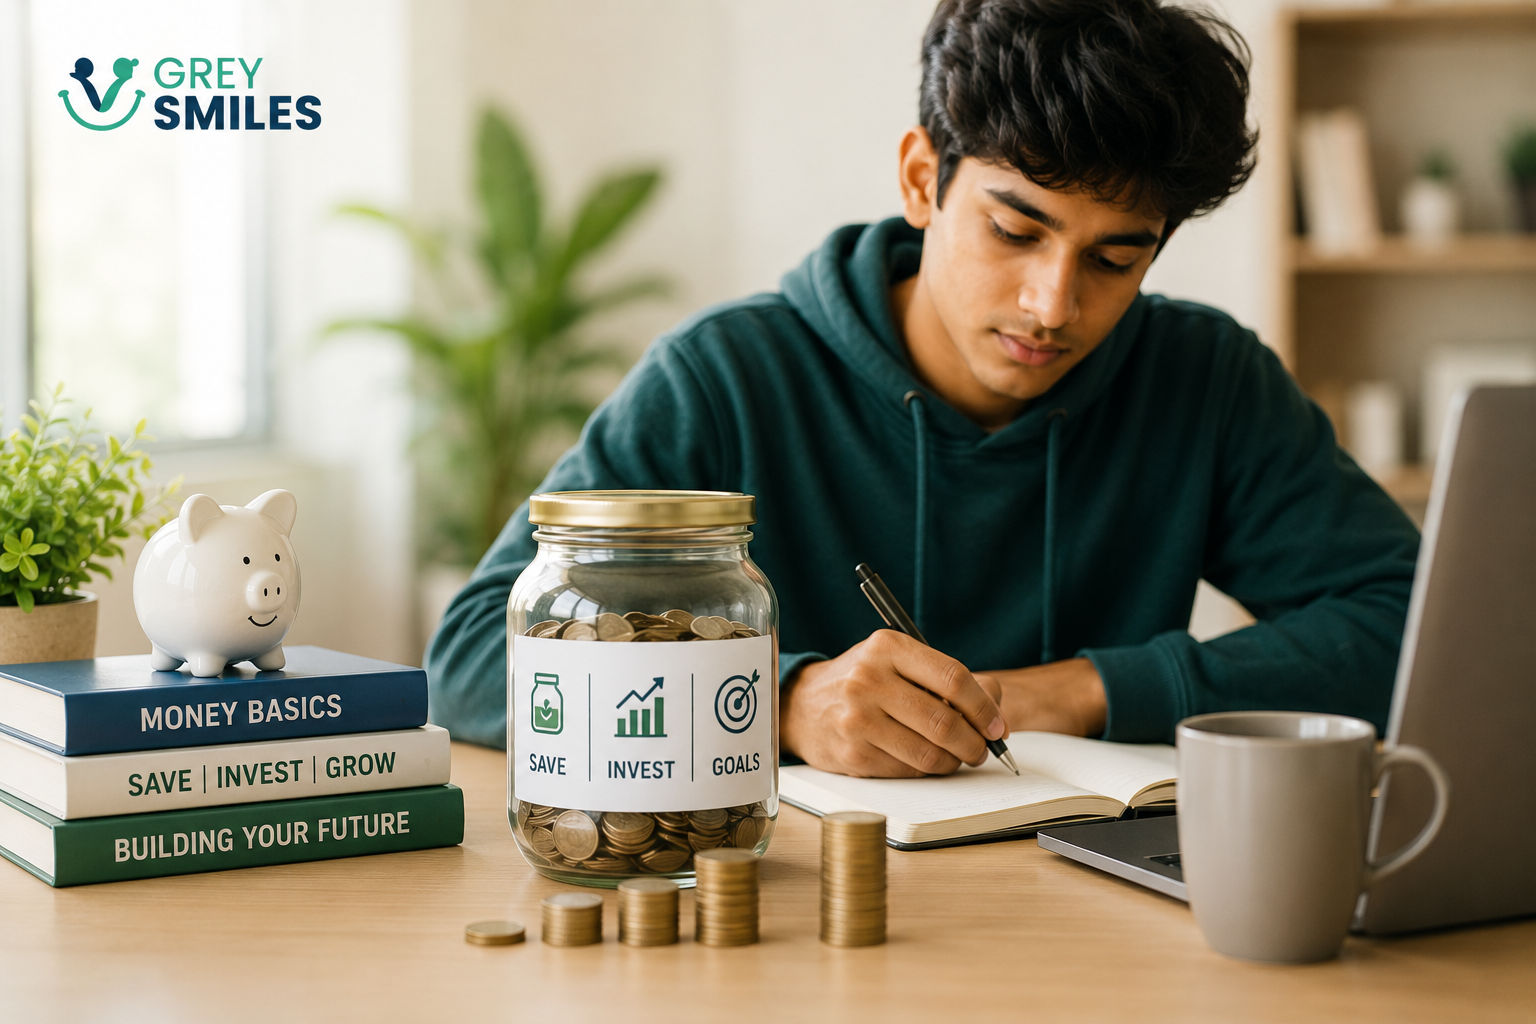
- Your first salary is not the beginning of your financial life. The money habits you develop before it can shape what happens afterwards.
- You don’t need to understand the stock market. Start with saving, spending, debt, interest, inflation, insurance and basic investing.
- Your first salary is an opportunity. Automating even a small amount of saving from the beginning can build a powerful habit.
- Learn before you borrow. Credit cards, EMIs and digital loans can make spending easy without making the cost obvious.
There is a moment in almost every young person’s life when money suddenly becomes very different.
The first salary arrives.
Until then, money may have meant pocket money, gifts, school expenses or asking parents for something you needed. Suddenly, there is an amount sitting in your own bank account.
It feels like freedom.
And it is.
But it is also the moment when a few basic money lessons can make a huge difference.
Don’t Wait for the First Salary to Learn
One mistake we make as a society is treating financial education as something that begins when people start earning.
By then, some of the most important decisions may already be happening.
A young person may already have a bank account, use UPI, shop online, take a subscription, use a credit card or consider an education or personal loan.
The better approach is to learn the basics before money becomes complicated.
Five Things Every Young Person Should Understand
1. Saving is not what is left over
If you spend first and save whatever remains, there may be very little left.
A better habit is to decide what you want to save first and then organise your spending around what remains.
It doesn’t have to be a large amount.
The habit matters before the amount does.
2. Understand where your money goes
A budget doesn’t have to be a complicated spreadsheet.
For a young person, simply tracking expenses for a month can be eye-opening.
Food deliveries. Subscriptions. Shopping. Transport. Entertainment. Small digital payments.
None of these is necessarily wrong. The point is to know what you are choosing to spend money on.
3. Learn what borrowing really costs
This is one lesson worth learning early.
An EMI can make something look affordable because the large price is divided into smaller monthly payments. But the total cost may be considerably higher once interest and other charges are included.
Before borrowing, ask two simple questions:
- How much will I repay in total?
- Do I actually need to borrow for this?
Understanding those two questions can prevent some very expensive mistakes.
4. Understand inflation and compounding
Two concepts deserve to become part of every young person’s financial vocabulary.
Inflation explains why ₹1,000 today won’t necessarily buy what ₹1,000 buys ten or twenty years from now.
Compounding explains why starting early can matter so much when money is invested for the long term.
You don’t need complicated mathematics to understand either idea. But you do need to understand what they mean for your future.
5. Learn about risk before learning about returns
The internet is full of people talking about returns.
Young investors are often shown what an investment could become after 10 or 20 years.
A more important question comes first:
What could I lose, and can I afford that risk?
Understanding risk, diversification and time horizon is more useful than chasing whatever investment happens to be popular this month.
What Should Happen When the First Salary Arrives?
There is no perfect formula. But a young person could consider dividing the first salary into a few simple buckets:
| Bucket | Purpose |
|---|---|
| Needs | Rent, food, transport and essential expenses. |
| Savings | Building an emergency cushion and future security. |
| Investing | Long-term wealth creation, once the basics are understood. |
| Enjoyment | Travel, eating out, hobbies and things that make life enjoyable. |
The exact percentages aren’t the point.
Learning to give every rupee a purpose is.
And Please Don’t Try to Become an Expert Overnight
A young person discovering investing today can be overwhelmed by information.
PE ratios. PEG ratios. RSI. Options. Futures. Crypto. Technical charts. “Hot stocks”. Influencers promising extraordinary returns.
There is plenty of time to learn more sophisticated concepts later.
Start with the fundamentals.
Read credible financial publications. Follow businesses you understand. Keep notes. Learn how companies make money. Take a good introductory course if structured learning suits you.
And when you don’t understand something, don’t pretend that you do.
That may be one of the most important financial habits of all.
A GreySmiles Thought for Young Readers
You don’t need to invest your first salary perfectly.
You don’t need to become wealthy at 22.
You don’t need to understand every financial product available.
You simply need to start learning before you start making big financial decisions.
The First Salary Is Just the Beginning
Your first salary will probably be exciting. You may buy something you’ve wanted for years. You may take your parents out. You may travel. You may finally feel financially independent.
Enjoy it.
But also save something from it. Learn something from it. And build one good financial habit around it.
Because the real value of the first salary isn’t just the amount that arrives in your account.
It is the beginning of your relationship with money.
Get that relationship right early, and you give yourself something far more valuable than a good first investment: decades in which your financial knowledge, habits and money can grow together.
Part of the GreySmiles Financial Literacy Series
Start with our cornerstone article: Financial Literacy in India: Why Children Should Learn About Money.
You can also read the personal story behind this series: I Was 16 When My Father Introduced Me to the Stock Market. Here’s What I Learned.
Disclaimer: This article is intended for general education and information. It is not personal financial, investment, tax or legal advice.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.