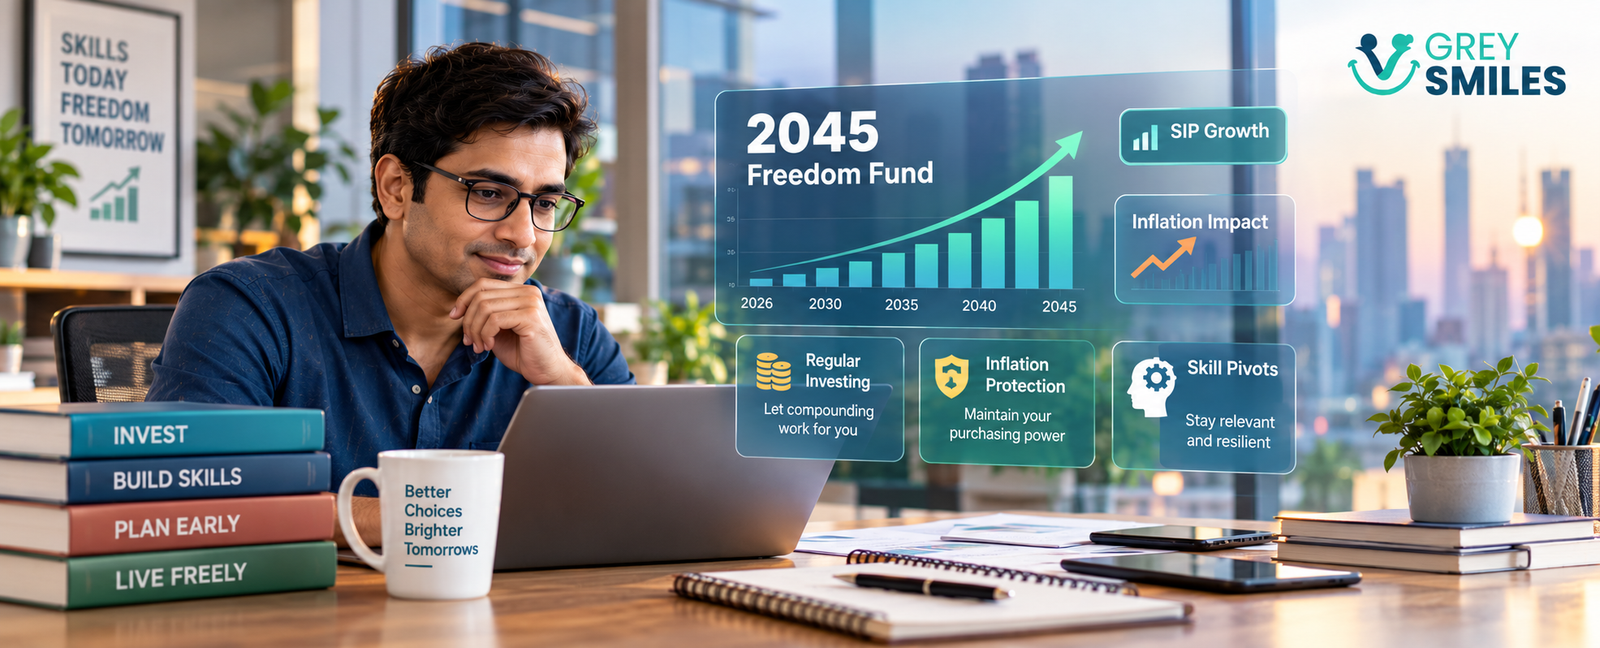
Building financial freedom through regular investing, inflation awareness and continuous skill development.
Forget the outdated image of a 60-year-old whose retirement begins only after a lifetime of work. For today’s young Indians, retirement planning can mean something much more immediate: building the financial freedom to choose how, where and when to work.
For people in their 20s and early 30s, time is one of the most valuable financial assets they have. Regular investing over a long period can allow compounding to work in their favour. At the same time, rising living costs, changing career paths and the impact of technology make it important to build financial resilience rather than depend on a single salary or a single source of income.
The traditional idea of working for decades and saving whatever remains at the end of each month is not the only approach. A better starting point is to treat saving and investing as planned expenses, protect against financial shocks and invest in the skills that can sustain future earning power.
At a Glance
- Start investing early so your money has more time to compound.
- Automate regular contributions instead of relying on leftover income.
- Account for inflation when estimating future expenses and retirement needs.
- Choose investments according to your time horizon, risk tolerance and financial goals, rather than chasing a fixed return.
- Build an emergency fund and keep investing in skills to manage career uncertainty.
1. The Subscription Trap: Your 20s Are the Beta Test
Today’s spending is increasingly built around recurring payments. Streaming platforms, gym memberships, app subscriptions, food delivery, premium services and vehicle payments can each look affordable on their own. Together, however, they can take a meaningful share of a young professional’s monthly income.
The problem is not that every subscription is wasteful. It is that small recurring expenses can become invisible. When they are deducted automatically, it is easy to underestimate how much money is committed before the month has properly begun.
The strategy: Pay your future self first
Think of retirement investing as a regular commitment to your future independence. It is not simply about giving up today’s pleasures. It is about making sure that today’s spending does not eliminate tomorrow’s choices.
For example, a regular systematic investment plan (SIP) in a mutual fund can help you build an investing habit. You can arrange the contribution around your salary date, after accounting for essential expenses, debt repayments and an adequate cash buffer.
Equity mutual funds can be considered for long-term goals, but they are not suitable for every investor or every time horizon. Small-cap and mid-cap funds can experience substantial volatility. They should not be selected simply because the objective is to grow wealth aggressively.
The practical move: Review the previous month’s discretionary spending. Identify one or two expenses you can reduce without making your lifestyle unnecessarily restrictive, and direct a manageable amount towards a long-term goal.
2. Inflation Is a Thief: Protect Your Future Purchasing Power
Money does not retain the same purchasing power indefinitely. The amount needed to pay for food, housing, transport, healthcare and other essentials may rise over time. A retirement plan that uses only today’s expenses can therefore underestimate future needs.
Cash in a savings account and fixed deposits can play important roles in emergency reserves and short-term goals. They provide liquidity or predictable interest arrangements, depending on the product. However, the return after tax and inflation may be insufficient to maintain purchasing power over a long period.
Equities, including diversified equity mutual funds, provide an opportunity to participate in business growth. They also carry market risk: values can fall, returns are not guaranteed, and periods of poor performance can last longer than investors expect.
Think in terms of real returns
The return shown on an investment is not the same as the increase in what you can afford to buy. Inflation and taxes affect the outcome.
For instance, if an investment earns 7% in a year and inflation is 5%, the approximate return after inflation is around 2% before tax and other costs. If the investment return is lower than inflation, its purchasing power declines.
This is why a retirement plan may need a mix of assets rather than relying entirely on cash, deposits or equities. The right allocation depends on the purpose of the money, when it will be needed and how much risk the investor can reasonably take.
There is no universal requirement for every investor to earn 12% a year. A return assumption is a planning input, not a promise. Building a financial plan around an ambitious number can lead to excessive risk-taking or an unrealistic estimate of the retirement corpus required.
To understand how future expenses and inflation affect the amount you may need, read the GreySmiles guide to retirement corpus calculation in India.
3. The Portfolio of One: Invest in Your Earning Power Too
For a young professional, financial assets are only one part of the picture. The ability to earn an income is also an important resource. Skills, experience, professional relationships and the ability to adapt to new technology can influence how well someone navigates changes in the job market.
Automation and artificial intelligence may alter the tasks performed in many occupations. The effects will differ across industries and roles, so it is difficult to predict exactly which skills will be in demand years from now. A sensible response is to keep learning rather than assume that today’s qualifications will always be sufficient.
Build two forms of resilience
The financial bucket: Build an emergency reserve and invest for long-term goals. The emergency reserve should remain accessible and should not depend on selling volatile investments at an inconvenient time.
The skills bucket: Set aside money for relevant training, certifications, professional development or a career transition. The appropriate amount depends on your field, existing skills and likely learning costs. You do not necessarily need a separate investment product; a clearly defined savings goal may be enough.
These two buckets serve different purposes. Money reserved for a course or a possible career break in the near term should not automatically be exposed to the same market risk as money intended for retirement decades away.
A financial cushion can give you more room to change jobs, retrain or explore a different career without making decisions under immediate financial pressure. That flexibility is part of financial independence too.
4. The First Paycheck Challenge: Start Before You Feel Ready
One of the biggest obstacles to investing is waiting for the perfect moment. Some people wait for a higher salary, while others believe they need a large initial amount before beginning. In practice, a manageable and consistent contribution can be a useful starting point.
Audit your leisure spending
Review your bank and card statements to understand what you spend on dining, delivery, subscriptions, shopping and entertainment. You do not need to eliminate these expenses. Instead, identify an amount that can be redirected towards saving or investing without compromising essential needs.
Automate a realistic contribution
Choose an amount you can maintain after accounting for essential bills, loan repayments and your emergency fund. Automating a contribution can reduce the temptation to postpone it each month.
If money is tight, start with a smaller amount and review it when your income or expenses change. Consistency matters, but so does keeping the plan affordable. Avoid borrowing or neglecting essential needs simply to maintain an investment contribution.
Increase contributions as income grows
When you receive a salary increase or bonus, consider directing a portion towards your long-term goals before allowing all of it to become additional spending. A step-up in contributions can help your investments keep pace with changing income and financial needs.
For example, you might review your SIP every year and increase it when your budget allows. The increase need not be a fixed percentage. The objective is to build a contribution level that reflects your evolving circumstances.
Do not ignore debt and emergency savings
Investing for retirement should not mean leaving yourself exposed to a sudden medical bill, job loss or urgent family expense. Build an accessible emergency reserve appropriate to your circumstances and pay attention to expensive debt, particularly balances that carry high interest rates.
A well-structured plan balances immediate financial stability with long-term growth. It should help you remain invested through difficult periods rather than force you to withdraw investments whenever an unexpected expense arises.
5. Turn Financial Independence into a Measurable Goal
Financial independence is easier to work towards when it is translated into numbers. Start with your present expenses, estimate how they may change over time and identify the age at which you would like to have greater freedom over your work choices.
Then review your existing savings, investments, expected contributions and other likely sources of income. Your target will depend on your lifestyle, family responsibilities, housing arrangements, health needs, inflation assumptions and the length of time your money may need to last.
Early retirement and conventional retirement may require different calculations. Someone who stops full-time work in their 40s may need to fund a much longer period without a salary than someone who works until their 60s. The plan should account for that difference rather than rely on a generic corpus multiple.
GreySmiles Calculators
Ready to put numbers behind your financial freedom goal? Explore the GreySmiles calculators to assess retirement-related needs and test different savings and planning assumptions. Use the results as illustrations, not as guaranteed investment outcomes.
If you are starting early, the GreySmiles retirement planning guide provides a useful next step. You can also explore the Retirement Readiness Test to reflect on your preparedness, keeping in mind that a readiness assessment and a numerical calculator serve different purposes.
The GreySmiles Take
Financial freedom is not about chasing the highest possible return or giving up every small pleasure. It is about creating choices. Start with manageable contributions, protect yourself against emergencies, invest according to your time horizon and keep building the skills that support your earning power. The earlier you begin, the more time you give yourself to learn, adjust and build a plan that fits your life.
Conclusion: Build Freedom, One Decision at a Time
For young Indians, retirement planning does not have to mean putting life on hold until a distant date. It can be a way to create more flexibility throughout life: the ability to change careers, take a break, learn a new skill or choose work for reasons beyond an immediate salary.
Start by understanding where your money goes. Build a reserve for emergencies, invest regularly for long-term goals and review your contributions as your circumstances change. Account for inflation, diversify sensibly and avoid assuming that any particular return is guaranteed.
Your first paycheck does not need to create wealth overnight. It needs to help establish habits that can grow with you. Over time, those habits can turn financial planning from an abstract idea into a practical route towards greater independence.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.