By Kartikey Gupta: Kartikey Gupta is a finance professional with 6+ years of experience across capital markets, insurance and financial services. He is a CMT and CFA Level II qualified professional and writes on retirement planning, investing and financial security.
At a Glance
- Partial withdrawal, normal exit and premature exit are different routes, each governed by specific conditions.
- At normal exit, the permitted lump-sum and annuity portions depend on the applicable NPS rules and the subscriber’s circumstances.
- Premature exit generally carries different conditions from normal exit.
- Smaller corpus amounts and death-related claims may be subject to special provisions.
- The amount you can withdraw is only one part of the decision. You also need to plan how the money will support your retirement expenses.
First, understand which NPS withdrawal applies to you
People often use the term “NPS withdrawal” to describe several different situations. The distinction matters because the rules for accessing money while continuing the account are not the same as those that apply when the subscriber exits NPS.
You may want to make a permitted partial withdrawal while continuing your investment. You may be approaching the normal exit point. You may need to leave NPS before the normal exit conditions are met. Alternatively, the account may need to be settled following the subscriber’s death.
Before making a decision, identify which situation applies to you and check the relevant conditions. Do not assume that a rule you read about someone else’s withdrawal will necessarily apply to your account.
If you are still deciding where NPS fits alongside your other retirement savings, start with our guide to NPS vs PPF vs EPF and which to prioritise. It provides the wider context for understanding the role each option can play in your retirement plan.
Can you make a partial withdrawal from NPS?
Yes, partial withdrawals from Tier I are permitted under specified conditions. They are not the same as closing the account or withdrawing the entire retirement corpus at exit.
NPS is designed primarily to support retirement, so access to the accumulated money before exit is governed by the applicable regulations. Eligibility, permitted purposes, limits and procedural requirements matter. Having a substantial balance in the account does not automatically mean you can withdraw any amount whenever you wish.
If you are considering a partial withdrawal, first check whether your reason qualifies under the current rules. Confirm the permitted amount, any applicable waiting period, the number of withdrawals allowed and the documentation required. These details should be verified against the latest official guidance rather than an older article or an informal summary.
It is also worth asking whether you genuinely need to use retirement savings. A medical expense, family obligation or other unexpected cost can put pressure on household finances. Where possible, a separate emergency reserve can help you meet such needs without disturbing a long-term retirement arrangement.
For this reason, NPS should be considered alongside your wider savings and investment choices, rather than treated as the only pool of money available for every financial need.
What happens when you reach normal exit?
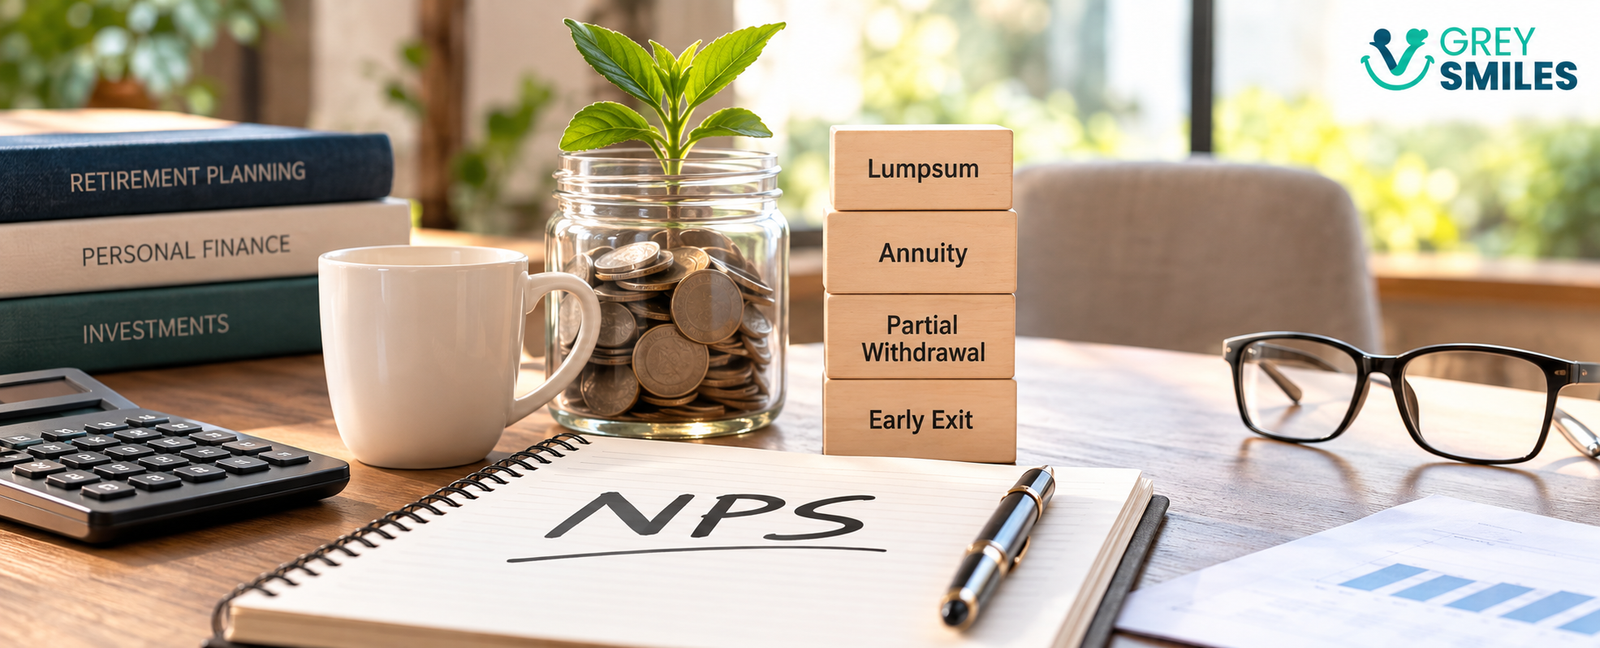
Normal exit is the point at which the subscriber leaves NPS under the applicable normal exit conditions. The treatment of the accumulated pension wealth determines how much may be received as a lump sum and how much, if any, must be used to purchase an annuity.
Under the current All Citizen Model framework, normal exit can permit up to 80% of the corpus as a lump sum, with at least 20% used for annuity, subject to the applicable rules and special provisions. The precise options available should be confirmed under the latest regulations when you are preparing to exit.
This is an important distinction from older explanations that present a blanket 60:40 split as if it applies in every situation. NPS exit provisions have changed over time, and the applicable treatment can depend on the subscriber’s circumstances and corpus size.
The practical point is that your NPS balance does not automatically become a monthly pension. A lump-sum withdrawal gives you access to capital, while an annuity is intended to provide income under the terms of the chosen product. Each serves a different purpose.
Before deciding how much money you need immediately, estimate your retirement expenses and identify the income you can expect from other sources. You may have EPF proceeds, rental income, a pension, interest income or investments outside NPS. The decision should take these resources into account rather than being based on the NPS withdrawal percentage alone.
What if you want to exit NPS early?
Premature exit is different from normal exit and generally carries more restrictive conditions. The permitted lump-sum and annuity portions can differ, and the applicable rules depend on the circumstances of the exit.
This is why NPS should not be used as a substitute for an emergency fund. Money you may need in the near future should not be committed to a retirement structure on the assumption that it will be freely accessible whenever required.
If you are considering leaving NPS early, check the current exit conditions before submitting a request. Understand the amount that may be available to you, the portion that may need to be used for an annuity and any special provisions that could apply.
It is equally important to understand why you want to exit. A temporary cash-flow problem may call for a different response from a permanent change in your employment or retirement plans. Where appropriate, consider the alternatives before making an irreversible financial decision.
What if your NPS corpus is small?
The rules include special provisions for certain smaller accumulated corpus amounts. The treatment of a relatively small balance may therefore differ from the standard exit route used for a larger retirement corpus.
Do not rely on a threshold remembered from an older article. Check the current PFRDA regulations and the applicable NPS guidance for the exact corpus band, exit category and options available to you.
The wider retirement question remains the same even when the balance is small: will the money be needed immediately, or can it contribute to income over time? Your answer will depend on your other savings, regular expenses and available sources of support.
What happens to NPS when the subscriber dies?
Death-related claims are governed by provisions that differ from those for a subscriber voluntarily leaving NPS. The treatment of the accumulated pension wealth depends on the applicable rules and the circumstances of the claim.
Nomination is therefore more than an administrative formality. It is part of making sure that your financial arrangements are organised and that the people who may need to deal with your affairs know where to find the relevant information.
Review your nomination details periodically, particularly after important family changes. Keep account information and essential documents organised, and make sure the appropriate family member knows how to locate them. Nomination and legal succession are not necessarily interchangeable, so seek appropriate guidance if your family circumstances or estate arrangements are complex.
Will your NPS withdrawal be tax-free?
The amount you are permitted to withdraw under NPS rules and the amount that receives favourable tax treatment are two different questions. Do not assume that the entire amount you receive will automatically be tax-free simply because the withdrawal is allowed under the pension regulations.
Tax treatment can depend on the nature of the payment, the applicable provisions of the Income-tax Act and the rules in force when the withdrawal takes place. Annuity income also needs to be considered separately from the initial amount used to purchase the annuity.
Before submitting an exit request, confirm the current tax treatment of the lump sum, annuity purchase and subsequent pension income. If the amount is significant, a tax professional can help you understand how the withdrawal will affect your wider tax position.
Our article on how pension income is taxed in India provides a useful starting point for understanding the income side of retirement. Always verify current tax provisions before acting, as the treatment may change.
The bigger question: how will you use the money?
Knowing how much you can withdraw is only the first step. The next question is what that money needs to do for you.
Consider a subscriber with an NPS corpus of ₹1 crore. The permitted lump-sum amount may help fund immediate retirement needs, while the portion used for an annuity may provide regular income. The actual outcome depends on the applicable exit rules and the annuity option selected.
Even after the exit calculation is complete, several decisions remain. How much cash should be kept aside for near-term expenses? How much might be needed for healthcare or other major costs? What income will be available every month, and how will the remaining capital be managed over a potentially long retirement?
These questions are why a withdrawal percentage should never be treated as a complete retirement strategy.
Our guide to withdrawing from your retirement corpus explores the broader challenge of drawing money from accumulated savings. If you are still estimating how much you may need, use the GreySmiles Corpus Calculator to work through your retirement corpus requirement before making decisions about withdrawals.
Annuity or SWP: what role should each play?
An annuity and a systematic withdrawal plan (SWP) are not the same thing. An annuity is an insurance product that pays income according to its terms. An SWP allows an investor to withdraw a specified amount periodically from an investment, with the remaining investment value changing according to returns and withdrawals.
An annuity can provide a more predictable stream of income, depending on the product selected. An SWP can offer greater flexibility, but the capital is exposed to market movements and the risk that withdrawals may not be sustainable over time.
Neither option should be selected simply because one appears to offer a higher initial monthly amount. Consider your essential expenses, other income sources, liquidity needs, inflation and the consequences of living longer than expected.
Read our comparison of pension versus SWP for retirement income and our guide to annuity versus SWP before deciding how different income sources could fit together.
If you already have investments intended to support retirement spending, the GreySmiles SWP Calculator can help you explore a withdrawal scenario. The SWP Tax Estimator can help you examine the tax dimension of an SWP. These tools do not replace the separate rules governing NPS exits or annuity taxation.
You can also read our analysis of how much monthly income ₹1 crore, ₹2 crore and ₹3 crore may generate in retirement. It helps put the size of a retirement corpus into the context of the income it may need to support.
Do not build your retirement plan around one percentage
People often remember NPS through a few numbers: 60:40, 80:20 or the percentage they expect to receive as a lump sum. These figures can help explain the rules, but they do not answer the most important question: will your retirement resources support the life you expect to lead?
Your plan needs to bring together your total retirement corpus, expected household expenses, other sources of income, healthcare needs and the flexibility you may require. It should also account for the possibility that markets, inflation or personal circumstances do not follow your original assumptions.
Review your arrangements well before retirement. Confirm the latest NPS exit rules, estimate your income needs, understand the tax implications and decide how much liquidity you will require. A little preparation can prevent a rushed withdrawal decision at a difficult time.
GreySmiles Take
The best time to understand NPS withdrawal rules is before you need to withdraw. Know which exit conditions apply, how much of your corpus may be available as a lump sum and what role an annuity could play. Then look beyond the withdrawal percentage. Your retirement plan should connect your NPS savings with your total corpus, expected expenses, other income and need for flexibility. Check the latest official rules before making a decision, rather than relying on an old percentage or a general online explanation.
Frequently Asked Questions About NPS Withdrawal
1. Can I withdraw my entire NPS corpus at retirement?
Not necessarily. The amount you can withdraw as a lump sum and the portion that may need to be used to purchase an annuity depend on the applicable exit rules, your NPS model and corpus size. Check the latest PFRDA regulations before planning your withdrawal.
2. Can I withdraw money from NPS before retirement?
Partial withdrawals from Tier I are permitted for specified purposes and subject to prescribed conditions. Premature exit is a separate process with different rules. Check which provision applies to your situation before submitting a request.
3. What is the difference between partial withdrawal and premature exit?
A partial withdrawal allows you to access a permitted portion of your Tier I savings while continuing the account, subject to the applicable conditions. Premature exit means leaving NPS before the normal exit conditions are met and is governed by a different set of rules.
4. Is NPS withdrawal tax-free?
Tax treatment depends on the nature of the payment and the tax provisions applicable when you withdraw. Do not assume that every amount permitted under NPS exit rules is automatically tax-free. Confirm the current treatment of your lump sum and any annuity income before making a decision.
5. What happens to my NPS money if I die?
Death-related settlement is governed by specific NPS provisions. The treatment of the accumulated pension wealth depends on the applicable rules and circumstances. Keep your nomination details updated and ensure that your family knows how to locate the relevant account information.
6. Should I choose an NPS annuity or invest the withdrawal myself?
The choice depends on your essential expenses, other retirement income, need for predictable payments, liquidity requirements and tolerance for investment risk. An annuity and a systematic withdrawal plan (SWP) work differently, so compare their features and limitations before deciding how to fund retirement.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.