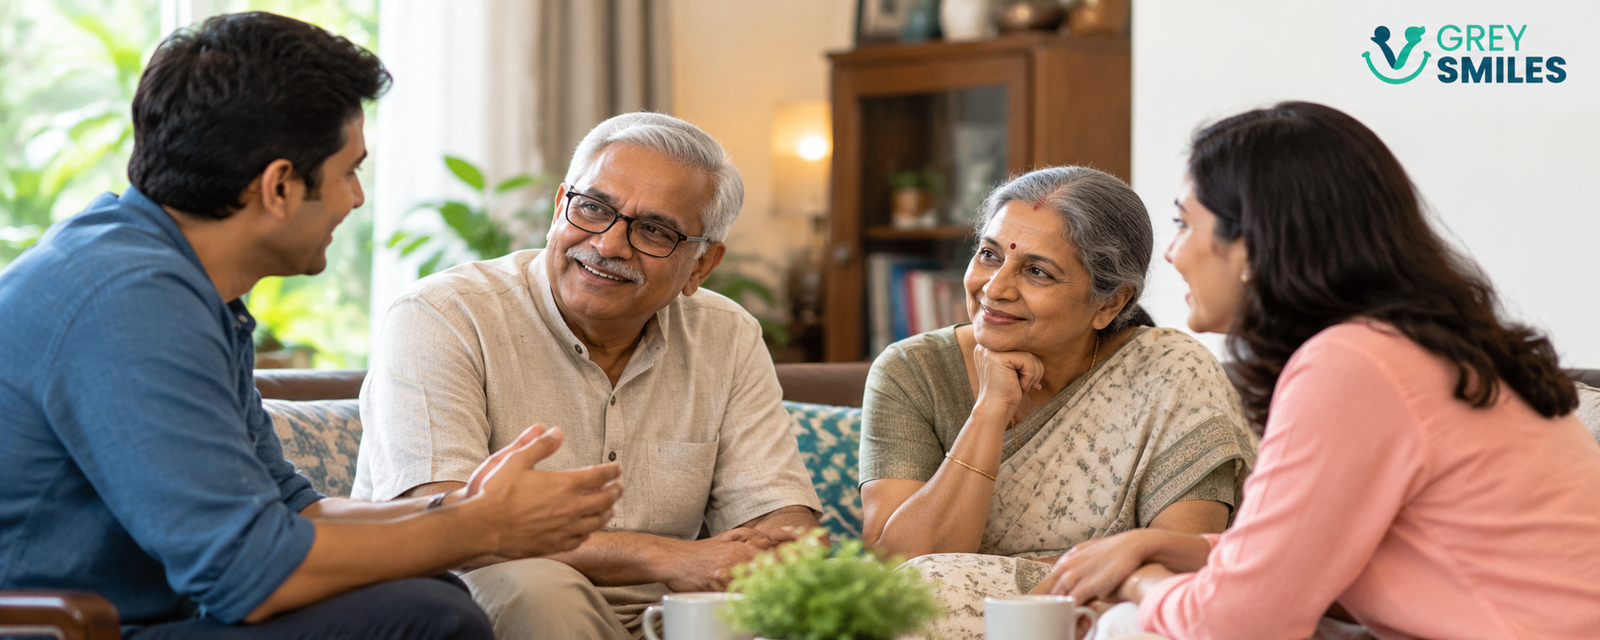
There are some conversations we find surprisingly difficult to have with our parents.
How much money will you need after retirement? What happens if one of you needs long-term care? Would you ever consider moving closer to us? Where are your important financial and legal documents? What would you want us to do if you could no longer manage everything yourself?
In many Indian families, these questions can feel intrusive. Parents may see financial matters as private. Children may worry that asking too many questions will make their parents feel old, dependent or vulnerable. So the conversation gets postponed, often for years.
Usually, that works well until something changes.
- Talking to ageing parents is about preparedness, not inheritance or taking control.
- Start with how your parents want to live, rather than how much money they have.
- Money, healthcare, living arrangements and important documents are all part of the conversation.
- The aim is not to solve everything in one conversation. It is to understand expectations while there are still choices.
Why is this conversation so difficult in India?
For generations, Indian families have relied heavily on interdependence. Parents supported children through education, careers and marriage. Children were expected to remain connected to their parents and, eventually, support them as they grew older.
Much of this was understood rather than discussed.
That understanding is becoming harder to rely on. Children may live in another city or another country. Families are smaller. Both spouses may be working. Parents are living longer and may want to remain independent for much longer as well.
The family structure has changed, but expectations have not always changed at the same pace.
A parent may think, “I don’t want to become a burden on my children.” A child may think, “Whatever happens, I will take care of my parents.” Both may mean well, but neither tells the family what will actually happen when circumstances change.
Don’t start with “How much money do you have?”
A direct question about savings, investments or property can easily sound like an enquiry about inheritance rather than retirement security. It can also make parents feel that their independence is being questioned.
Start with the life they want.
“How do you see the next ten or fifteen years?”
“Would you want to continue living here if one of you were alone?”
“What would make life easier for you as you get older?”
“Is there anything you worry about that we haven’t really discussed?”
These questions allow parents to talk about what matters to them. Money, healthcare and dependence can then enter the conversation naturally.
What does independence mean to your parents?
We often assume we know the answer. We may not.
For one parent, independence may mean continuing to live in the family home. For another, it may mean never having to ask their children for money. Someone else may be comfortable having help at home while retaining control over everyday life. Another parent may eventually prefer to move closer to their children or consider senior living.
There is no single definition of independence.
Ask your parents what it means to them.
“If life became more difficult five or ten years from now, how would you want to live?”
That is a much more useful conversation than waiting until the family has to make the decision for them.
If senior living eventually becomes part of that discussion, it is worth separating the idea of support from the stigma of an “old-age home”. Our guide to assisted living in India looks at how support and independence do not necessarily have to be opposites.
Then talk about money
Once the larger conversation has started, financial preparedness becomes easier to discuss.
You do not necessarily need to know every investment or every bank balance. You do need to understand whether there is a plan for the life your parents want. Where will their regular income come from? Are major healthcare expenses accounted for? Are there loans or other financial commitments the family should know about? Is their money accessible if one parent suddenly has to manage everything?
There is an important difference between knowing every financial detail and knowing where the important information is. Parents may reasonably want to retain control over their finances while making sure that a trusted person can locate the necessary information in an emergency.
GreySmiles has looked at this practical exercise in organising and simplifying a parent’s financial world, including documents, nominations, ownership and access.
“If your money eventually isn’t enough, what would you want us to do?”
The answer may surprise you. It may also reveal that your parents have a very different understanding of financial independence from the one you assumed.
What happens if one parent is suddenly alone?
Couples often divide responsibilities without thinking much about it. One person handles investments. The other manages household bills. One knows the insurance policies. The other knows the doctors. One remembers passwords, renewals and paperwork.
The arrangement works until one person suddenly has to manage everything.
Both parents should ideally know enough about the family’s financial and practical affairs to function independently if necessary. That means knowing where important documents are kept, what insurance exists, which accounts and investments need attention, who the relevant advisers are, and where the Will and other important legal documents can be found.
This does not mean children should automatically take over. It means the family should have enough visibility to avoid confusion when one person becomes unavailable.
The same principle applies to healthcare decisions. A Living Will and Advance Medical Directive can form part of a wider conversation about what a parent wants if they are later unable to make certain medical decisions themselves.
Healthcare is not just a medical conversation
Healthcare is often discussed only after a diagnosis, fall or hospitalisation. By then, choices can become limited and emotions can run high.
India’s National Programme for Health Care of the Elderly recognises the need for accessible, affordable and comprehensive care for an ageing population, including preventive, curative and rehabilitative services.
For families, however, the immediate question is simpler: what would your parents want if they needed more help than they do today?
Would they prefer care at home? Would they accept a professional caregiver? Would they want to move closer to their children? Would they consider senior living? What happens if one parent needs significantly more care than the other?
GreySmiles has also explored the growing importance of care at home for ageing parents, particularly when children live in another city or overseas. For many families, it can offer a middle path between complete independence and moving away from a familiar home.
These are not conversations about giving up independence. They are conversations about preserving as much independence as possible when circumstances change.
What do you expect from us?
This may be the hardest question of all.
Parents sometimes avoid asking because they do not want to burden their children. Children avoid asking because they fear making their parents feel unwanted. That silence can create completely different expectations within the same family.
A parent may assume they will eventually move in with a child. The child may assume the parents would never want to leave their own home. A parent may expect some financial support. The child may believe the parents are completely financially independent.
Nobody may be unreasonable. They simply haven’t talked about it.
“As you get older, what would you want from us?”
Ask the question and listen before offering solutions. The answer may be financial help, regular visits, help with healthcare, someone to manage practical matters, or simply knowing that their children will be available when they genuinely need them.
The three things families are trying to balance
As parents age, most families are trying to balance three things at the same time.
Parents want to retain control over their lives and decisions.
Parents may eventually need practical, medical or emotional support.
The arrangement has to remain sustainable for both generations.
Sometimes all three fit together comfortably. Sometimes they do not. The difficult part is finding an arrangement that works for this particular family, at this particular stage of life.
A family discussing home care over tea has choices. A family discussing it in a hospital corridor has considerably fewer.
Don’t turn one conversation into an interrogation
You do not need to settle retirement income, healthcare, housing, legal documents and future care in one afternoon. Trying to cover everything at once can make parents feel that a conversation about ageing has suddenly become a project about managing them.
Open one door at a time. Begin with where they would like to live as they get older. Talk about healthcare another day. Ask where important financial and legal documents are kept when the opportunity arises.
The goal is to make these subjects normal rather than dramatic.
That matters because family conversations are rarely one-time events. Plans change. Health changes. Children move. Financial circumstances change. A decision that made sense at 70 may not make sense at 80.
Parents need to start the conversation too
This cannot always be the responsibility of the children.
Parents cannot expect their children to understand plans that have never been shared. If you want to remain independent, say so. If you do not want to move in with your children, tell them. If you expect some help later, discuss it. If your finances are sufficient, let them know. If they are not, don’t wait until there is a crisis.
The Maintenance and Welfare of Parents and Senior Citizens Act reflects the broader legal recognition of responsibilities towards senior citizens. Family conversations, however, should ideally happen long before anyone needs to rely on legal provisions.
Protecting children from difficult information may feel loving. Uncertainty can become a much heavier burden later.
Start while everyone still has choices
The best time to discuss ageing is before somebody needs care. The best time to discuss money is before money becomes a problem. The best time to discuss where your parents want to live is while they are still happily living where they are.
For many families, the first conversation may simply be about what a good later life looks like. From there, the discussion can gradually move towards retirement income, healthcare, housing, legal documents, caregiving and the role children may play.
These conversations may feel uncomfortable. They may take several attempts. That is fine.
The objective is not to produce a family agreement in one sitting. It is to make sure that everyone understands the choices before circumstances make those choices for them.
Don’t wait for a crisis to discover what your parents wanted — or what they thought you would do.
The first conversation does not need to solve anything. It just needs to make the second conversation easier.
Frequently Asked Questions
How do I talk to my ageing parents about money?
Start with their plans rather than their bank balance. Ask how they see the next ten or fifteen years, what kind of lifestyle they want and what they would need if circumstances changed. Once the broader conversation is comfortable, discuss income, healthcare costs, investments, insurance and important documents.
What financial information should adult children know about their parents?
Parents do not necessarily need to disclose every financial detail. However, someone trusted should know where important information can be found, including bank accounts, investments, insurance policies, pensions, property records, liabilities and key contacts. This becomes particularly important if one parent suddenly has to manage everything alone.
When should families discuss care arrangements for ageing parents?
Ideally, before care becomes urgent. Discussing preferences while parents are still healthy gives them a greater say in whether they would prefer home care, family support, living closer to children, senior living or another arrangement.
How can I discuss senior living with my parents without making them feel unwanted?
Begin by asking how they would like to live over the next ten or fifteen years and what would make everyday life easier. Senior living can then be discussed as one possible choice rather than a decision that has already been made for them.
What if my parents refuse to discuss their finances?
Do not turn the conversation into a confrontation. Start with practical issues such as healthcare, living arrangements and emergency contacts. The financial discussion can follow when your parents understand that the purpose is preparedness and continuity rather than control or inheritance.
Sources & References
National Programme for Health Care of the Elderly (NPHCE) — Directorate General of Health Services, Government of India.
Maintenance and Welfare of Parents and Senior Citizens Act — Government of India.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.