When we talk about retirement planning, we usually make it sound like an individual exercise. How much corpus do I need? When can I retire? Will my savings last?
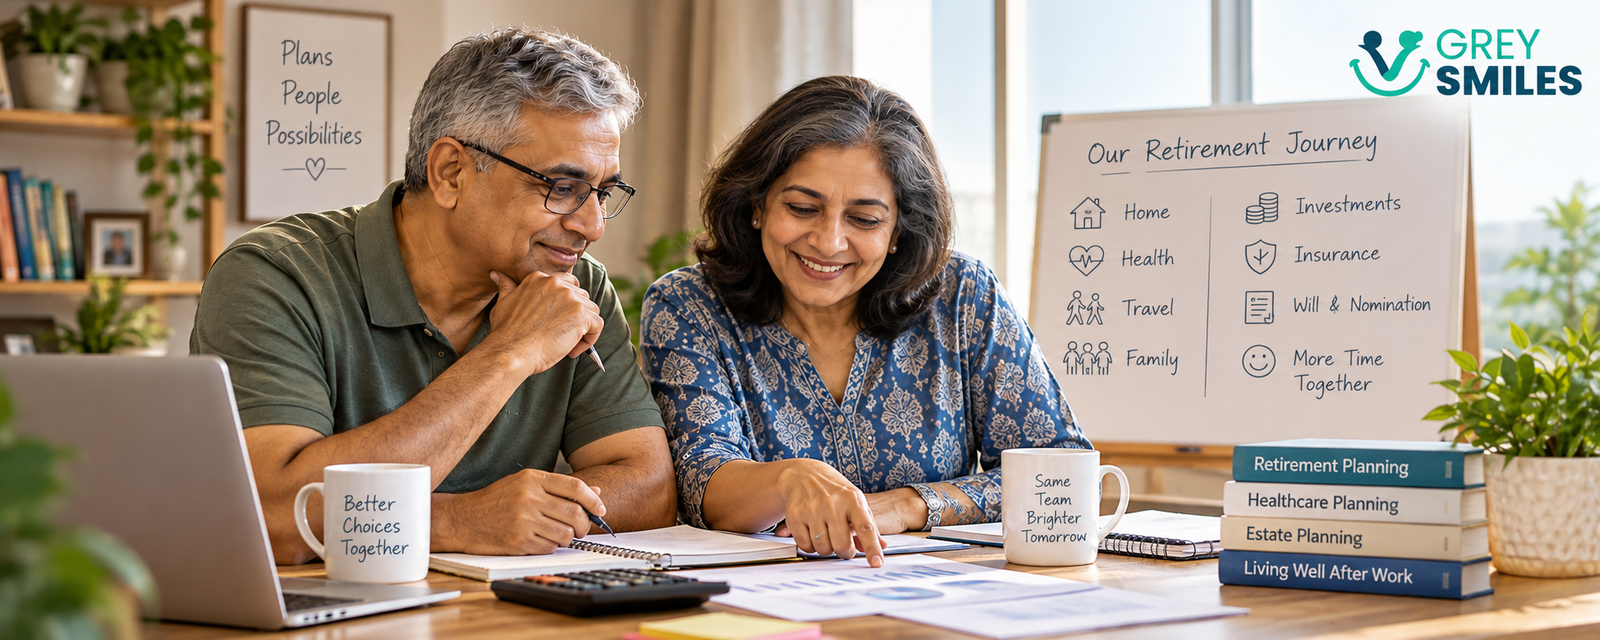
But retirement rarely happens to just one person. A person may retire from work, but the family does not retire from life. Income changes, expenses change, children become independent, parents may need support, health needs evolve and the way the family manages its money may change as well.
Retirement is therefore a household transition, not merely an individual’s financial event.
At a Glance
- Retirement affects the household, not just the person leaving work.
- If both spouses work, both incomes, investments and retirement dates matter.
- A couple can look at asset allocation across the household rather than in isolation.
- Risk tolerance may differ between spouses, but risk capacity matters too.
- Retirement planning should cover money, health, longevity, family responsibilities and life after work.
Retirement is a journey, not a date
For many families, retirement is not a simple move from working to retired. One spouse may stop working while the other continues for several years. One may retire completely while the other takes up consulting. Both may retire together, but their spending and priorities may change considerably over the following decades.
During the early years, travel, hobbies and family commitments may increase spending. Later, healthcare and caregiving can become more important. Inflation, investment risk and longevity run through the entire journey.
This is why retirement planning is not simply about arriving at a corpus number. It is about building a financial system that can adapt as the family’s circumstances change.
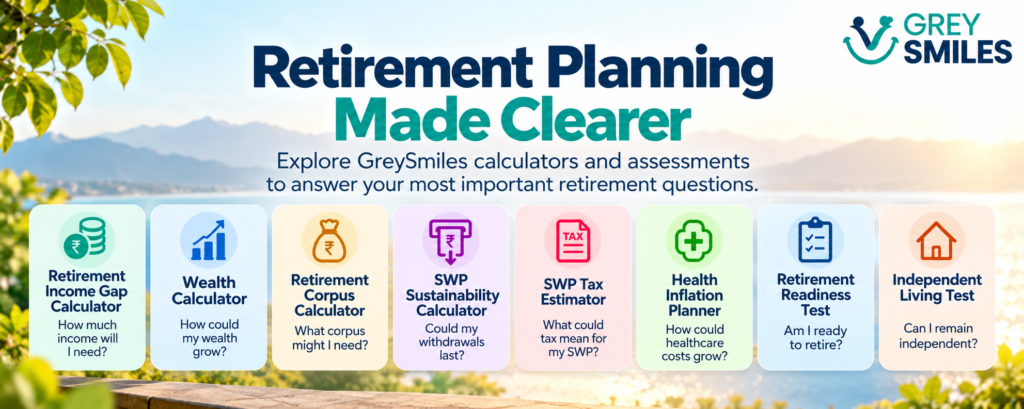
If you are not sure how prepared your household really is, the GreySmiles Retirement Readiness Test is a useful starting point. It looks beyond the corpus to the wider retirement picture.
Your retirement number may not be just your number
Consider a husband who plans to retire at 58 while his wife expects to continue working until 62. Should her income be ignored when planning his retirement? Of course not. Her income may continue to meet part of the household’s expenses, while her own investments and retirement benefits may add to the family’s resources.
The reverse can also happen. A wife may retire first while her husband continues working. The important point is that the family’s retirement cash flow does not necessarily change on the day one person retires.
That is why couples should look at household spending, income and assets together. Before worrying about a target corpus, it is worth understanding what the household actually spends and how that spending might change after retirement. This is also the thinking behind the GreySmiles approach to estimating retirement spending.
Two portfolios can make one household plan
This becomes particularly interesting when spouses have different attitudes towards investment risk. Imagine a husband who is very comfortable with fixed deposits and a wife who is willing to take some equity exposure through mutual funds.
Looking at their portfolios separately may tell two very different stories. Looking at them together may provide a better picture of the family’s overall asset allocation.
| Husband | Wife | Household | |
|---|---|---|---|
| Fixed income | ₹60 lakh | ₹20 lakh | ₹80 lakh |
| Equity-oriented | ₹0 | ₹40 lakh | ₹40 lakh |
| Total | ₹60 lakh | ₹60 lakh | ₹1.20 crore |
The husband may appear completely conservative when viewed alone, while the wife may appear considerably more comfortable with market risk. At the household level, however, the family has ₹80 lakh in fixed income and ₹40 lakh in equity-oriented investments.
This does not mean that couples should simply merge their portfolios or ignore ownership, taxation or individual financial needs. It means that for shared goals, household asset allocation can be an important additional lens.
GreySmiles Calculator
Estimate Your Retirement Corpus
Once you understand household spending, income and retirement timing, you can explore the corpus that may be required using the GreySmiles Corpus Calculator.
Illustrative calculation only. Actual requirements depend on individual circumstances and assumptions.
Risk tolerance is only part of the picture
NISM’s financial-planning framework distinguishes between a person’s willingness to take risk and their ability to bear it. That distinction matters for couples.
One spouse may be comfortable with equity while the other is not. But the more important household question is also whether the family can afford the potential loss. A person may be willing to take substantial risk without having the financial capacity to absorb it.
This is why asset allocation should connect back to goals, time horizon, liquidity needs and the family’s ability to withstand losses. Diversification can help manage risk, but it cannot remove it.
Nor should the more comfortable spouse automatically be expected to carry all the family’s investment risk. The conversation should be about what the household needs, rather than which spouse is willing to take more risk.
The spouse is more than another source of income
There is another side to this. Retirement planning often focuses on salaries and investments, but both spouses also need to understand the family’s financial arrangements.
If one person has always handled the investments, what happens if that person dies, becomes unable to manage money or simply cannot deal with financial matters later in life? The other spouse should know what assets exist, where they are held, what insurance and liabilities exist, where important documents are kept and who the nominees are.
That is not just investment planning. It is family financial resilience.
Retirement is also about the life you want to lead
One spouse may want to continue working while the other wants to stop. One may want to travel while the other prefers spending more time with family. One may want to move to a smaller city while the other wants to remain close to friends and healthcare.
These may sound like lifestyle differences, but they can have financial consequences. Where you live, how much you travel, whether you continue working and how you spend your time all influence the retirement budget.
GreySmiles Take
Don’t plan retirement person by person if you live life as a family. Your portfolios do not have to be identical, your risk preferences do not have to be identical and your retirement dates do not have to be identical. But the household plan should make sense together.
Think about what happens after the corpus is built
Building the corpus is only one part of retirement planning. Once one or both spouses stop working, the question changes to how the household will generate income from its accumulated money.
The GreySmiles SWP Calculator can help you explore how a starting corpus and planned withdrawals may behave over time. It is useful for understanding the mechanics of drawing income from investments, rather than assuming that a corpus automatically translates into a sustainable retirement income.
Healthcare deserves separate attention as well. It can become a significant and unpredictable component of a long retirement, which is why the GreySmiles Health Planner Calculator can be used to explore future healthcare requirements.
Five questions every couple should discuss
Before getting into detailed calculations, couples can start with five simple questions: When does each of us expect to stop working? What does our household spend today? What income will continue after each of us retires? What investments do we have collectively? And what happens if either one of us can no longer manage the family’s finances?
These questions will not produce a perfect retirement plan. They will, however, create something much more useful: a shared understanding of the journey ahead.
Retirement is not about one person having enough money
Your retirement does not begin simply when your salary stops. It begins when the family starts planning for a different way of living.
Your spouse’s income matters. Their investments matter. Their retirement date matters. So do their aspirations, health, risk preferences and ability to manage money. The same applies to the responsibilities the family may continue to carry towards children or parents.
So instead of asking only, “Have I saved enough for my retirement?”, couples should also ask:
Have we built a financial and life plan that can take us through retirement together?
That is a much bigger question, and perhaps a much better one.
Frequently Asked Questions
Should couples plan retirement together?
Yes, particularly where household expenses, financial goals and responsibilities are shared. Each spouse should still understand their own finances, but the household should also look at combined income, assets, liabilities and retirement timelines.
Should a husband and wife’s investments have the same asset allocation?
Not necessarily. Their risk preferences and individual circumstances may be different. However, for shared goals, it can be useful to also look at the combined household asset allocation and whether it is appropriate for the family’s goals and risk capacity.
What if one spouse is comfortable with equity and the other prefers FDs?
The difference in risk tolerance should be acknowledged rather than ignored. The couple can examine the household portfolio as a whole while still respecting individual ownership and preferences. The objective is not to make both portfolios identical.
Does my spouse’s income reduce the retirement corpus I need?
It can affect the amount the household needs to draw from investments, particularly if one spouse continues working after the other retires. The impact depends on household expenses, the duration of the second income, taxes, other income sources and the family’s overall financial position.
Why is retirement planning more than a corpus calculation?
Because retirement also involves cash flow, inflation, longevity, healthcare, investment risk, changing lifestyle needs and the possibility that one spouse may eventually have to manage the family’s finances alone.
Sources & References
National Institute of Securities Markets (NISM) — investor education material covering financial goals, risk management, diversification, asset allocation and retirement planning.
NISM — retirement planning material covering longevity risk, inflation, healthcare and other retirement-related risks.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.