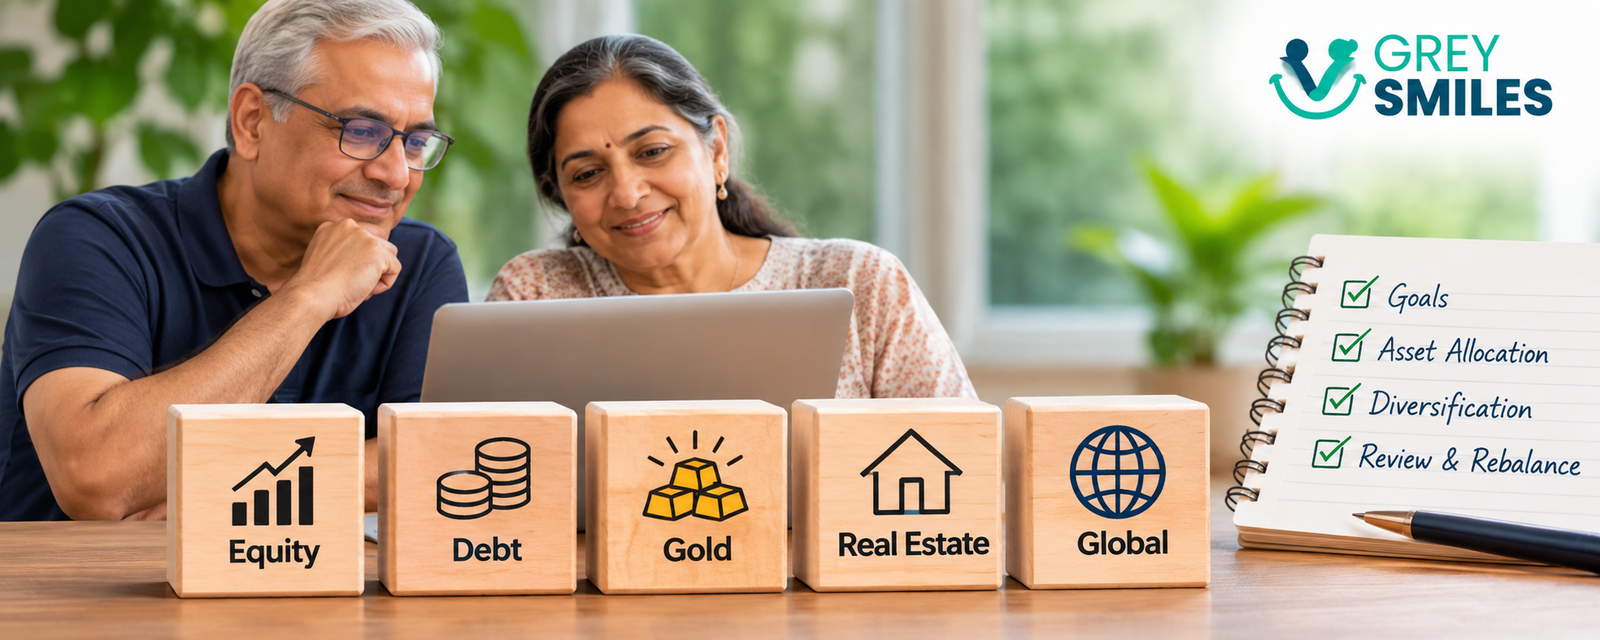
Diversifying investments across asset classes can help manage portfolio risk and build long-term financial resilience.
By Kartikey Gupta: Kartikey Gupta is a finance professional with 6+ years of experience across capital markets, insurance and financial services. He is a CMT and CFA Level II qualified professional and writes on retirement planning, investing and financial security.
Recent geopolitical developments, changing interest rate expectations and uncertainty across global markets have reminded investors why portfolio diversification matters. For Indian investors, building a resilient portfolio is not simply about owning different investments; it is about understanding how different assets behave, how they interact and how they contribute to long-term financial goals. Portfolio diversification means spreading investments across different parts of the economy and financial markets so one investment’s underperformance doesn’t disproportionately affect the entire portfolio. It is not a way to eliminate risk or guarantee returns. It builds resilience and reduces dependence on any single source of return.
However, diversification should not begin with a list of investment products. It should begin with the investor: their financial goals, income, expenses, existing assets, liabilities, time horizon and ability to absorb investment losses.
This is consistent with the financial-planning and portfolio-construction approach covered by the National Institute of Securities Markets (NISM). Asset allocation, diversification and portfolio review are connected decisions. They should be considered together rather than in isolation.
At a Glance: Portfolio Diversification
- Diversification reduces excessive dependence on individual companies, sectors and asset classes.
- Financial goals, time horizon and risk profile should guide asset allocation.
- Equity, debt, gold, real estate and international investments can play different roles in a portfolio.
- Owning several investments does not automatically mean that a portfolio is diversified.
- Correlation between investments matters, and it can change during market stress.
- Periodic reviews and rebalancing help keep a portfolio aligned with its objectives.
- Diversification cannot eliminate market-wide risk or guarantee positive returns.
Why Diversification Matters: Managing Risk Beyond Market Returns
One common mistake investors make is confusing the number of investments they hold with the level of diversification in their portfolio.
Owning shares of ten companies does not necessarily mean that a portfolio is diversified. If all ten companies belong to the same sector or depend on similar economic conditions, they may respond to market developments in much the same way.
Consider an investor whose equity portfolio is heavily concentrated in information technology companies. A slowdown in global technology spending, changes in client budgets or adverse developments in major overseas markets could affect several holdings simultaneously.
The investor may own different stocks, but the underlying exposure remains concentrated.
Diversification helps spread exposure across different sources of risk and return, rather than allowing one market event or business sector to determine the outcome of an entire investment portfolio.
Understanding the Two Broad Categories of Market Risk
It helps to distinguish between two types of risk.
1. Unsystematic Risk
This is the risk associated with a particular company, industry or business. Examples include poor management decisions, regulatory action, operational failures or a slowdown in a specific sector.
Diversification across companies and sectors can help reduce the impact of these risks. If one company performs poorly, the effect on a well-spread portfolio may be limited.
2. Systematic Risk
This is the broader risk affecting financial markets or the economy. Interest rate changes, inflation, geopolitical developments, financial crises and widespread market corrections are examples.
Diversification across investments may help manage the impact of such developments, but it cannot eliminate systematic risk. When the entire market declines, individual securities can also lose value.
NISM makes this distinction in its investor education material on managing investment risks. It also highlights that investment quality, diversification and matching an investment to the time horizon of a financial goal all matter.
The objective, therefore, is not to create a portfolio that is immune to every market event. It is to avoid unnecessary concentration and ensure that the portfolio is not excessively dependent on one outcome.
Start With the Investor, Not the Investment Products
Before deciding how much to invest in equity, debt or gold, an investor needs to understand their own financial position. This is an important part of the financial-planning and portfolio-construction process covered in the NISM Investment Adviser curriculum.
The same investment allocation will not be suitable for everyone. A salaried person in their thirties, a business owner approaching retirement and a retired individual drawing from accumulated savings have different financial requirements.
A useful starting point is to examine the following areas.
1. Financial Goals and Their Time Horizons
Investments should be linked to specific financial goals. These could include buying a house, funding a child’s education, building a retirement corpus or meeting healthcare expenses later in life.
The time available to achieve each goal matters. Money required in the near future generally needs a different investment approach from money that can remain invested for many years.
For example, exposing money needed for a near-term expense to substantial equity-market volatility may create a mismatch between the investment and the financial goal. Long-term goals, on the other hand, need to account for inflation and the possibility that conservative investments may not preserve purchasing power over time.
2. Income, Expenses, Assets and Liabilities
An investor’s existing financial position influences how much risk they can reasonably take. Income stability, household expenses, outstanding loans, emergency savings, existing investments and future commitments all need to be considered.
Someone with substantial debt and uncertain income may have a different capacity to withstand investment losses from someone with stable income, manageable liabilities and adequate emergency reserves.
This is why portfolio construction should not begin by copying an asset allocation used by another investor.
3. Risk Tolerance and Risk Capacity
Risk tolerance refers to how comfortable an investor is with fluctuations and possible losses. Risk capacity refers to their financial ability to withstand those losses without compromising important goals.
The two are related but not identical. An investor may be comfortable taking risks but may not have the financial capacity to absorb a significant loss. Another investor may have the financial capacity to take risk but feel uncomfortable with market volatility.
A suitable portfolio needs to take both into account.
4. Liquidity and Other Investment Constraints
Some investments may be difficult to sell quickly or may involve significant costs when exiting. Others may have tax implications, lock-in periods or regulatory restrictions.
NISM’s portfolio-construction framework recognises investment constraints such as liquidity, taxation and regulatory requirements. These should be considered before deciding the portfolio structure.
Asset Allocation: The Foundation of Portfolio Diversification
Asset allocation is the process of deciding how much of a portfolio should be invested in different asset classes. Diversification involves spreading investments within and across those allocations.
The two work together, but they are not the same.
For example, an investor may decide that their portfolio should contain equity, debt and gold. That is an asset allocation decision. They then need to consider how their equity exposure is spread across companies and sectors, how their debt investments are structured, and how the different asset classes may behave in different market conditions. That is diversification.
NISM’s portfolio-construction curriculum specifically includes asset allocation, correlation across asset classes and securities, strategic and tactical allocation, and portfolio rebalancing.
Different Asset Classes Serve Different Purposes
Equity
Direct shares, diversified equity mutual funds and exchange-traded funds can provide participation in the long-term growth of businesses and the economy. However, equity investments carry market risk and can experience significant short-term volatility.
Debt
Government securities, bonds, deposits and suitable debt mutual funds can provide income and help meet relatively predictable financial requirements. Credit risk, interest rate risk and liquidity must still be considered.
Gold
Gold has traditionally been viewed as a store of value and can behave differently from equities and debt under certain market conditions. Investors may consider appropriate forms of gold exposure, keeping in mind price volatility, costs and taxation.
Real Estate and REITs
Direct property ownership and Real Estate Investment Trusts provide exposure to the property sector. However, real estate is not automatically a defensive investment. Property valuations, rental demand, interest rates and economic conditions can influence returns. Direct property also requires attention to maintenance, transaction costs and liquidity.
The important point is that these asset classes should not be selected simply because they are different. Each should have a defined role in the portfolio.
Understanding Correlation: Why Different Investments Matter
One of the more important concepts in portfolio diversification is correlation. It describes how the returns of two investments move in relation to each other.
If two investments tend to move in the same direction, they have a positive correlation. If they tend to move in opposite directions, they have a negative correlation. If their movements have little consistent relationship, their correlation is relatively low.
For diversification, investors need to look beyond the names of their investments and understand how they behave together.
For example, two equity mutual funds may appear to offer different investment strategies. However, if both hold many of the same companies, they may provide limited additional diversification.
Similarly, equity, debt and gold may respond differently to certain economic developments. But their relationship is not fixed. During a period of market panic or liquidity stress, investments that normally behave differently may decline together.
NISM’s October 2026 investor education material specifically discusses how correlations between asset classes can change across market conditions. It highlights the importance of combining suitable asset allocation with meaningful diversification and disciplined rebalancing.
The practical lesson is simple: diversification is not about collecting different products. It is about understanding the underlying exposures and how they may behave together.
Diversification Within Equity: Avoiding Sector Concentration
Even after deciding how much to allocate to equity, investors need to examine where that equity exposure lies.
A portfolio concentrated in a handful of popular sectors can become vulnerable when market sentiment changes. An investor may hold companies in information technology, banking, pharmaceuticals, consumer goods, infrastructure and manufacturing. These sectors are influenced by different business cycles, demand patterns and economic factors.
However, investing in every sector is neither necessary nor practical. The objective is to avoid excessive dependence on a single industry or investment theme.
Broadly diversified equity funds can help achieve this, although investors should examine their underlying holdings to identify overlapping exposures. Sector-specific funds and thematic investments require particular care. A portfolio containing several sector funds may appear diversified by the number of schemes but remain concentrated in a few underlying industries.
For a closer look at how mutual funds can fit into a long-term financial plan, read our guide to mutual funds for retirement.
Geographic Diversification: Looking Beyond India
Indian investors are naturally exposed to the domestic economy through their employment, property, savings, businesses and investments. This can create a degree of concentration in one country’s economic and financial conditions.
International investments can provide exposure to companies, industries and markets that may not be adequately represented in Indian portfolios. For example, international funds and ETFs may offer access to overseas technology businesses, consumer companies and other global industries.
However, international diversification introduces additional considerations:
- Currency movements can influence returns when investments are converted back into rupees.
- Overseas markets have different regulatory, economic and political environments.
- International investments may carry different tax and reporting implications.
- Access, investment limits and product availability can change.
Geographic diversification should therefore be considered as part of an overall allocation strategy, not as an automatic way to improve returns.
The Geopolitical Reality: Why Global Developments Matter to Indian Investors
Geopolitical events are no longer distant developments that affect only international markets. Their consequences can reach Indian businesses, households and investment portfolios through several channels.
For India, the transmission of these developments is particularly relevant in areas such as energy imports, trade, currency movements and foreign investment flows.
Crude Oil and Imported Inflation
A sustained rise in crude oil prices can increase India’s import bill and put pressure on transportation, manufacturing and other operating costs. This can eventually influence inflation and corporate profitability.
Inflation also affects the real value of long-term savings. Our article on beating inflation in India through portfolio diversification explores why investors need to consider purchasing power when planning for the future.
Interest Rates and Global Capital Flows
Changes in monetary policy in major economies can influence the relative attractiveness of emerging-market investments. Shifts in global investor sentiment can affect capital flows into Indian financial markets.
Supply Chains and Manufacturing
Changes in global trade relationships and supply-chain strategies can create opportunities for Indian manufacturing. However, the benefits depend on investment, infrastructure, competitiveness and the ability of businesses to execute.
Currency Movements
Geopolitical uncertainty and changes in international capital flows can influence currency markets. For investors holding overseas assets, currency movements can add another layer of risk as well as potential return.
These developments demonstrate why a portfolio should not be built around one economic assumption, such as uninterrupted domestic growth, permanently low inflation or stable global trade. The objective is to participate in long-term opportunities while recognising that economic conditions can change.
Strategic Allocation, Tactical Changes and Rebalancing
Once an investor has established an appropriate asset allocation, the next challenge is maintaining it over time. This is where strategic allocation, tactical allocation and rebalancing become relevant.
Strategic Asset Allocation
Strategic asset allocation is the long-term investment mix established around the investor’s goals, time horizon and risk profile. It provides a framework for how the portfolio should be structured across different asset classes.
It is not intended to change every time markets rise or fall. Its purpose is to provide consistency and reduce the temptation to make impulsive decisions based on short-term market movements.
Tactical Asset Allocation
Tactical asset allocation involves making limited adjustments to the long-term allocation in response to specific market or economic considerations.
Such changes require a clear rationale and an understanding of the risks involved. Tactical decisions should not become frequent attempts to predict market movements or chase sectors that have recently performed well.
Portfolio Rebalancing
Over time, market movements can cause the portfolio to move away from its original allocation.
For example, if equity investments rise substantially, equity may begin to represent a much larger share of the portfolio than originally intended. Rebalancing involves reviewing the allocation and, where appropriate, bringing it back towards the planned structure.
NISM’s investor education guidance recommends reviewing changes in financial circumstances and goals, and rebalancing when necessary to keep investments aligned with those objectives.
Rebalancing should consider transaction costs, taxes, investment restrictions and the investor’s changing circumstances. It should not become an attempt to predict short-term market movements.
Diversification Is Not the Same as Owning More Investments
A common misconception is that a larger number of investments automatically makes a portfolio safer. It does not.
An investor may hold several mutual funds that own many of the same companies. Another may have investments spread across different sectors but remain heavily dependent on equity markets. A third may own property, shares and gold but have very little readily available money for emergencies.
In each case, the portfolio may look diversified without being adequately balanced.
There are three questions worth asking:
- What drives the returns? Do the investments depend on different economic and market factors, or are they exposed to similar risks?
- What happens during a downturn? Could several investments decline together because of the same underlying event?
- Can I access the money when needed? Does the portfolio provide sufficient liquidity for planned expenses and unexpected requirements?
Diversification should be evaluated by examining the underlying exposures, not merely the number of products held.
How Should Investors Review Their Diversification Strategy?
A diversified portfolio is not something that can be created once and then ignored. Financial goals, income requirements, market conditions and personal circumstances change over time. A periodic review can help keep the portfolio aligned with its intended purpose.
Review Financial Goals and Circumstances
Begin by checking whether financial goals, their estimated costs or the time available to achieve them have changed. Marriage, children, a change in employment, a new liability or retirement can all affect financial requirements.
Review Asset Allocation
Check whether the proportion invested in equity, debt, gold and other assets still reflects your financial goals and risk tolerance. Market movements can change these proportions even when no new investment decisions are made.
Examine Concentration
Look at the underlying holdings of mutual funds and other investments. Identify excessive exposure to individual companies, sectors, themes or geographies.
Assess Liquidity Requirements
Money required for near-term expenses should not be exposed to unnecessary market volatility or locked into investments that are difficult to access. This is particularly important for people approaching retirement or already dependent on their investments for regular income.
Understanding the retirement corpus required to support future expenses is one part of this exercise. The GreySmiles Retirement Corpus Calculator can help readers explore their corpus assumptions.
Rebalance When Necessary
Rebalancing involves bringing the portfolio back towards its intended asset allocation when market movements cause significant deviations. It should be guided by the investor’s financial plan, not by short-term market predictions.
Why Diversification Becomes Particularly Important Around Retirement
Diversification matters throughout an investor’s life, but its purpose and practical implications can change with age and financial circumstances.
A person in their thirties may have a long investment horizon and regular employment income. Someone approaching retirement may have less time to recover from a major market decline. A retired person drawing regular income from investments needs to consider liquidity and the possibility of having to sell investments during an unfavourable market.
This does not mean that every retiree should avoid equity or that every younger investor should take high risks. The appropriate allocation depends on the individual’s goals, financial position, risk profile and time horizon.
For retirement planning, diversification must also be considered alongside inflation, healthcare costs, regular expenses and the expected duration of retirement.
Our Retirement Corpus Calculator can help estimate the amount required, while the SWP Calculator allows readers to explore how different withdrawal assumptions may affect their retirement corpus.
What Diversification Cannot Do
It is equally important to understand the limitations of diversification.
It cannot prevent losses during a broad market correction. It cannot guarantee that gold will rise when equities fall. It cannot make an unsuitable investment suitable simply by adding it to a portfolio.
Different asset classes can become more closely correlated during periods of financial stress. International investments can also decline when global markets experience widespread uncertainty.
NISM also highlights that some risks cannot be diversified away. Investors therefore need to consider investment quality, the time horizon of each financial goal and the suitability of individual products, alongside diversification.
Diversification is a risk-management approach, not a substitute for understanding investments. The quality of the underlying investments, their costs, liquidity, taxation and suitability for the investor remain important.
GreySmiles Take: Resilience Matters More Than Chasing Every Opportunity
The purpose of diversification is not to own a little bit of everything or to constantly move money between investments in response to global developments.
It is to build a financial portfolio that can withstand different economic conditions without placing an excessive burden on any one investment or market.
For someone building long-term wealth, this means balancing growth opportunities with stability and liquidity. For someone approaching retirement, it also means ensuring that the money needed for regular expenses is not unnecessarily exposed to market fluctuations.
The NISM approach reinforces an important point: investment decisions should be connected to the investor’s financial goals, risk profile, time horizon and constraints. Diversification is one part of that process, not a standalone investment strategy.
Geopolitical developments, changing trade relationships and market volatility will continue to create uncertainty. Investors cannot control these events, but they can examine how exposed their financial plans are to them.
A resilient portfolio is not necessarily the one that performs best in every market cycle. It is one that remains aligned with the investor’s goals and financial needs across different market conditions.
Frequently Asked Questions
What is portfolio diversification?
Portfolio diversification means spreading investments across different asset classes, companies, sectors and geographies. The aim is to reduce excessive dependence on any one investment or source of return.
Why is diversification important for Indian investors?
Indian investors are exposed to domestic economic conditions as well as global developments that influence energy prices, interest rates, currency movements and capital flows. Diversification can help reduce concentration risk and make a portfolio less dependent on one market or sector.
What is the difference between asset allocation and diversification?
Asset allocation is the process of deciding how much of a portfolio should be invested in different asset classes. Diversification involves spreading investments within and across those allocations to avoid excessive concentration. The two work together in portfolio construction.
What is correlation in portfolio diversification?
Correlation describes how the returns of two investments move in relation to each other. Understanding correlation helps investors assess whether different investments genuinely provide diversification or are exposed to similar market factors. Correlations can change across market conditions.
Does diversification guarantee that I will not lose money?
No. Diversification can reduce certain types of investment risk, particularly company- and sector-specific risk. It cannot eliminate market-wide risk or guarantee positive returns.
How often should I review my investment portfolio?
There is no universal review frequency. Investors should review their asset allocation periodically and whenever there is a meaningful change in financial goals, income, liquidity requirements or personal circumstances. Rebalancing should be based on the portfolio’s intended allocation rather than short-term market predictions.
Is geographic diversification useful for Indian investors?
International investments can provide exposure to markets and businesses outside India. However, they also introduce currency, regulatory, taxation and market risks. The decision should form part of an overall investment plan.
Does diversification become more important after retirement?
It can be particularly important after retirement because investments may need to support withdrawals over a long period. A retirement portfolio needs to consider growth, income, liquidity, inflation and the possibility of market declines during withdrawal years.
Sources & References
- National Institute of Securities Markets (NISM) – How to Manage Investment Risks.
- NISM – Things to Consider Before Investing.
- NISM – Investment Adviser Level 1 Curriculum: Portfolio Construction Process.
- NISM – Investor Education, October 2026: Asset Allocation, Correlation and Portfolio Building.
- Securities and Exchange Board of India (SEBI) – Investor education and investment risk awareness.
- Association of Mutual Funds in India (AMFI) – Mutual fund education and investor resources.
This article is intended for general financial education. It does not constitute personalised investment advice or a recommendation to buy or sell any particular investment. Asset allocation and investment choices should be based on individual financial circumstances, goals, risk tolerance and time horizon. Readers should consult a SEBI-registered investment adviser where personalised advice is required.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.