The Spirit of Active Aging in India
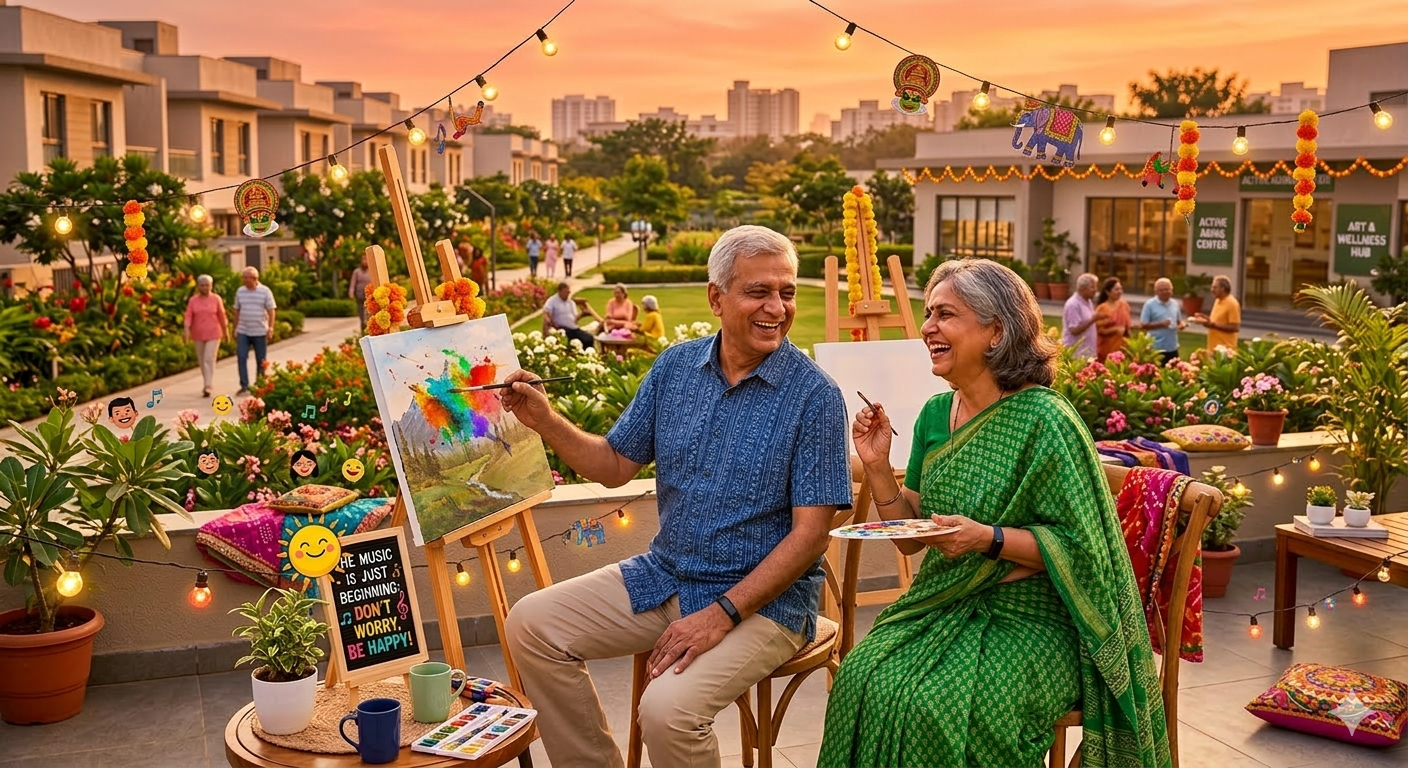
Retirement in the Indian context is undergoing a massive cultural shift. Moving away from the traditional model of total dependence on the joint family, today’s pre-retirees are looking toward a future of “active aging” and financial autonomy. Executing the right strategy for retirement planning for Indian over 40 is critical because transitioning from a structured professional life to a self-determined one often brings a cocktail of anxieties—ranging from the rising cost of healthcare to the fear of outliving one’s corpus. To truly embody the spirit of Bobby Mcferrin’s classic “Don’t Worry, Be Happy,” one must realize that happiness isn’t the absence of concerns, but the presence of a robust plan. By addressing the “worry triggers” head-on while you are still in your 40s, you can build a fortress of financial security and physical vitality. This guide explores how to pivot your mindset and your investments now, ensuring that when the 9-to-5 ends, the music is just beginning.
Quick Navigation
1. Understanding the “Worry Triggers” for Pre-Retirees in Their 40s
For most Indians, retirement worries usually center on three pillars: Medical Inflation, Longevity Risk (outliving your money), and Social Isolation. In India, retail healthcare costs are rising at an alarming rate of nearly 14% annually, which can quickly deplete a standard savings account. Acknowledging these stressors early allows you to move from a state of “worry” to a state of “workable strategy.”
Furthermore, structural shifts in urban India mean that traditional joint family cushions are evolving. As adult children migrate to metro hubs or abroad, seniors must prepare psychologically for the emotional and social changes that stem from living independently. Identifying these friction points in your 40s prevents the sudden identity vacuum that catches many executive-level professionals off guard when they exit the workforce.
Also read: The Best Cities to Retire in India
2. Securing the Bag: Financial Moves and Retirement Planning for Indian Over 40
To keep the “Don’t Worry” vibe alive, your 40s should be your peak accumulation and protection phase. Embracing aggressive retirement planning for Indian over 40 ensures that financial autonomy becomes the absolute foundation for mitigating any negative psychological adjustments later on.
- The Inflation Buffer: Don’t just save; invest in equity-oriented instruments like Mutual Funds or the National Pension System (NPS) to ensure your long-term compounding returns comfortably beat the Indian domestic inflation rate.
- Debt Liquidation: Aim to be completely “Home Loan Free” by 50. Entering your post-work life with zero EMIs is the ultimate psychological “happy” pill, removing a massive layer of vulnerability.
- The Emergency Bucket: Keep at least 12 months of living expenses in a highly liquid fund to handle unforeseen familial obligations or sudden market drawdowns without touching your long-term equity compounding corpus.
3. Health as Your Greatest Asset
You cannot enjoy personal freedom or focus on lifestyle design if you are in chronic physical pain or constantly visiting clinics. Managing physical health is deeply tied to managing the psychological transitions of aging; a healthy body fosters social agility and confidence.
- Separate Health Insurance: Do not rely solely on your corporate cover, as it vanishes the moment you retire. Secure a comprehensive, independent personal health insurance plan with a high sum insured—and a Super Top-up—before you hit 50 to lock in lower premiums and avoid lengthy pre-existing condition waiting clauses. Check out institutional guidelines on senior health coverage on the official Insurance Regulatory and Development Authority of India (IRDAI) portal.
- Preventative Maintenance: Focus on Dharma (duty) toward your body. Regular, proactive screenings for Vitamin D, B12, lipid profiles, and HbA1c are absolutely essential in the Indian lifestyle to catch and manage lifestyle metabolic diseases before they escalate.
4. The Psychology of a Happy Retiree
Successfully navigating the final transition requires shifting your perspective from simple asset preservation to dynamic life orchestration. Effective retirement planning for Indian over 40 means understanding that leaving your job is not a passive end, but the official beginning of your “Second Innings.”
Cultivate an active, non-screen hobby early. Whether it is engaging in local community service, mentoring early-stage startups, or returning to a creative childhood passion, having a clear reason to wake up each morning keeps cognitive decline at bay. In addition, transitioning a portion of your wealth away from rigid accumulation toward funding unique travel experiences can spark significant personal growth. Spending on discovery and experiences builds completely fresh social footprints outside of your past corporate circles, letting you thrive through cultural transitions.
A New Horizon: Finally Living for Yourself
For the last three or four decades, your life belonged to your obligations. You lived for your employers, your children’s education, your home loans, and societal expectations. You measured your worth by what you provided for others.
Retirement is the ultimate permission slip to break that cycle. It is not a passive winding down, but a vibrant clean slate—a profound opportunity to state a brand-new meaning for your existence. For the first time in your adult life, you are allowed to be beautifully selfish. Reclaim your calendar, dive into passions you shelved decades ago, and let go of the need for external validation. You have done the work and paid your dues; now, step into the driver’s seat and finally live for yourself.
Your career has ended, but your life’s definitive chapter is just beginning.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.