Protecting your retirement plans when your regular income is disrupted.
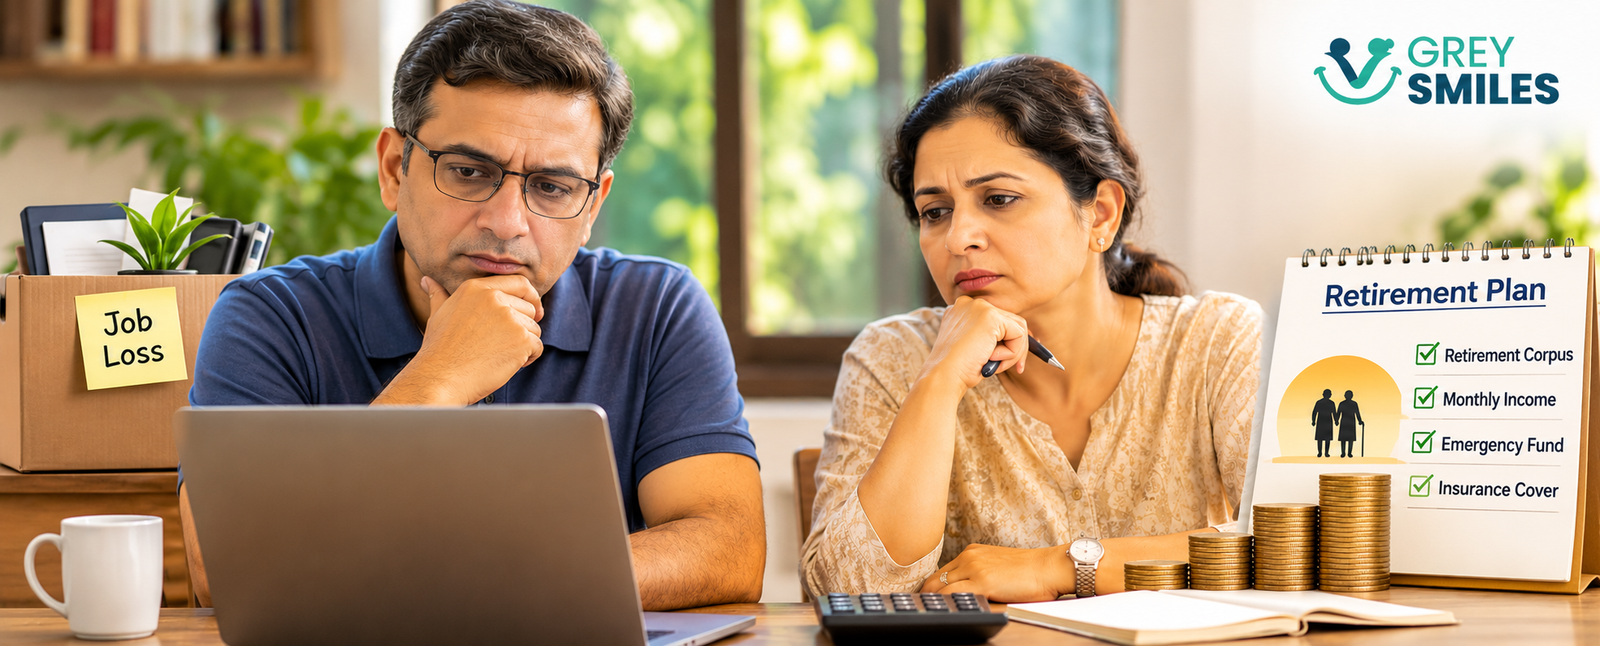
Losing a job at 40 can do more than interrupt your career. It can derail your retirement plans, drain your savings and put your family’s financial security at risk. The consequences can be even more serious if illness or disability affects your ability to earn, particularly when the interruption lasts for years.
For many Indian professionals, monthly expenses do not stop when a salary does. Home loan EMIs continue. Children still need education. Parents may depend on financial and medical support. Insurance premiums and household bills remain due, even when the next pay cheque is uncertain.
We spend years building careers and accumulating wealth, often assuming that we will continue earning until we are ready to retire. Yet our ability to earn is itself an asset, and one that can disappear long before retirement age.
The biggest threat to your retirement may not be how much you save after 60. It may be what happens to your savings when you lose your ability to earn at 40.
At a Glance
- Job loss can turn a long-term wealth-building plan into an immediate cash-flow crisis.
- Illness or disability can create a double financial shock: reduced income and higher expenses.
- Social protection in India exists, but eligibility and coverage vary. Do not assume benefits will replace your salary.
- Employer-provided insurance may change when employment ends. Understand your cover before a crisis occurs.
- Emergency savings, insurance and retirement investments serve different purposes and should not be treated as interchangeable.
1. Your Salary Is Not Your Safety Net
A regular salary creates a powerful sense of financial security. You know roughly how much will arrive each month, so you commit to a home loan, school fees, vehicle payments, holidays and investments. Over time, your lifestyle adjusts to your income, and a large part of that income may already be committed before the month begins.
The vulnerability lies in assuming that this arrangement will continue uninterrupted. A company restructuring, an industry slowdown, a health condition or an accident can affect your earning capacity without changing your financial commitments.
For a salaried professional, job loss is therefore not merely an employment problem. It tests how long the household can function without its usual income. The same applies to business owners and self-employed professionals whose work or business activity may suddenly come under pressure.
Your earning capacity helps build your wealth. Your financial reserves determine how well you can cope when that capacity is disrupted.
2. The Indian Reality: You Cannot Assume Someone Will Replace Your Income
In several Western countries, eligible workers may receive unemployment benefits, disability support or access to public healthcare arrangements. The nature and extent of these benefits differ across countries. Even where support exists, people may face waiting periods, eligibility restrictions, lost income and substantial household expenses.
India also has social protection arrangements. For example, the Employees’ State Insurance (ESI) system provides specified medical and cash benefits to eligible insured workers, including certain sickness and disablement benefits. Other government schemes support particular groups and circumstances.
However, eligibility depends on the applicable rules. Not every professional or household is covered by the same arrangements.
Many Indian professionals therefore depend heavily on personal savings, employer benefits, private insurance and family support. Self-employed people and those outside covered employment arrangements may face a different set of risks.
The point is not that people in Western countries are fully protected or that India has no support. It is that you need to know exactly what protection you qualify for instead of building your financial plan around benefits you may not receive.
The wider structural differences are explored in The Wealth Gap: Why Indian Retirement Planning Falls Behind the West. But beyond the broader retirement gap, there is a more immediate question: what happens to your finances when your ability to earn is interrupted during your working years?
3. Job Loss Can Start a Chain Reaction
Consider a household with a home loan, children in school and ageing parents who receive regular financial support. The main earning member loses their job. Initially, the family may use its savings and expect the situation to resolve within a few months.
As the job search continues, however, difficult choices begin. Investments may be paused, essential purchases postponed, fixed deposits used or mutual fund investments redeemed. If savings run low, borrowing may follow.
What began as a temporary employment setback can gradually damage years of financial progress.
| What happens | Possible financial consequence |
|---|---|
| Salary stops | Savings must fund essential household expenses. |
| EMIs continue | Fixed commitments consume a growing share of available cash. |
| Investments are paused or withdrawn | Long-term wealth creation is interrupted, and market losses may be realised. |
| Emergency savings run low | The household may resort to expensive borrowing or sell assets under pressure. |
| The job search takes longer than expected | Retirement contributions and other long-term goals may suffer for years. |
The danger is not limited to the months without a salary. A prolonged interruption can reduce the time available to rebuild savings and benefit from investment compounding before retirement. A household may eventually recover its income but never fully restore the financial position it might otherwise have achieved.
4. When Illness or Disability Takes Away Your Ability to Earn
Job loss can be financially devastating, but there is an important difference between unemployment and a condition that prevents you from returning to work.
In the first situation, you may be able to resume earning once you find another role. In the second, your earning capacity may remain reduced for months or years, or change permanently.
A serious illness, accident or disability can affect more than the person experiencing it. The household may face treatment costs, rehabilitation expenses, changes to the home, transport needs or additional care. A spouse may need to reduce working hours or leave employment to provide support. The family may also lose the employer-linked benefits attached to the affected person’s job.
This is why health insurance alone cannot address every financial consequence of illness or disability. Health insurance pays for eligible expenses according to the policy terms. It does not automatically replace lost salary, compensate for every future cost or guarantee an income for dependants.
Depending on your circumstances, personal accident or disability cover, life insurance for those with dependants, accessible savings and a realistic plan for reduced income may all have a role. The important step is to understand what each arrangement covers and what remains your responsibility.
The financial pressure can also arise before an insurance claim is settled. GreySmiles’ guide to Managing Medical Emergencies and Hospitalisation Cash Flows explains why accessible reserves matter when medical expenses arise or costs fall outside insurance coverage.
5. What Would Six Months Without Income Actually Cost You?
Consider a hypothetical household whose essential monthly expenses total ₹1.5 lakh. These include housing costs, groceries, utilities, school-related expenses, insurance premiums, loan repayments and necessary family support.
The household’s regular salary stops, and it takes six months to secure another job.
| Essential monthly expenditure | ₹1,50,000 |
| Six months of essential expenditure | ₹9,00,000 |
| Additional medical or job-search costs | Not included |
| Minimum cash requirement in this illustration | ₹9,00,000 |
This is an illustration, not a recommended reserve for every household. It excludes discretionary spending and additional medical costs, and assumes there is no replacement income during the period. The actual amount required will depend on household commitments, other earners, available benefits and the time it takes to return to work.
Now consider what happens if the interruption lasts a year, or if the affected person cannot return to the same level of employment. The financial requirement can grow substantially, while the household’s ability to replenish its savings may be reduced.
The right question is not simply whether you have investments. It is how much of your household’s essential expenditure you can meet without selling long-term assets or taking on expensive debt.
6. Your Emergency Fund and Retirement Corpus Must Have Different Jobs
Many people treat their investments as one large pool of wealth. When a crisis arises, they assume they can simply withdraw whatever is needed.
That approach can be costly when money intended for retirement has to cover expenses that should ideally have been funded by a separate reserve.
An emergency fund provides accessible money when income is interrupted or an unexpected expense arises. A retirement corpus is intended to support living costs over many years after employment income ends. Health insurance and other protection arrangements serve different purposes again.
These resources are connected, but they are not interchangeable. If every financial shock is funded from the retirement corpus, the amount left for later life can shrink just when the need for financial independence is approaching.
This is also why protecting long-term savings matters. GreySmiles discusses this in Smart Strategies to Fill Gaps in Your Retirement Corpus. Before deciding how to bridge a shortfall, it is important to understand which risks your existing financial arrangements can and cannot absorb.
7. What Should You Put in Place Before a Crisis?
You cannot eliminate every risk, and no financial plan can guarantee that a job loss or disability will be manageable. You can, however, reduce the likelihood that one disruption will destabilise your entire household.
Build a reserve around essential expenses
Start by calculating what your household must spend each month, rather than using your salary as the starting point. Include loan repayments, food, utilities, school expenses, insurance premiums and essential support for dependants.
A reserve covering three to six months of essential expenditure can be a starting point. Households with a single earner, volatile income or substantial responsibilities may need more.
Understand your social security and employment benefits
Check whether you are covered by ESI or another applicable arrangement and establish which benefits you qualify for. Understand your employment contract, notice-period provisions, severance terms and any relevant disability benefits.
Do not assume that a scheme applies to you simply because it exists.
Review health and disability protection before you need it
Check the limits, exclusions, waiting periods and conditions of your health insurance. Understand what happens to employer-provided cover when employment ends.
If your household depends on your income, examine whether additional disability, accident or life insurance is appropriate for your circumstances.
Keep long-term investments from becoming your first line of defence
Maintain accessible savings for short-term disruption so you are less likely to sell long-term investments under pressure. Review high-cost debt and avoid committing every salary increase to new fixed expenses.
A lower level of mandatory expenditure can give you more flexibility when income changes.
It is also worth considering whether your household has become too dependent on one source of income. GreySmiles explores this related concern in Stable Job, Great Salary: Why Do You Still Need a Second Income Stream?
Prepare for a prolonged interruption, not just a short gap
Think beyond a three-month job search. Consider what would happen if your recovery took a year, your next job paid less or you needed to change careers.
If other family members earn, understand how much of the household’s essential expenditure their income could cover. Have a plan for reducing discretionary spending without immediately sacrificing healthcare, essential education or long-term security.
8. Start With Three Numbers
Before reviewing investments or considering additional insurance, establish three basic numbers:
- Your household’s essential monthly expenses.
- Your readily accessible savings.
- The income that would remain if the main earner could not work.
Together, these numbers give you an initial picture of how exposed your household is. They are often more useful in a crisis assessment than looking at total net worth, which may include property and investments that cannot be accessed quickly without financial consequences.
Next, review your insurance and employment benefits, including what changes when a job ends. Set a realistic emergency-reserve target and identify the steps needed to reach it.
Only then assess whether your long-term investments are being asked to do too many jobs at once.
The GreySmiles Take
Your career is not guaranteed to continue uninterrupted, even if you are experienced, responsible and good at what you do. Illness and disability can affect anyone, while economic conditions and business decisions can change beyond your control.
Financial resilience begins when you stop assuming that income will always arrive and start building a plan for the possibility that it will not.
Planning for these risks is not about living in fear or keeping every rupee idle. It is about giving yourself time, protecting the people who depend on you and preserving as much of your long-term financial progress as possible.
The real test of financial planning is not whether everything goes according to plan. It is whether your family can withstand the things that do not.
Frequently Asked Questions
How much emergency savings should an Indian professional have?
A reserve covering three to six months of essential household expenditure can be a starting point. A larger reserve may be appropriate if you have one income earner, significant loan commitments, dependants or uncertain employment. Calculate your own essential expenses rather than applying a fixed amount to every household.
Does India provide unemployment benefits?
Some eligible workers may qualify for benefits through specific social security arrangements, including applicable ESI provisions. Coverage is not universal, and scheme rules and eligibility conditions matter. Check current official guidance and your own employment status rather than assuming that a benefit will be available.
Does health insurance protect me if I lose my job?
Health insurance generally covers eligible healthcare expenses under the policy terms; it does not replace lost salary. Employer-provided cover may also change when employment ends. Review your policy and continuation options before a crisis occurs.
Can disability insurance replace my full income?
Not necessarily. Benefits depend on the policy, the definition of disability, exclusions, waiting periods, benefit limits and claim conditions. Review the wording carefully and consider how your household would manage if income were reduced for an extended period.
Should I use retirement savings to pay household expenses after job loss?
Sometimes withdrawals may be unavoidable, but they can reduce the resources available for later life and affect investment outcomes. Accessible emergency savings and appropriate protection can reduce the need to rely on retirement investments for short-term crises.
Sources and References
- Employees’ State Insurance Corporation (ESIC) — official information on eligibility and applicable medical, sickness and disablement benefits.
- Ministry of Labour and Employment, Government of India — official information on social security schemes and worker protection.
Disclaimer: This article is for general information and educational purposes. Government benefits and insurance coverage depend on eligibility, current rules and individual policy terms. Verify the latest requirements with the relevant authority, employer or insurer. This article is not personalised financial, legal, medical or insurance advice.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.