Author: Ruchit Mohan is a legal professional with over six years of experience in litigation and corporate legal practice. An alumnus of Jindal Global Law School, with executive education from Harvard Law School, he writes on legal and regulatory issues, with a focus on property rights, senior citizens’ welfare and financial security.
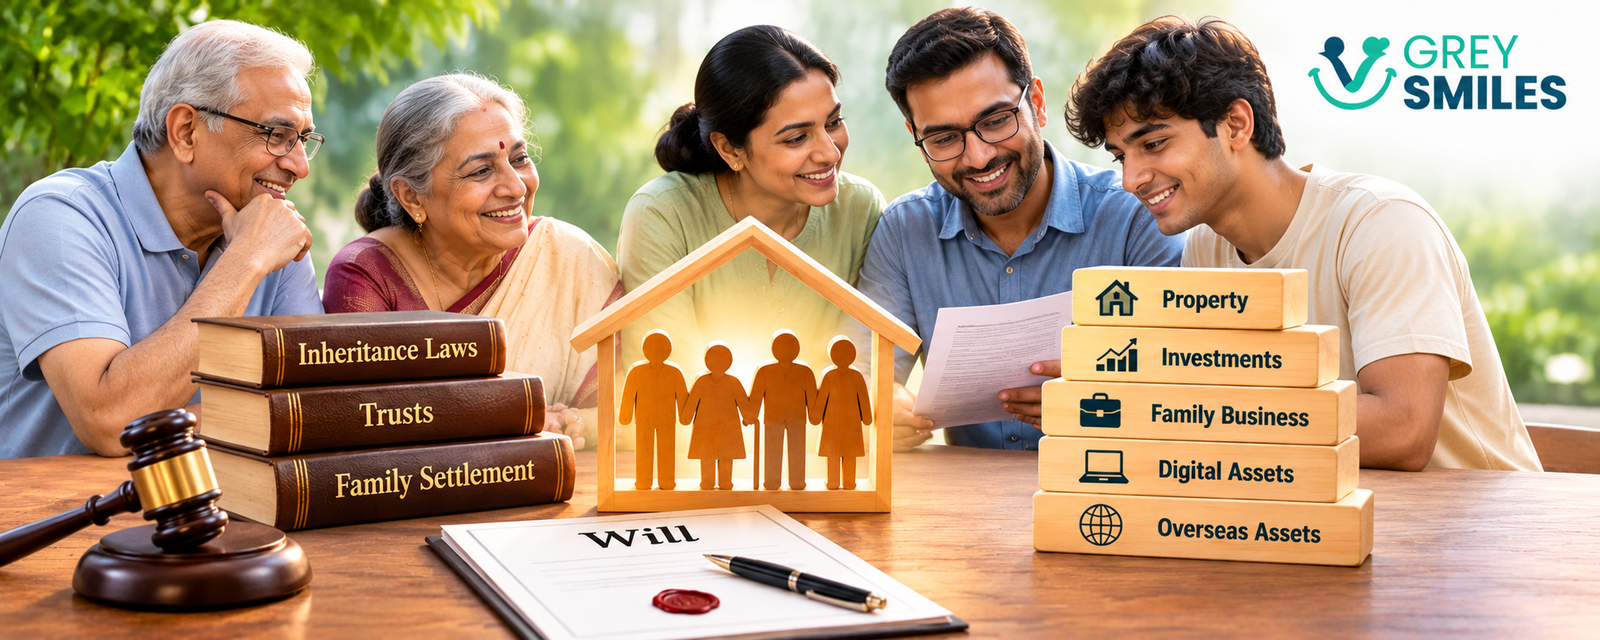
Family succession planning in India is often approached as a legal exercise that begins and ends with writing a Will. An individual decides who should receive their assets, records those wishes and assumes that the family’s financial future has been taken care of. However, transferring wealth successfully across generations requires considerably more preparation.
At a Glance
- Family succession planning in India goes beyond writing a Will. It involves understanding ownership, organising assets and preparing for their eventual transfer.
- A family’s succession arrangements must reflect the applicable personal law, actual ownership interests and the nature of its assets.
- Wills, family settlements, private trusts and business governance arrangements serve different purposes and should work together where appropriate.
- Property, investments, family businesses, digital holdings and overseas assets may each require different succession arrangements.
- Open family conversations and organised documentation can reduce uncertainty and help prevent avoidable disputes.
- A periodic review is essential because family circumstances, assets and legal requirements change over time.
Consider a family that has spent three decades building financial security. It owns a home, has accumulated investments, runs a family business and has created savings for the next generation. The parents may have clear ideas about how this wealth should eventually be distributed. Yet the family may have no consolidated record of its assets, no clarity about who will manage the business, no arrangements for supporting financially dependent members and no common understanding of the responsibilities that accompany inherited wealth.
Even when a valid Will exists, these practical questions do not automatically disappear. Assets may be held through different legal structures, ownership may involve several family members and the administration of an estate may require coordination between institutions, professionals and beneficiaries.
The larger objective of succession planning is therefore not simply to decide who receives what after someone dies. It is to prepare the family for an orderly transition of ownership, responsibility and financial decision-making, while respecting the rights of everyone concerned.
A well-designed succession plan brings together legal documentation, financial organisation, family communication and long-term continuity. It protects not just the wealth created by one generation, but also the ability of the next generation to preserve and manage it responsibly.
1. Understanding the Legal Foundations of Succession in India
India does not follow one uniform succession framework for every individual and every asset. The applicable rules can depend on personal law, the nature of the property, the circumstances of the marriage and the relevant statutory provisions.
Some of the principal legal frameworks include:
- The Indian Succession Act, 1925: Contains provisions concerning testamentary succession, intestate succession for specified communities, administration of estates and related matters, subject to its scope and exceptions.
- The Hindu Succession Act, 1956: Governs intestate succession among Hindus, Buddhists, Jains and Sikhs and contains provisions concerning coparcenary property.
- The Muslim Personal Law (Shariat) Application Act, 1937: Provides for the application of Muslim personal law in specified matters, including intestate succession, subject to the applicable legal framework.
- The Special Marriage Act, 1954: Contains provisions that can affect the succession regime applicable to certain marriages.
The distinction is important because testamentary freedom and inheritance entitlements are not identical across all personal laws. For example, Muslim testamentary dispositions are subject to specific restrictions under Muslim personal law, including the general one-third rule in relevant circumstances, subject to applicable principles and the consent of heirs.
Families should therefore establish which legal framework applies before deciding how their estate should be structured. A document or arrangement that works for one family may not have the same legal effect for another.
For estates involving substantial property, multiple beneficiaries, business interests or cross-border assets, professional legal advice should be obtained at the planning stage rather than after a dispute arises.
2. Begin With an Asset and Ownership Audit
Before discussing distribution, a family needs to understand what it actually owns. This sounds straightforward, but financial assets and property accumulated over several decades can be spread across institutions, companies, documents and different ownership structures.
Some families have investments that were opened many years ago, property documents held by different members, business interests recorded in company registers and financial accounts that have not been reviewed for years. Without a consolidated picture, it becomes difficult to prepare a reliable succession plan.
What should the family inventory include?
| Asset category | What to establish |
|---|---|
| Residential and commercial property | Title documents, ownership interests, mortgages, encumbrances and related agreements. |
| Bank deposits and savings | Institution details, account ownership, balances and relevant documentation. |
| Investments | Mutual funds, shares, bonds, demat holdings and other securities. |
| Insurance and retirement assets | Policies, pension benefits, provident fund interests and relevant claim documentation. |
| Business interests | Shareholding, partnership interests, agreements, liabilities and management responsibilities. |
| Digital assets | Online investments, digital businesses, domain names, intellectual property and relevant access arrangements. |
| Overseas holdings | Foreign property, investments, accounts and applicable cross-border requirements. |
The inventory should also record the legal owner, the location of the original documents, outstanding liabilities and the person responsible for maintaining each record.
It is useful to distinguish between the market value of an asset and the ownership interest that can legally be transferred. A property valued at ₹2 crore, for example, may involve multiple ownership interests or an outstanding mortgage. The full market value should not automatically be treated as the estate of one individual.
Why this exercise matters
An asset audit creates a common starting point for the family and its professional advisers. It helps identify missing documentation, unclear ownership, forgotten investments and potential administrative difficulties.
It also makes it easier to estimate the family’s overall financial position, assess liabilities and consider whether the intended distribution of wealth is practical.
3. Designing a Will That Reflects the Family’s Actual Position
A Will remains an important part of succession planning. It records an individual’s testamentary intentions and can provide directions for the distribution of assets that the person is legally entitled to dispose of.
However, a Will should be prepared as part of the wider succession plan rather than as an isolated document.
Under the Indian Succession Act, 1925, provisions including Sections 59, 61 and 63 address testamentary capacity, circumstances affecting the validity of a Will and the execution and attestation requirements for Wills governed by those provisions. The applicable formalities must be considered in the context of the relevant personal law.
Important considerations while preparing a Will
- Testamentary capacity: The person making the Will should have the legal capacity to understand the nature and consequences of the document.
- Free and informed intention: The document should reflect the testator’s genuine wishes and should not be the result of fraud, coercion or undue influence.
- Accurate asset descriptions: Assets and ownership interests should be identified clearly, without attempting to dispose of property that belongs to someone else.
- Beneficiary identification: Beneficiaries should be identified unambiguously, with appropriate provisions for relevant contingencies.
- Executor appointment: The Will may appoint an executor to carry out its provisions and administer the estate.
- Proper execution: Signing and attestation requirements should be followed in accordance with the applicable law.
- Safe custody: The original document should be preserved securely, and appropriate arrangements should be made so that it can be located when required.
Registration of a Will is generally not compulsory. It may provide useful supporting evidence, but registration alone does not establish that the Will is genuine, voluntary or legally valid.
A relevant legal development: Changes to probate requirements
The Repealing and Amending Act, 2025 (Act No. 37 of 2025), received Presidential assent on 20 December 2025 and was published in the Gazette of India on 21 December 2025. It omitted Section 213 of the Indian Succession Act, 1925, along with consequential amendments to related provisions.
This removed the specific statutory restriction previously imposed by Section 213 on establishing certain rights as executor or legatee without obtaining probate or letters of administration in the circumstances covered by that provision.
However, the change should not be interpreted as making every Will automatically acceptable or eliminating the possibility of probate proceedings. Questions concerning the genuineness, execution, interpretation and ownership of assets may still require judicial determination. Other legal and procedural requirements also remain relevant.
Families should therefore avoid relying on older blanket statements that probate is compulsory in every relevant case, while also avoiding the assumption that probate and estate administration have become unnecessary.
The appropriate course depends on the estate, applicable law, location of assets and circumstances involved.
4. Family Conversations: The Often-Missing Part of Succession Planning
Legal documents can establish important rights and responsibilities, but they cannot always resolve differences in expectations within a family. Many disputes begin with assumptions that were never discussed while the people concerned were alive and able to explain their intentions.
A parent may believe that one child should continue running the family business, while another expects an equal role. One child may have contributed financially to a family property, while another may have provided years of care to ageing parents. A family may have made informal promises about financial support that were never documented.
These situations require more than legal paperwork. They require a thoughtful conversation about expectations, responsibilities and the family’s long-term priorities.
What should families discuss?
- Financial expectations: What are the broad intentions regarding the family’s wealth and its future use?
- Dependent family members: How will financially dependent children, spouses or other family members be supported?
- Business responsibilities: Who is interested in managing the business, and who would prefer to remain a financial beneficiary?
- Care responsibilities: Are there family members whose future care or support requires specific arrangements?
- Decision-making: Who will make important financial and administrative decisions when the current decision-makers are no longer available?
- Disagreement resolution: How will the family approach differences of opinion before they become formal disputes?
These discussions do not require parents to disclose every financial detail or make immediate decisions about distribution. The purpose is to reduce uncertainty and ensure that important responsibilities are understood.
For families, the timing matters. Conversations held calmly and voluntarily while everyone can participate are generally more constructive than discussions initiated during illness, bereavement or a financial emergency.
5. Family Settlements: Creating Clarity Around Shared Interests
Some families accumulate property and business interests over several generations. Over time, different branches of the family may develop competing expectations about how these assets should be used, managed or divided.
A family settlement can sometimes provide a practical mechanism for resolving existing or anticipated disputes concerning family property.
In Kale v. Deputy Director of Consolidation (1976), the Supreme Court recognised bona fide family arrangements as a legitimate means of resolving disputes and claims relating to family property.
A family settlement may be relevant where family members need to agree on:
- How inherited family assets should be divided or managed.
- How different branches of a family should deal with shared interests.
- How an existing family business should be reorganised.
- How competing claims or expectations can be resolved.
- Whether certain family members should receive assets while others receive alternative financial consideration.
Such arrangements must be voluntary and legally sustainable. A family settlement cannot simply be used to bypass statutory inheritance rights or third-party interests.
Registration and stamp-duty requirements should also be examined. A memorandum recording an arrangement already completed may be treated differently from an instrument that itself creates, declares or extinguishes rights in immovable property. Applicable state law and the specific drafting matter.
The objective should be clarity and a durable agreement, not merely a quick informal understanding.
6. Private Trusts: When Wealth Needs a Longer-Term Structure
For some families, a direct transfer of assets to individual beneficiaries may not be the most suitable arrangement. This can be particularly relevant where beneficiaries are minors, require continuing financial support or may not be ready to manage substantial assets independently.
A private trust may offer a structured way to hold and administer assets for specified beneficiaries, depending on its design and the applicable law.
Under a trust arrangement, the trustee holds and administers trust property in accordance with the terms of the trust, for the benefit of the beneficiaries or the permitted purpose. The Indian Trusts Act, 1882, provides the statutory framework for private trusts within its scope and subject to its exclusions.
When might a private trust be considered?
- Where assets need to be administered for minor children.
- Where a beneficiary requires long-term financial support.
- Where wealth is intended to be distributed in stages rather than transferred immediately.
- Where the family wants a structured arrangement for managing specified assets.
- Where continuity of administration across generations is an important objective.
For example, parents may want to provide for a child’s education, healthcare and living expenses over several years rather than transferring a substantial amount at once. A properly structured trust may provide a mechanism for doing so.
However, trusts are not automatically suitable for every family. Their creation and administration can involve legal drafting, registration, stamp duty, taxation, trustee responsibilities and continuing costs. The implications depend on the nature of the assets, the beneficiaries and the trust structure.
A private trust should therefore be considered only after obtaining appropriate legal and tax advice. It should not be treated as a universal substitute for a Will or as a guarantee against inheritance disputes.
7. Family Business Succession: Protecting Continuity Beyond Ownership
Family businesses present a distinct succession challenge. The death or incapacity of a founder can affect not only the ownership of the business but also its management, employees, customers, suppliers, lenders and day-to-day operations.
In many Indian family businesses, the founder remains the central decision-maker for decades. Important relationships may depend on personal trust, operational knowledge and informal arrangements. If these responsibilities are not transferred gradually, the business can become vulnerable at a critical moment.
Business succession should therefore be considered separately from the inheritance of business ownership.
Five questions every family business should address
- Who will lead the business? Identify the person or team capable of taking responsibility for operations and strategic decisions.
- Who will own the business? Clarify the intended ownership structure and how the interests of different family members will be addressed.
- Who will make key decisions? Establish appropriate authority for banking, contracts, borrowing, investments and major business commitments.
- How will family disagreements be handled? Consider governance mechanisms, shareholder arrangements and dispute-resolution provisions.
- What happens if the intended successor cannot take over? Develop an alternative leadership and continuity plan.
Important arrangements to consider
Depending on the business structure, families may need to review:
- Articles of Association and shareholder agreements.
- Partnership deeds and related agreements.
- Board composition and decision-making powers.
- Share-transfer and buy-sell arrangements.
- Valuation mechanisms and exit provisions.
- Banking mandates and authorised signatories.
- Key management responsibilities and operational documentation.
A Will may address the inheritance of an individual’s business interest, but it does not automatically provide an operational continuity plan. Company law, contractual arrangements and the relevant constitutional documents must be considered together.
For a business that has taken decades to build, succession should be a gradual process of preparing people, systems and governance arrangements rather than an event triggered by the founder’s departure.
8. Digital Assets and Overseas Wealth: Planning for a More Complex Estate
Family wealth is increasingly spread across physical property, financial institutions, digital platforms and international jurisdictions. This creates additional administrative and legal considerations that may not be covered by conventional estate planning.
Digital assets
Digital assets may include:
- Online investment and trading accounts.
- Digital wallets and cryptocurrency holdings.
- Websites, domain names and online businesses.
- Digital intellectual property, royalties and monetised content.
- Important financial records stored through digital platforms.
Families should maintain a secure inventory of significant digital holdings and understand the relevant platform procedures for dealing with them after death.
Passwords, PINs, private keys and one-time passwords should not be casually included in a Will or stored in an unsecured document. Appropriate secure-access arrangements should be established separately.
Cross-border assets and NRI families
Families with members living overseas or assets held outside India need to consider additional legal and regulatory requirements.
Relevant questions can include:
- Where is the asset legally situated?
- Which jurisdiction’s succession rules may apply?
- Does the individual have assets in more than one country?
- Will a Will executed in one country be recognised in another?
- What documents will be required to transmit overseas assets?
- Are there FEMA, tax or repatriation considerations?
Succession law and foreign-exchange regulation serve different purposes. FEMA may become relevant when inherited assets are held, transferred or repatriated across borders, but it does not independently determine who inherits an asset.
Where an estate spans multiple jurisdictions, separate professional advice may be necessary in the relevant countries. A coordinated approach can help avoid contradictory documents and unnecessary administrative complications.
9. Organising Estate Records and Administration
A succession plan can be legally sound and still become difficult to implement if the family cannot locate important records or identify the institutions holding its assets.
Documentation and administration should therefore form a separate part of the family’s succession exercise.
Maintain a secure central record
The family should maintain an organised record of:
- Wills and related estate-planning documents.
- Property title deeds and important agreements.
- Banking and investment institution details.
- Insurance and retirement-related documentation.
- Business ownership and governance records.
- Trust deeds and trustee information, where applicable.
- Details of executors, professional advisers and relevant authorised representatives.
- Information about significant digital and overseas holdings.
This does not mean that every family member should have unrestricted access to confidential financial information. The objective is to establish secure custody and ensure that the appropriate authorised person can locate the records when required.
Families should also understand that different legal documents serve different administrative purposes. A legal heir certificate, succession certificate, probate or letters of administration may be relevant in different circumstances. The appropriate document depends on the asset, applicable law and the institution or authority involved.
For a detailed explanation of the distinction between two commonly requested documents, see GreySmiles’ guide: Legal Heir vs Succession Certificate: Key Differences.
10. A Practical Family Succession Planning Framework
Families do not need to establish complicated legal structures immediately. A sensible starting point is to work through a sequence that identifies the gaps, clarifies priorities and brings the necessary arrangements together.
| Step | Action | Intended outcome |
|---|---|---|
| 1 | Prepare an asset and ownership inventory. | Understand the family’s actual financial and legal position. |
| 2 | Identify the applicable succession laws. | Establish the legal framework governing the estate. |
| 3 | Prepare or review the Will. | Record testamentary intentions clearly and legally. |
| 4 | Discuss family expectations and responsibilities. | Reduce uncertainty and prevent avoidable disagreements. |
| 5 | Evaluate trusts, settlements and business arrangements. | Provide appropriate structures for complex assets and family needs. |
| 6 | Organise records and administrative access. | Make the estate easier to identify and administer. |
| 7 | Review the arrangements periodically. | Keep the plan relevant as circumstances change. |
When should the plan be reviewed?
A succession plan should not be treated as a one-time exercise. It should be reviewed following significant events such as:
- Marriage, divorce or the birth of a child.
- Death or incapacity of a family member.
- Acquisition or sale of significant assets.
- Changes in business ownership or management.
- Creation or restructuring of a trust or family settlement.
- Major changes in residence or overseas financial holdings.
- Changes in applicable law or regulatory requirements.
A periodic review helps ensure that the documents, ownership records and family arrangements continue to reflect actual circumstances and intentions.
Conclusion: The Real Value of a Family Succession Plan
Families spend decades building financial security, acquiring assets and creating opportunities for the next generation. Yet the arrangements needed to transfer and manage that wealth are often postponed until much later.
The result can be uncertainty about ownership, disagreements over responsibilities, business disruption and unnecessary delays in administering an estate.
Effective family succession planning addresses these issues before they become difficult to resolve. It begins with understanding what the family owns, identifying the applicable legal framework and recording the intentions of the people who have created the wealth.
It then moves beyond documentation to consider family communication, business continuity, the financial needs of dependants and the structures required to manage wealth across generations.
A Will remains an important instrument, but it is not the entire succession plan. The real objective is to ensure that the next generation inherits not only assets, but also clarity about ownership, responsibility and the arrangements needed to preserve that wealth.
GreySmiles Take
A family may spend a lifetime building wealth, but the transition of that wealth to the next generation should not be left to chance.
Succession planning is not simply about deciding who gets what. It is about ensuring that the family understands what it owns, that its legal arrangements reflect its intentions and that the people who eventually take responsibility are prepared to do so.
It is also an opportunity to have important conversations while family members can participate freely and constructively.
The most valuable legacy may not be the wealth transferred, but the clarity and continuity with which it is passed on.
Frequently Asked Questions
1. Is writing a Will sufficient for family succession planning in India?
A Will is an important part of succession planning, but it may not address every issue involving ownership, business continuity, family governance, trusts or the administration of complex assets. A broader plan may be necessary depending on the family’s circumstances.
2. What is the difference between inheritance planning and succession planning?
Inheritance planning generally focuses on the transfer of assets and legal entitlements. Succession planning can take a broader view, including the transfer of responsibilities, business leadership, asset administration and continuity across generations.
3. Can a family settlement be used instead of a Will?
A family settlement and a Will serve different purposes. A family settlement may resolve existing or anticipated disputes concerning family property, while a Will records testamentary intentions. One should not automatically be treated as a substitute for the other.
4. When should a family consider creating a private trust?
A private trust may be considered where a family needs structured management of assets, staged distributions or continuing support for specified beneficiaries. Its suitability depends on the assets, beneficiaries, tax consequences, costs and intended objectives.
5. How should family businesses prepare for succession?
Family businesses should identify potential leadership successors, clarify ownership arrangements, document management authority and review shareholder or partnership agreements. Operational continuity should be planned separately from the inheritance of business interests.
6. Does family succession planning apply only to wealthy families?
No. Families with a home, savings, investments, insurance and retirement assets can all benefit from organised succession planning. The complexity of the arrangements should reflect the family’s actual assets and needs.
7. How often should a family succession plan be reviewed?
It should be reviewed periodically and whenever a significant family, financial, legal or business change occurs. The objective is to ensure that the arrangements remain consistent with the family’s current circumstances and intentions.
Sources & References
Legislation
- The Indian Succession Act, 1925.
- The Hindu Succession Act, 1956, including the Hindu Succession (Amendment) Act, 2005.
- The Muslim Personal Law (Shariat) Application Act, 1937.
- The Special Marriage Act, 1954.
- The Indian Trusts Act, 1882.
- The Registration Act, 1908.
- The Companies Act, 2013.
- The Repealing and Amending Act, 2025 (Act No. 37 of 2025).
Important judicial decisions
- H. Venkatachala Iyengar v. B.N. Thimmajamma, AIR 1959 SC 443.
- Kale v. Deputy Director of Consolidation, (1976) 3 SCC 119.
- Vineeta Sharma v. Rakesh Sharma, (2020) 9 SCC 1.
- Shakti Yezdani v. Jayanand Jayant Salgaonkar, 2023 INSC 1076; (2024) 4 SCC 1.
Official legal resources
- India Code – Government of India legislation repository.
- The Repealing and Amending Act, 2025 – official India Code text.
Related Reading on GreySmiles
- Will, Nominee or Legal Heir: Who Actually Gets Your Money?
- Nominee, Joint Holder or Will? What Each One Actually Does
- Jointly Owned Home After a Spouse Passes Away: Why Your Will Matters
- Legal Heir vs Succession Certificate: Key Differences
- The Unclaimed Wealth Crisis in India: Why Crores Remain Untransferred to Rightful Heirs
Legal and editorial note: This article is intended for general information and awareness. It does not constitute legal, financial or tax advice. Succession arrangements depend on applicable personal law, ownership documents, the nature of the assets and individual circumstances. Readers should obtain advice from appropriately qualified legal and tax professionals before implementing any succession arrangement.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.