Understanding PF and VPF contributions can help strengthen long-term retirement savings.
The Employees’ Provident Fund (EPF) is one of the most widely used retirement savings instruments in India. For salaried employees, it provides a disciplined way to build long-term savings during their working years and can become an important part of the retirement corpus they eventually depend on.
Employees can also choose to contribute more than their mandatory EPF contribution through the Voluntary Provident Fund (VPF). This can be useful for those who want to increase their provident fund savings through a familiar, salary-linked mechanism rather than adding another investment product to their portfolio.
At a Glance
- EPF is a long-term retirement savings mechanism for eligible salaried employees, with contributions made through payroll during their working years.
- VPF allows you to save more by contributing voluntarily above your mandatory employee EPF contribution.
- VPF works through your provident fund account rather than being a separate market-linked investment such as a mutual fund.
- The EPF interest rate is declared from time to time. For FY 2025–26, the Central Board of Trustees recommended an interest rate of 8.25%, subject to the applicable government notification and crediting process.
- Tax benefits have conditions and limits. The Section 80C deduction limit is an overall limit and is not an additional ₹1.5 lakh deduction exclusively for VPF.
- VPF can strengthen retirement savings, but putting too much into it can reduce liquidity and leave less money available for other financial needs.
Understanding the Provident Fund System
What is the Employees’ Provident Fund (EPF)?
The Employees’ Provident Fund is a government-backed retirement savings mechanism for eligible employees. Contributions are made regularly through payroll, creating a pool of long-term savings that can support an employee after the end of their working life.
Under the standard EPF contribution framework, the employee contribution is generally 12% of basic wages plus dearness allowance. The employer also contributes, although the employer’s contribution is distributed between EPF and the applicable pension component according to the prevailing EPFO rules.
The interest rate on EPF is declared from time to time. For FY 2025–26, the Central Board of Trustees recommended an interest rate of 8.25%, subject to the applicable government notification and crediting process. EPFO
What is the Voluntary Provident Fund (VPF)?
The Voluntary Provident Fund is an optional contribution made by an employee over and above the mandatory EPF contribution. It allows an employee to direct a larger portion of their salary towards long-term provident fund savings.
VPF is not a separate investment account like a mutual fund or PPF account. The additional employee contribution forms part of the provident fund arrangement and earns the rate of interest declared for EPF. To understand how these savings options differ, see our guide to EPF vs PPF.
Subject to the applicable EPF rules and the employer’s payroll arrangements, an employee can contribute up to 100% of basic wages and dearness allowance through the employee contribution route. The employer is not required to match the additional VPF contribution.
This makes VPF particularly relevant for salaried employees who have surplus monthly income and want to increase their long-term provident fund savings without taking on additional market risk.
Managing Your Provident Fund
Managing your provident fund is not simply about contributing as much as possible. The more useful approach is to understand how EPF and VPF fit into your wider retirement planning and whether the contribution level works for your present financial situation.
1. Set Clear Financial Goals
Start by deciding what you want your provident fund savings to achieve. For many employees, the primary objective will be retirement, while others may also have specific long-term financial commitments in mind.
Look at your EPF and VPF alongside your other retirement savings rather than considering them in isolation. Your eventual retirement corpus may come from several sources, and understanding how each one contributes can make your planning more realistic.
2. Budget for Your Contributions
Increasing your VPF contribution directly reduces the amount of salary available for your monthly spending. Before increasing it, review your regular expenses, emergency savings, insurance premiums, debt repayments and other financial commitments.
A contribution that looks attractive on paper should still leave enough flexibility in your monthly cash flow. Retirement savings need to remain sustainable over several years rather than becoming a financial burden after a few months.
GreySmiles Take
More retirement savings is not automatically better retirement planning. VPF can be useful when you have surplus income and want disciplined long-term savings. The right contribution is one that strengthens your retirement position without leaving you short of liquidity today.
3. Monitor Your EPF and VPF Balance
Keep track of your provident fund balance periodically. This gives you a clearer picture of how much you have accumulated and how much of your eventual retirement corpus may already be coming from EPF and VPF.
Regular checks can also help you identify discrepancies or account-related issues early, rather than discovering them when you change jobs or approach retirement.
4. Use EPFO Online Services
EPFO provides online services that allow members to access information relating to their provident fund account and carry out various account-related activities. Keeping your UAN and other relevant details properly updated can make account management and future transfers easier.
It is worth checking your account periodically rather than waiting until retirement or a job change to discover that an important detail needs correction.
5. Review Your Contribution Every Year
A VPF contribution that works well at one stage of your career may not remain appropriate forever. Salary changes, home loans, children’s education, family responsibilities and your retirement timeline can all affect how much you should set aside.
Review your contribution at least once a year and whenever there is a major change in your financial circumstances. This keeps your provident fund contribution aligned with your wider financial plan.
Pros and Cons of VPF
VPF can be an attractive option for disciplined long-term saving, but it is not automatically suitable for everyone. Its advantages need to be weighed against the impact on liquidity, monthly cash flow and the role of other investments in your overall financial plan.
Pros of VPF
1. Disciplined Long-Term Saving
Because VPF is deducted directly from salary, it can make saving easier. The money is set aside before it becomes part of your monthly spending, reducing the temptation to spend it elsewhere.
2. Interest at the EPF Rate
VPF contributions earn interest at the same rate declared for EPF. This can make VPF attractive to employees looking for a relatively predictable long-term savings mechanism rather than a market-linked investment.
3. Potential Tax Benefits
Eligible provident fund contributions can qualify for tax deduction under Section 80C of the Income Tax Act when the old tax regime applies and the relevant conditions are met. The overall Section 80C limit is ₹1.5 lakh across eligible investments and payments, so this should not be treated as a separate ₹1.5 lakh deduction available only for VPF.
The tax treatment of provident fund interest also has specific rules. Interest relating to employee contributions above the prescribed annual threshold can become taxable, so employees making large VPF contributions should consider the tax implications rather than assuming that the entire balance will always enjoy the same tax treatment.
4. Compounding Over Time
Regular contributions combined with interest can build a meaningful retirement corpus over a long working life. The effect of compounding becomes particularly relevant when contributions continue for many years.
This is one reason why starting early can make a difference. Even a moderate additional contribution, maintained consistently over a long period, can add meaningfully to retirement savings.
5. Convenient for Salaried Employees
Once VPF is enabled through the employer’s payroll system, contributions can happen automatically each month. There is no need to remember to make a separate investment every time you receive your salary.
6. Portability Across Jobs
Provident fund balances can generally be transferred when an employee changes jobs, subject to the applicable EPFO processes and account requirements. This makes the provident fund useful as a continuing retirement savings mechanism across a working career.
Cons of VPF
1. Limited Liquidity
Provident fund savings are designed primarily for long-term financial security. Although withdrawals and advances are permitted in specified circumstances, EPF and VPF should not be treated like a regular savings account that can be accessed freely whenever money is needed.
If you are likely to need the money in the near term, directing too much of your salary towards VPF may not be appropriate.
2. Opportunity Cost
VPF can provide stability within your retirement savings, but it is only one possible way to build long-term wealth. Depending on your circumstances and risk tolerance, other investments may have a different role to play in your overall financial plan.
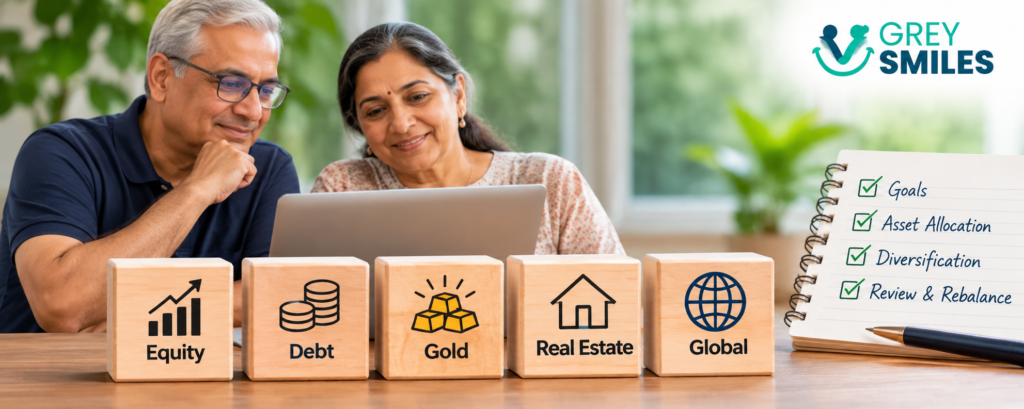
Putting a very large proportion of your retirement savings into one instrument can therefore reduce diversification. The longer your investment horizon, the more important it is to look at your complete portfolio rather than evaluating VPF on its own.
3. Impact on Monthly Cash Flow
A large VPF contribution can reduce your take-home salary substantially. This may become difficult to sustain if you also have a home loan, children’s education expenses, family responsibilities or other significant financial commitments.
Before increasing VPF, make sure that your present financial needs are adequately covered. Retirement savings should not come at the cost of financial stress today.
4. Interest Rates Can Change
The EPF interest rate is declared from time to time and is not permanently fixed for the entire period of your working life. The rate applicable to your provident fund savings can therefore change over the years.
This is another reason to review your overall savings strategy periodically rather than assuming that one savings instrument will remain equally attractive throughout your career.
5. Tax Benefits Have Limits
VPF should not be selected purely for its tax benefits. The available deduction under Section 80C has an overall limit, and the tax treatment of interest on contributions above the prescribed threshold also needs to be considered.
How VPF Fits Into Your Retirement Plan
VPF can form an important part of your retirement savings, particularly if you have a stable income and sufficient surplus to make additional contributions. At the same time, your provident fund should be viewed alongside your other retirement savings rather than as your only source of retirement income.
If you are trying to understand how much you may need for retirement overall, the GreySmiles Retirement Corpus Calculator can help you look at the larger retirement requirement. VPF can then be considered as one component of the savings needed to meet that requirement. You can also read our guide to calculating your retirement corpus in India.
GreySmiles Take
Use VPF to strengthen your retirement savings, not to replace your retirement plan. A good retirement strategy needs a balance between security, growth, liquidity and diversification. VPF can be an important part of that mix without having to carry the entire burden of your retirement planning.
Conclusion
The Provident Fund can play an important role in building long-term financial security. For salaried employees who have the financial capacity to save more, VPF provides a simple way to increase provident fund savings through an existing salary-linked mechanism.
Its strengths include disciplined saving, the interest rate applicable to EPF and potentially favourable tax treatment subject to the prevailing rules. At the same time, liquidity constraints, changing interest rates, tax limits and the opportunity cost of concentrating too much money in one type of saving need to be considered.
The right VPF contribution will therefore depend on your income, expenses, existing savings, retirement timeline and need for liquidity. The objective should not be to maximise VPF simply because the option is available. It should be to use VPF in a way that supports your broader retirement goals.
Sources & References
For current rules relating to EPF and VPF, refer to the Employees’ Provident Fund Organisation (EPFO). For current tax provisions, refer to the Income Tax Department.
Provident fund rules, interest rates and tax provisions can change, so current official guidance should be checked before making a financial decision.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.