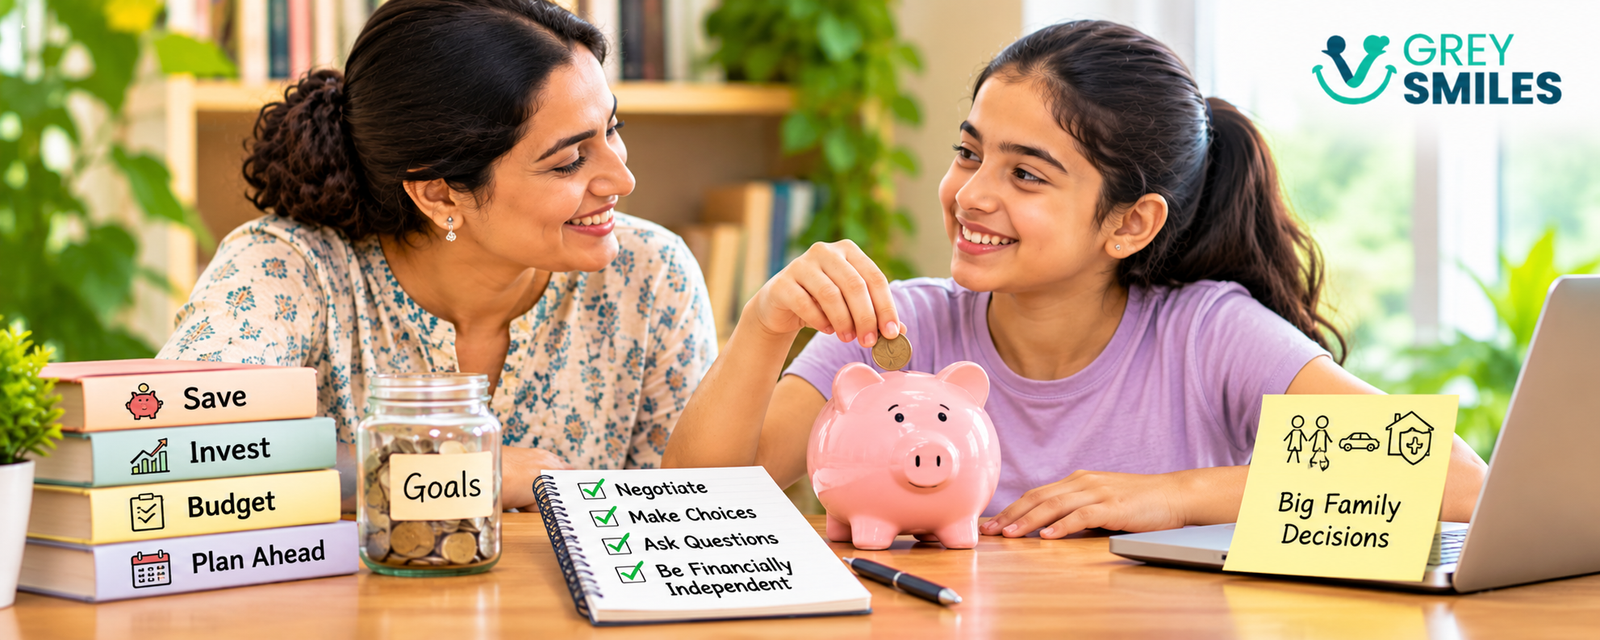
Financial confidence begins at home with everyday money habits, questions and decisions.
Dr. Shruti Gupte: Dr. Shruti Gupte is a financial literacy and entrepreneurship educator with over 13 years of experience, currently serving as Senior Project Manager (Entrepreneurship & Innovation) at IIT Bombay’s Desai Sethi School of Entrepreneurship. She has conducted over 1,000 financial literacy and investor awareness sessions across India. She is co-founder of YFS Academy LLP, a SEBI-certified SMART trainer organisation, and holds a Doctor of Business Administration with research focused on women’s financial literacy in mainstream finance.
Raising Financially Confident Daughters: Money Habits That Start in Childhood
Dr. Shruti Gupte
We praise girls for not asking. Decades later, that praise shows up in their salaries, their savings and their retirement.
She stayed back after one of my investor awareness sessions with a question she said had been bothering her all week.
I will call her Meera. She was twenty-three and very comfortable with money in the way her generation is. She paid for everything on UPI, had started an SIP with her first salary and could explain an expense ratio better than some of the adults in the room. Six months earlier, she and a college batchmate had joined the same firm, in the same role, through the same off-campus interviews. Over lunch that week she had learnt that he was earning ₹40,000 a year more. When HR made the offer, he had said he would like to think about it and had come back with a number. Meera had said thank you and signed the same afternoon.
“It never even crossed my mind that I could ask,” she said. “Why didn’t it?”
We sat in the empty hall and she worked it out aloud. Her younger brother had bargained for a bigger allowance every Diwali, sulked when refused and usually won. When the family bought a car, he went to the showroom. She stayed home to help with lunch for the guests. Shagun envelopes from relatives went into the cupboard at home “for safekeeping”, and she never asked what became of them. Nobody had ever told her not to ask. They had simply praised her, year after year, for not asking. Meera samajhdaar hai. Meera is so sensible. Meera never makes a fuss.
“I thought that was a compliment,” she said, and laughed, though she did not look amused. “I used to be proud of it.”
Meera is a composite of several young women I have met, with details changed. Many readers will recognise her house, because it was theirs. Women may remember being the sensible one. Men may remember being taken to the bank by their father, or asked which car to buy, without noticing that their sister was not. It was rarely cruel and usually done with love, and that is exactly why it sticks. Among older women I hear the same thing in a single sentence, in Hindi, Marathi and English alike: Papa sambhalte the. Father used to handle it. Later it becomes a husband, and later still a son.
If you are a parent or grandparent, this is a story about the girls in your own family and the later years they will have.
At a Glance
- Financial confidence begins at home, long before a girl earns her first salary.
- Children learn money habits through practice, observation and the choices they are allowed to make.
- Being “sensible” should not mean being discouraged from negotiating, questioning or making decisions.
- Giving girls opportunities to handle money, ask for more and participate in family decisions can build confidence that carries into adulthood.
- Financial confidence is not just about knowing how money works. It is about feeling capable of using that knowledge.
- Parents, grandparents and sons have a role in creating a home where girls are encouraged to participate equally in financial conversations.
What being sensible costs
Meera’s ₹40,000 sounds small. Suppose she had invested it every year from twenty-three to sixty and earned 10 per cent a year, a figure used here only for illustration, since market returns are never guaranteed. It would come to about ₹1.3 crore. Inflation would shrink that to roughly ₹15 lakh in today’s money, which is still a great deal to lose by not asking one question, and it leaves out every future raise calculated on her lower salary.
Career breaks work the same way. On the same assumption, a woman who invests ₹60,000 a year from twenty-five to sixty but pauses for five years in her early thirties skips ₹3 lakh of contributions. By sixty the gap in her savings is close to ₹40 lakh, because the years she missed were the ones with the longest time to grow.
And women need their savings to last longer. According to the Sample Registration System’s life tables for 2016–20, an Indian woman who reaches sixty can expect to live another 19.2 years, against 17.5 for a man. Since many women also marry men a few years older, a large share will spend their last years managing money on their own.
The national numbers show the same gap from another side. A National Centre for Financial Education survey for 2020–21 found 21 per cent of Indian women financially literate, compared with 27 per cent of men. The World Bank’s Global Findex 2025 shows Indian women now hold bank accounts at about the same rate as men, which is real progress, but 18 per cent of women account holders made no transaction in the previous year, against 11 per cent of men. Owning an account and using it are still two different things.
Employers are not off the hook. Fair pay is their responsibility, and no amount of childhood training should be needed to get it. But our daughters should not have to lose money while the workplace catches up.
Why childhood matters so much
In 2013, researchers David Whitebread and Sue Bingham at the University of Cambridge reviewed the evidence for the UK’s Money Advice Service. They concluded that by about the age of seven most children understand what money is for and have formed core habits, such as planning ahead and waiting for something they want, that they carry into adult life. It does not mean the door closes at seven. It means the habits start forming far earlier than most of us begin talking to children about money.
My own doctoral research on women’s financial literacy kept returning to a related point. Knowing about money and feeling able to act on that knowledge are separate things, and the second comes only from practice. Meera had the knowledge. What she had never practised was asking.
A Women’s Day advertisement by Paytm in 2021 made a similar point on camera. Watch the Paytm Women’s Day video. Thirty men and women stood in a line and stepped forward for every “yes”. Did you learn to cycle before ten? Can you make your own breakfast? The line stayed mixed. Then the questions turned to money, starting with whether they knew the exact break-up of their salary, and the men moved steadily ahead.
For more on the importance of building money knowledge early, read Improving Financial Literacy in India: Snapshot, Barriers and Practical Solutions.
Five things that would have changed Meera’s answer
Most of what follows costs nothing. It fits a two-room flat as well as a bungalow, and a home with one parent as well as one with four grandparents under the same roof.
1. Put real money in her hands early
A four-year-old who pays at the kirana shop, waits for the change and counts it learns that money is real and that it runs out. A gullak split into three, for spending, saving and giving, teaches her that the rupee spent on sweets today is not there for the cricket bat or storybook she is saving for. When you refuse something, “that isn’t in our plan this month” teaches her that families choose. “We can’t afford it” mostly teaches her to worry.
2. Let her ask, and sometimes let her win
This is the habit Meera never had the chance to build. Give pocket money on a fixed day, and if she thinks it should go up, ask her to make the case. What does it need to cover? What costs more now? What will she take charge of in return? Say yes when the case is good. A girl who has argued for a raise at eleven, and won one, is unlikely to sign her first offer letter without a question.
3. Let her see the numbers grow
A “family bank” makes saving visible. Each time she deposits money with you, add a little of your own, say ₹1 for every ₹10, the way an employer adds to a provident fund, and record the balance on a sheet on the fridge. Later, if you save for her through the Sukanya Samriddhi Yojana, a recurring deposit or a small SIP, open the statement with her once a quarter. Money saved for her is not the same as money she understands. If part of it is in the market, she will see it fall in some months, and learning at sixteen that values go down as well as up is much cheaper than learning it at forty-five.
Parents can also explore teaching children about money and taking responsibility as they grow, rather than simply saving or setting aside money on their behalf.
4. Give her a seat at the table
Think of the car showroom Meera never went to. When the family renews health insurance, takes a loan or buys something large, let her sit in and ask questions. She is not there to decide, only to see how decisions are made and that they can be questioned. The same goes for property. Since 2005, daughters have had the same right as sons to joint family property under Hindu succession law, and in 2020 the Supreme Court confirmed that the right comes with birth and does not end with marriage. Families under other personal laws should find out what applies to them. Many daughters still grow up assuming they will quietly sign away their share. A daughter who has heard property discussed openly at home is far better placed to decide for herself.
5. Watch what you praise
Nobody meant to hold Meera back. Her family simply praised the wrong thing. Praise a daughter for asking well, not for never asking. Notice whether “ask your father” is the answer to every money question at home, and let her watch whichever parent handles the budget, the bills and the investments actually doing it. A mother who has never taken a money decision on her own can still start, and a daughter who watches her mother learn learns too. Sons need all of this as well. Not every boy is a born negotiator, and boys who grow up seeing their sisters handle money make better partners.
If you are Meera
Some of you reading this were the sensible one, and the good news is that asking can be learnt at any age. Before your next appraisal, write a one-page note on what you have delivered and what you think it is worth, and ask. Take a health insurance policy in your own name, check the nominee on every account you hold, and ask your parents, gently but clearly, where the family’s papers are and what your share will be. If you keep everything in fixed deposits and gold because that feels careful, ask whether careful is the same as safe over thirty years. Often it is not.
For the long-term implications of financial autonomy, see When Her Money Is Everyone’s Money: What Happens to an Indian Woman When She Retires?.
For grandparents
Grandchildren often listen to you in a way they do not listen to their parents. Tell them what things cost when you were young and which money mistakes taught you most. If your nominations and will are in order, walk an older grandchild through how you organised them. And grandmothers have a particular story to tell. Many of you were never encouraged to ask either. If you learnt to manage money later in life, perhaps after losing a husband, tell your granddaughter what that was like and what you wish someone had taught you at her age.
The question Meera asked
Meera’s question was a simple one: why had it never crossed her mind? The honest answer is that nobody had ever put it there. For twenty years, every small chance to ask had gone to someone else, or been praised away. The opposite is just as easy to build, one coin, one pocket-money negotiation and one family conversation at a time. Somewhere along the way, nobody told Meera she was allowed to ask. We can tell our daughters now.
The GreySmiles Take
Financial confidence begins with everyday experiences at home. Giving daughters the opportunity to handle money, ask questions, negotiate and participate in decisions can help them carry that confidence into adulthood.
Sometimes the most important money habit we can teach our daughters is simply this: never be afraid to ask.
Frequently Asked Questions
1. How can parents teach daughters about money from a young age?
Parents can start by giving daughters small opportunities to handle money, save for goals, make spending choices, receive pocket money and participate in age-appropriate family financial discussions. Everyday practice helps children develop confidence in handling money.
2. Why is financial confidence important for girls?
Financial confidence helps girls grow into women who are comfortable asking questions, negotiating salaries, making financial decisions, managing savings and taking responsibility for their financial future. Knowing about money is important, but feeling capable of acting on that knowledge matters equally.
3. How can parents encourage daughters to negotiate and ask for what they deserve?
Parents can encourage daughters to express their needs, explain their reasoning and negotiate respectfully from an early age. Allowing them to ask for pocket-money adjustments, discuss purchases and make their case builds confidence that can later translate into salary negotiations and other financial decisions.
4. Should daughters be involved in family financial decisions?
Yes. Involving daughters in age-appropriate discussions about budgeting, insurance, loans, savings and major purchases helps them understand how financial decisions are made. It also reinforces that money-related conversations and decisions are not limited to one member of the family.
Sources
- Office of the Registrar General of India, SRS Based Abridged Life Tables 2016–20.
- National Centre for Financial Education, National Financial Literacy and Inclusion Survey 2020–21 (as reported by NCAER).
- Klapper, L., Singer, D., Starita, L. and Norris, A. (2025), The Global Findex Database 2025, World Bank.
- Whitebread, D. and Bingham, S. (2013), Habit Formation and Learning in Young Children, Money Advice Service, UK.
Investment figures are illustrations at an assumed 10 per cent annual return, compounded annually, with inflation taken at 6 per cent. Market-linked returns are not guaranteed.
Disclaimer: This article is intended for general educational and awareness purposes only. The views and opinions expressed are those of the author and do not necessarily represent the views of GreySmiles. It should not be construed as financial, investment, legal or tax advice. Readers should consider their individual circumstances and consult qualified professionals where appropriate.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.