
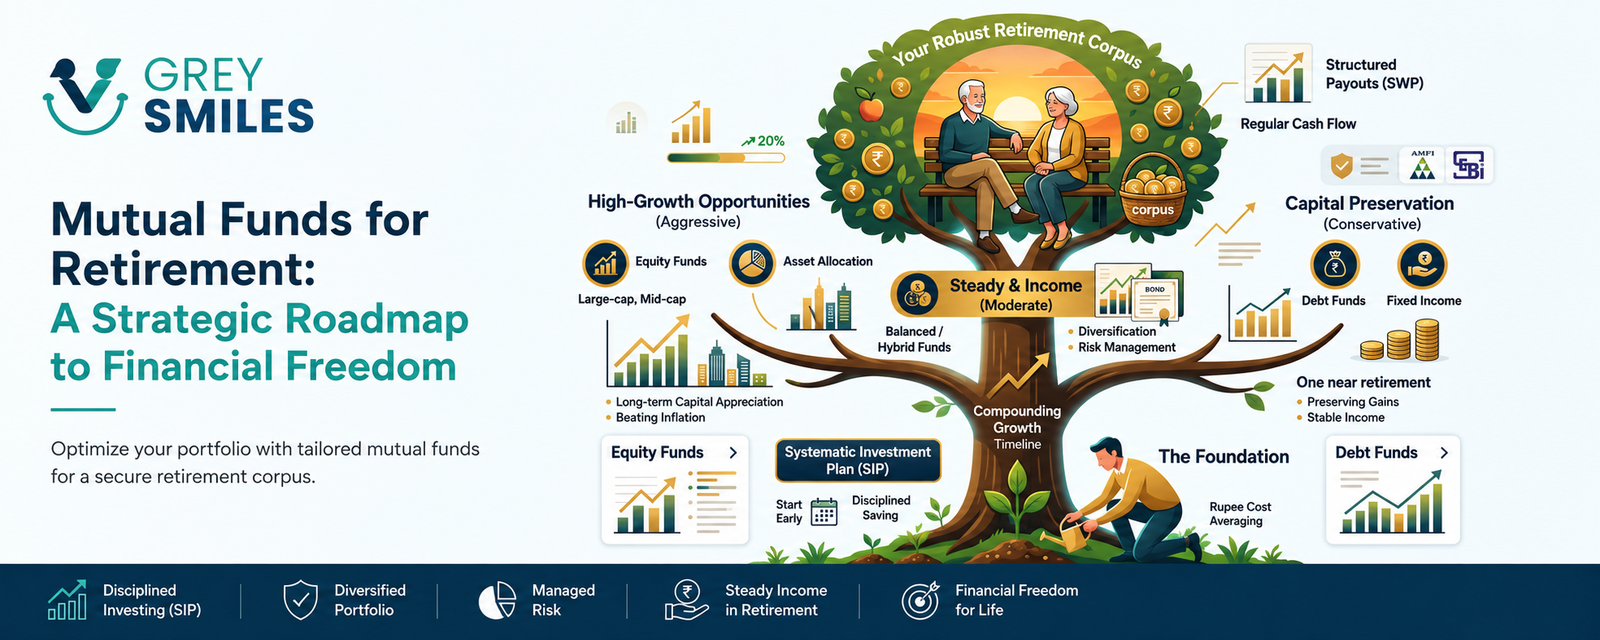
A retirement portfolio can use different mutual fund categories for growth, diversification, stability and income.
For one person, mutual funds may be primarily about long-term growth. For another, they may form part of a diversified portfolio that also includes EPF, PPF, NPS, fixed-income investments or other assets. Closer to retirement, the question changes again: how much of the portfolio can remain exposed to market movements, and how will the money eventually support spending?
At a Glance
- Mutual funds are a retirement-building tool, not a complete retirement plan.
- There is no universally “best mutual fund for retirement”. The right choice depends on your goal, time horizon, risk capacity and existing assets.
- Equity, debt and hybrid funds can perform different jobs within a retirement portfolio.
- A SIP is a way of investing regularly. It does not guarantee returns or make an unsuitable investment suitable.
- As retirement approaches, the focus should gradually include capital stability, liquidity and income, not only accumulation.
- After retirement, an SWP may be useful, but withdrawals need to be considered alongside spending, corpus, other income, taxes and market risk.
- The right number of mutual funds is not the maximum number. Every holding should have a clear purpose.
For investor education and current mutual-fund information, refer to the resources provided by SEBI Investor and AMFI. Mutual fund investments are subject to market risk and returns are not guaranteed.
What Are Mutual Funds for Retirement?
A mutual fund pools money from investors and invests it according to the scheme’s stated objective. Depending on the scheme, that portfolio may contain equities, bonds, government securities, money-market instruments or a combination of assets.
For retirement planning, however, the most important distinction is between the product and the goal.
Your retirement goal comes first. The investment is then selected according to the job it needs to perform.
That distinction matters because a retirement plan may contain several different kinds of assets. Mutual funds can sit alongside EPF, PPF, NPS, deposits, annuities and other investments rather than replacing all of them.
GreySmiles Take
Don’t choose a mutual fund because its name sounds appropriate for retirement. First decide what the money needs to do — grow, diversify, provide stability or eventually support income. Then choose the investment.
Where Do Mutual Funds Fit in a Retirement Plan?
Think of retirement planning as a chain of decisions rather than a search for one investment product.
| Retirement question | What it determines |
|---|---|
| How much will I spend? | Your retirement spending requirement |
| How much do I need? | Your target retirement corpus |
| Where will income come from? | Pension, investments, annuity, withdrawals and other income |
| How should my assets be positioned? | Your overall asset allocation |
| What role should mutual funds play? | The job assigned to each mutual-fund holding |
Start with your expected retirement spending before deciding how much to invest. GreySmiles’ guide on how much you may actually need to spend in retirement can help establish that starting point.
Once the spending requirement is clearer, the next question is the corpus you may need. See the GreySmiles retirement corpus calculation guide before turning to fund selection.
Which Mutual Fund Categories Can Play a Role?
There is no single mutual-fund category that is automatically “for retirement”. Different categories can serve different purposes, and the appropriate choice depends on the investor and the time horizon.
| Category | Possible role | What to think about |
|---|---|---|
| Equity funds | Long-term growth | Market volatility, time horizon and ability to tolerate losses |
| Debt funds | Diversification and portfolio stability | Interest-rate, credit and liquidity risks |
| Hybrid funds | A combination of equity and debt exposure | Actual asset allocation and how it may change |
| Index / passive funds | Broad market exposure | Index tracked, tracking difference and costs |
| Retirement-oriented schemes | A structured investment approach where the scheme provides one | Mandate, asset allocation, lock-in and withdrawal conditions |
The important point is that the category does not determine whether an investment is right for you. The same equity exposure can make sense for one retirement plan and be inappropriate for another.
How Should You Choose Mutual Funds for Retirement?
A better process is to work backwards from the retirement problem.
1. Start With Your Retirement Spending
Before choosing a fund, estimate what retirement may actually cost. Include regular household expenses as well as healthcare, insurance, travel, family support, taxes and irregular expenses.
A retirement portfolio cannot be judged properly without knowing what it eventually needs to support.
2. Establish Your Corpus Requirement
Your retirement corpus is not simply a large number that sounds comfortable. It needs to be considered alongside your expected spending, retirement duration, inflation, other income, healthcare requirements, taxes and the way your assets are invested.
This is why a ₹2 crore portfolio may be more than enough for one household and inadequate for another.
3. Consider How Long the Money Can Stay Invested
Someone in their 30s may have several decades before retirement. Someone approaching retirement may need part of the portfolio much sooner.
The longer horizon can provide greater capacity to live through market fluctuations, but it does not automatically justify taking maximum equity risk. Risk capacity depends on the whole financial situation, not age alone.
4. Decide What Job the Fund Has
Ask a simple question for every mutual fund you own:
“Why is this fund in my retirement portfolio?”
Possible answers might include:
- Long-term growth
- Diversification
- Balancing other assets
- Providing a particular type of market exposure
- Supporting a future withdrawal strategy
If you cannot answer the question, the fund may not have a sufficiently clear role.
5. Look at the Portfolio, Not the Fund Name
Two funds can have similar-sounding names while having different portfolios, risk characteristics, costs and investment strategies.
Look at what the scheme actually owns and understand the mandate before investing. SEBI’s investor education material specifically emphasises understanding the features and risks of securities and matching investments to the investor’s objectives and risk appetite. :contentReference[oaicite:5]{index=5}
6. Consider Costs
Costs reduce the amount of money that remains invested. Expense ratios and other applicable charges therefore matter, particularly over long investment periods.
But cost should not be viewed in isolation. A cheaper fund is not automatically the better fund if it does not perform the role your portfolio requires.
7. Check for Overlap
Owning six or eight mutual funds does not necessarily mean you have a well-diversified portfolio.
If several funds own many of the same companies, you may simply have multiple wrappers around similar exposure.
GreySmiles Advice
A retirement portfolio should be understandable enough for you to explain to yourself. If you cannot explain what each fund is doing, adding another fund is unlikely to solve the problem.
Mutual Funds at Different Stages of Retirement Planning
The role of mutual funds can change as you move closer to retirement.
| Stage | Primary question | What deserves attention |
|---|---|---|
| Early accumulation | How do I build wealth over the long term? | Growth, diversification and investing discipline |
| Mid-career | Am I still on track? | Corpus target, contributions and asset allocation |
| Approaching retirement | How much market risk can I still afford? | Liquidity, diversification and protection of near-term needs |
| Retirement | How will my portfolio support my spending? | Cash flow, withdrawals, taxes, liquidity and market risk |
This is why retirement investing should not be treated as a one-time decision. The portfolio you need at 35 does not necessarily have the same job at 55 or 65.
For a broader look at how investments fit into the retirement journey, see GreySmiles’ retirement asset allocation guide.
SIP: Useful for Discipline, Not a Retirement Strategy
A Systematic Investment Plan, or SIP, allows you to invest a fixed amount into a mutual-fund scheme at regular intervals.
That can be valuable because consistency is difficult to maintain when investing depends on making a fresh decision every month.
But there is an important distinction:
A SIP is a method of investing. It is not a retirement plan.
A SIP does not guarantee returns, eliminate market risk or make an unsuitable fund appropriate. The underlying investment still determines the risk and potential outcome.
What Happens When You Retire?
The investment question changes once you stop earning a salary.
During accumulation, the focus is largely on building the portfolio. In retirement, the portfolio has to coexist with actual spending.
You may therefore need to answer questions such as:
- How much will I need to withdraw each month?
- Which assets should fund near-term expenses?
- How much of the portfolio should remain exposed to growth assets?
- What other income will I receive from pensions, annuities or other sources?
- How will taxes affect withdrawals?
- What happens if markets fall shortly after retirement?
An SWP can be one component of the answer, but it should not be treated as a guaranteed pension.
GreySmiles View
The real retirement question is not “Can my mutual funds give me monthly income?” It is “Can my overall retirement portfolio support the spending I expect, through the years when I may need it?”
See the GreySmiles guide on how to withdraw from your retirement corpus for the next part of that decision.
What About Taxes?
Tax treatment depends on the nature of the investment, the type of income or gain involved, the holding period and the prevailing tax rules.
That means an old article, social-media post or fund comparison should not be treated as a permanent tax rule.
Before making a decision, check the current position with the Income Tax Department and review the relevant scheme documents.
For the broader retirement picture, see GreySmiles’ tax planning guide for retirees.
Common Mistakes When Using Mutual Funds for Retirement
- Choosing the fund before defining the goal: Investment selection should follow retirement planning, not replace it.
- Chasing recent performance: A fund that performed exceptionally well recently is not automatically the right long-term retirement investment.
- Assuming more funds means more diversification: Overlapping portfolios can create complexity without adding meaningful diversification.
- Treating debt funds as risk-free: Debt-oriented mutual funds have their own interest-rate, credit and liquidity risks. :contentReference[oaicite:6]{index=6}
- Taking more equity risk simply because retirement is far away: Time horizon matters, but so do financial capacity, other assets and the ability to withstand losses.
- Ignoring the transition into retirement: The portfolio’s job changes when regular salary income stops.
- Assuming SIP means safety: Regular investing can improve discipline but does not remove market risk.
- Ignoring costs and taxes: Both can affect the amount ultimately available for retirement spending.
- Buying a product because it contains the word “retirement”: The label does not answer whether the investment is appropriate for your circumstances.
A Practical Mutual Fund Retirement Checklist
| Question | What you need to know |
|---|---|
| What will retirement cost? | Expected essential, lifestyle, healthcare and irregular spending |
| What corpus do I need? | A realistic target based on your spending and circumstances |
| How long until retirement? | Investment horizon |
| How much risk can I actually take? | Risk capacity as well as risk tolerance |
| What job does each fund perform? | Growth, diversification, stability or another defined role |
| What does each fund actually own? | Portfolio composition and concentration |
| What does it cost? | Expense ratio and other applicable costs |
| Can I access the money when I need it? | Liquidity, exit loads, lock-ins and scheme conditions |
| What happens after retirement? | Withdrawal strategy and interaction with other retirement income |
The Question That Matters More Than “Which Fund Is Best?”
Once you have built a mutual-fund portfolio, periodically ask yourself:
“If I had to explain why I own every fund in this portfolio, could I?”
If the answer is no, that is worth investigating.
A retirement portfolio does not become stronger simply because it contains more schemes. It becomes stronger when the different parts work together towards a clearly understood objective.
And that objective can change.
The investor who is accumulating aggressively at 35 may be solving a very different problem from the investor at 55 who is preparing for the first withdrawal from the corpus.
Where Does Retirement Readiness Fit?
Mutual funds answer only one part of the retirement question.
You may have a substantial mutual-fund portfolio and still not be ready to retire if your expected spending is too high, healthcare costs are inadequately planned, reliable income is insufficient or your portfolio carries more risk than you can tolerate.
Conversely, someone with a smaller mutual-fund portfolio may be in a stronger position because they have lower spending, a pension, other assets and a more manageable retirement-income requirement.
That is why retirement readiness needs to be assessed after looking at the whole picture.
Once you have considered spending, corpus, income, investments, healthcare and other risks, you can use the GreySmiles Retirement Readiness Test to step back and ask the larger question: Am I actually ready for retirement?
The GreySmiles Take
There is no magical “retirement mutual fund”. There is only a retirement plan in which every investment should have a reason for being there.
The right mutual fund is therefore not necessarily the one with the highest return, the lowest cost or the most popular name. It is the one that performs a role you actually need — within a portfolio you understand and can live with.
The Bottom Line
Mutual funds can help build retirement wealth and, depending on the portfolio and circumstances, can also form part of a retirement-income strategy. But they should never be viewed in isolation.
Start with the life you want to fund. Estimate what that life may cost. Work out the corpus and income you need. Then decide what role mutual funds should play.
That approach is more useful than searching for a single “best mutual fund for retirement”.
And as retirement gets closer, remember that the question changes from:
“How much can my investments grow?”
to:
“How reliably can my overall retirement resources support the life I want?”
Sources & References
- SEBI Investor — Investor education and securities-market resources
- AMFI Investor — Mutual fund investor education and resources
- Income Tax Department — Current tax information
Important: This article is for educational purposes and is not personalised investment, tax or financial advice. Mutual fund investments are subject to market risk and returns are not guaranteed. Scheme characteristics, costs, taxation and regulatory requirements can change. Always check the latest scheme documents and official regulatory information before investing. Consider taking advice from a SEBI-registered Investment Adviser where appropriate.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.