
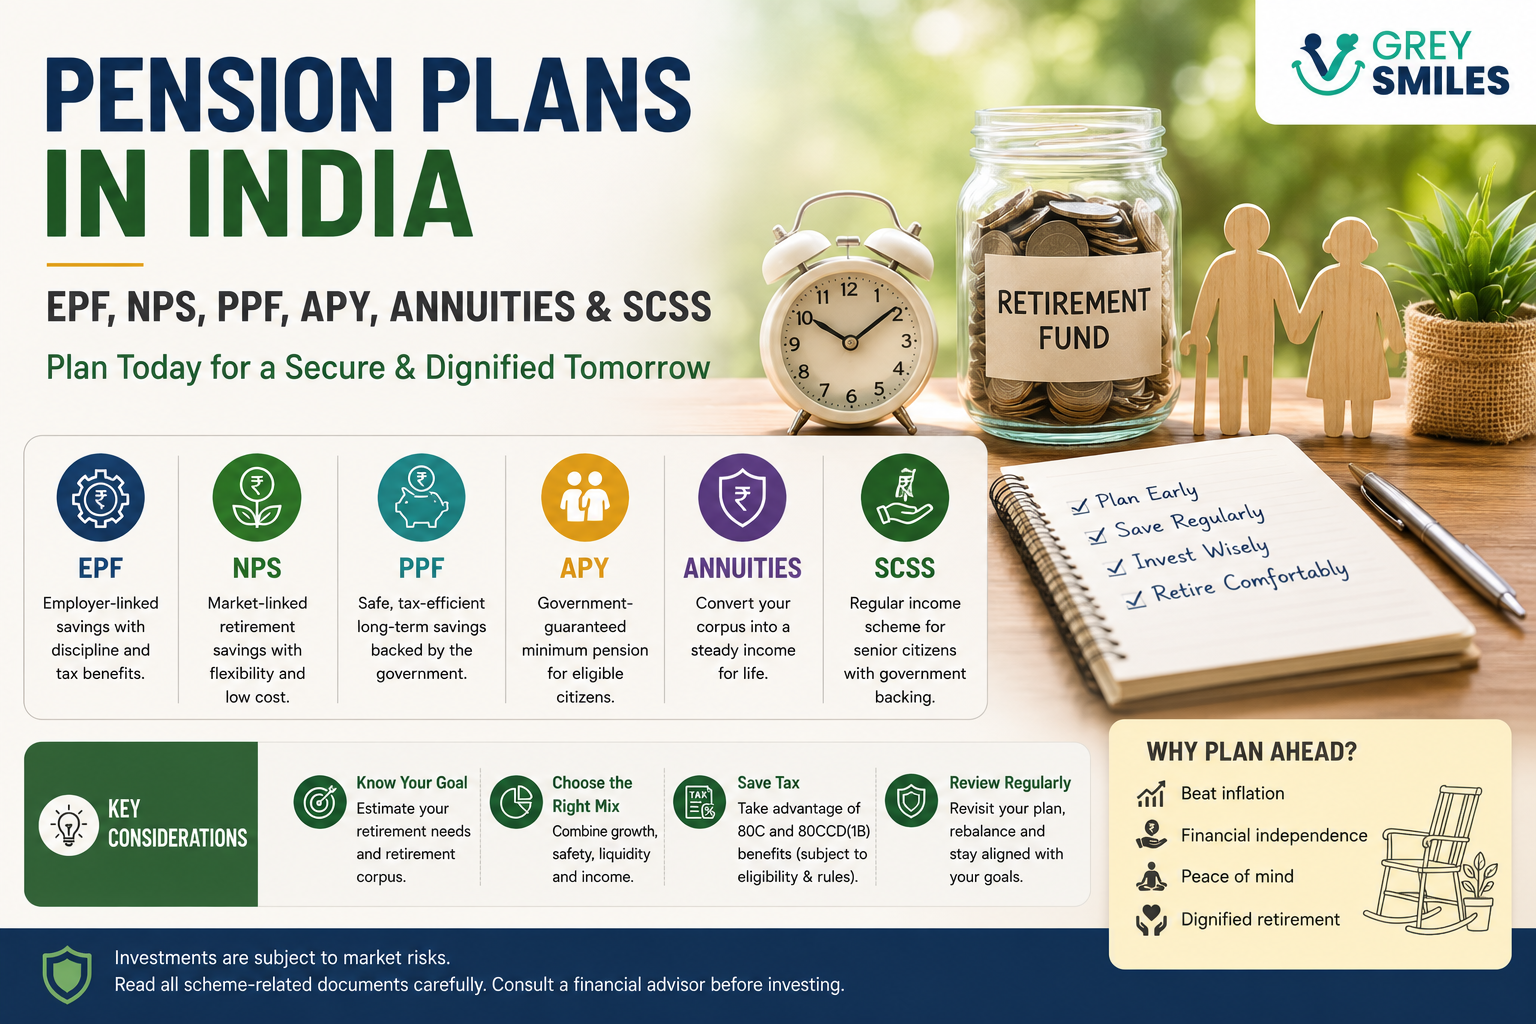
A simple guide to pension plans and retirement income options in India
Pension Plans in India: How to Choose the Right Option
When people search for a pension plan, they are often looking for one simple answer: which plan is best?
Retirement does not work quite that way.
A pension can mean different things depending on where you are in your working life. You may be trying to build a retirement corpus, create a dependable income after retirement, protect your spouse, or simply make sure that part of your retirement money is not exposed to unnecessary risk.
India has several schemes and products that can contribute to retirement income, including NPS, EPF, PPF, APY, SCSS and annuities. They do different jobs, have different eligibility rules and carry different trade-offs.
The useful starting point is therefore not the product name. It is understanding what you need your retirement money to do.
What Is a Pension Plan?
In everyday use, “pension plan” is a broad term. It can refer to a government-backed or workplace retirement scheme, a market-linked retirement savings arrangement, or an insurance product designed to provide income.
These are not interchangeable.
Some products help you accumulate money for retirement. Others are designed to turn an accumulated lump sum into regular income. Some provide greater liquidity, while others impose restrictions on when and how the money can be accessed.
That distinction matters because a product that is useful during the accumulation years may not be the product you need when you actually retire.
The Main Pension and Retirement Options in India
| Option | Broad role | Who may consider it |
|---|---|---|
| NPS | Long-term retirement accumulation | Eligible individuals building retirement savings |
| EPF / EPS | Workplace retirement savings and pension benefits | Eligible employees |
| PPF | Long-term fixed-income savings | Investors looking for a long-term government-backed savings instrument |
| APY | Defined pension benefit for eligible subscribers | Eligible subscribers meeting current conditions |
| SCSS | Interest income for eligible senior citizens | Eligible investors after or around retirement |
| Annuities | Converting a lump sum into regular income | People seeking income after accumulating a corpus |
This table is only a starting point. Eligibility, taxation, withdrawal rules and product features can change, so the current rules should always be checked before investing.
National Pension System (NPS)
NPS is a regulated retirement savings system in which contributions are invested according to the subscriber’s chosen investment structure.
For eligible subscribers under the All Citizen Model, NPS provides a long-term framework for retirement savings with investment choices across asset classes. PFRDA currently lists the All Citizen Model for eligible Indian citizens, NRIs and OCIs between 18 and 85 years of age. :contentReference[oaicite:1]{index=1}
NPS is therefore primarily an accumulation vehicle. It should not automatically be thought of as synonymous with a guaranteed pension.
Its role in a retirement plan depends on how much you contribute, how the money is invested, your time horizon and how you eventually use the accumulated corpus.
NPS is also evolving. PFRDA introduced Retirement Income Schemes and drawdown options under NPS in 2026, making it even more important to check the rules applicable when you actually retire rather than relying on an old explanation of the system. :contentReference[oaicite:2]{index=2}
EPF and EPS
For eligible salaried employees, EPF can become an important part of retirement wealth accumulation through workplace contributions.
EPS, meanwhile, is the pension component associated with the Employees’ Pension Scheme for eligible employees.
For someone covered by these arrangements, they should normally be considered as part of the overall retirement picture rather than viewed in isolation.
The important question is how much retirement income and corpus these benefits may provide alongside your other investments.
Current rules and benefits should be checked directly with EPFO because contribution, withdrawal and pension provisions can change.
Public Provident Fund (PPF)
PPF is a long-term savings instrument that can form part of a retirement portfolio.
Its appeal for many investors is its long-term structure and government-backed framework. But PPF should not automatically be called a pension plan simply because the money may eventually be used for retirement.
It is more useful to think of it as one component of a retirement portfolio that can provide a relatively stable part of the overall asset mix.
Its role becomes clearer when considered alongside equity investments, NPS, EPF and other retirement assets.
Atal Pension Yojana (APY)
APY is designed around a defined pension structure for eligible subscribers.
The scheme allows eligible subscribers to contribute during their working years in return for a guaranteed minimum monthly pension from age 60, subject to the scheme’s applicable conditions.
Current PFRDA rules also restrict new APY accounts for individuals who are income-tax payers from 1 October 2022. The applicable eligibility requirements should therefore be checked before considering the scheme.
APY can be relevant for eligible individuals seeking a defined pension benefit, but it should not be treated as a universal retirement solution.
Senior Citizens’ Savings Scheme (SCSS)
SCSS serves a different purpose from long-term accumulation products such as NPS.
It is designed for eligible senior citizens and certain eligible retirees and can provide interest income during retirement.
For someone already approaching or in retirement, SCSS may therefore be considered as part of the income and stability side of a retirement portfolio rather than as a substitute for decades of retirement accumulation.
Current interest rates, eligibility and deposit limits should be verified from the latest government or India Post information before investing.
Annuities: Turning a Corpus Into Income
Annuities solve a different problem again.
Instead of building a corpus, an annuity is generally about using a lump sum to purchase a stream of income according to the terms of the chosen product.
This can be attractive for someone who values certainty of income and wants to reduce the risk of outliving part of their retirement savings.
But an annuity also involves trade-offs. Depending on the option selected, you may give up liquidity or accept a particular income structure in exchange for greater certainty.
PFRDA explains several annuity structures available through empanelled Annuity Service Providers, including life annuities, options with return of purchase price and joint-life arrangements. :contentReference[oaicite:3]{index=3}
IRDAI’s framework for the standard immediate annuity product also illustrates why annuity choices need to be examined carefully: different options can affect lifetime income and what happens to the purchase price after death. :contentReference[oaicite:4]{index=4}
Pension Plan vs Annuity: They Are Not the Same Thing
The terms are often used interchangeably, but they describe different stages of retirement planning.
| Pension / retirement savings | Annuity | |
|---|---|---|
| Main purpose | Build retirement resources | Convert capital into income |
| Typical stage | Before and around retirement | Usually around or after retirement |
| Primary concern | Accumulation and investment | Income certainty and product terms |
How to Choose Between Pension Options
Rather than asking which pension plan is “best”, compare the options against the problem you are trying to solve.
1. Are you still building your retirement corpus?
If retirement is many years away, the emphasis is generally on disciplined saving, appropriate asset allocation and long-term growth.
Products such as NPS, EPF and other investments may therefore have a larger role than an immediate annuity.
2. Are you close to retirement?
The emphasis may gradually shift towards liquidity, stability, healthcare needs and creating dependable retirement income.
3. Do you need guaranteed income?
If a predictable income stream is particularly important, annuities or other income-generating retirement assets may deserve consideration.
4. How important is liquidity?
A product that provides regular income but makes your capital difficult to access may not be suitable for money that could be required for emergencies or major healthcare expenses.
5. What happens to the money after your death?
For married couples and families, the treatment of the corpus or income after the first death can be an important consideration. Annuity options, in particular, can differ significantly in their treatment of a spouse and nominee.
Do Not Choose a Pension Product Only for the Tax Benefit
Tax benefits can influence the attractiveness of a retirement product, but they should not determine the entire decision.
A tax benefit is useful only in the context of the product’s investment risk, liquidity, costs, withdrawal rules and eventual taxation.
Tax rules also change. Any decision based on a particular tax provision should therefore be checked against the current income-tax rules rather than an old article or product brochure.
Do You Need Only One Pension Product?
Usually, there is no reason to think of retirement income as something that must come from one product.
A household could have EPF or NPS accumulated during employment, other investments for growth, fixed-income assets for stability, and an annuity or other income source after retirement.
The combination matters more than the label attached to any individual investment.
This is particularly important because retirement involves several risks at the same time: market volatility, inflation, healthcare expenses, longevity and the possibility that one source of income may not be sufficient.
The Bigger Retirement-Income Picture
A pension plan is only one part of retirement planning.
Before selecting a product, you should know approximately how much you expect to spend in retirement, how much corpus you may need and how much dependable income you can expect.
Only then can you assess how much additional income your investments need to generate.
For the larger calculation, see How to Calculate Your Retirement Corpus in India.
And once you have accumulated the corpus, the next challenge is deciding how to withdraw it without treating the entire amount as one large cash balance. See How to Withdraw From Your Retirement Corpus.
A Simple Comparison Before You Decide
| What you need | Options worth examining |
|---|---|
| Build retirement savings over many years | NPS, EPF, PPF and other diversified investments |
| Defined pension structure and eligible under scheme rules | APY |
| Income and stability during retirement | SCSS and other suitable fixed-income options |
| Lifetime income from a lump sum | Annuity options |
| Broader retirement growth | A diversified portfolio appropriate to your time horizon and risk capacity |
What to Check Before Buying
- What is the primary purpose of the product?
- When can you access the money?
- What income or return is actually guaranteed, if anything?
- What investment risks remain with you?
- What happens if you need the money earlier?
- What fees or charges apply?
- How is the income or withdrawal taxed?
- What happens to the money after your death?
- How does the product fit with your other retirement assets?
- Are the rules and features still current?
The Bottom Line
There is no single pension plan that is automatically right for every Indian household.
The right choice depends on where you are in your retirement journey and what the money needs to accomplish.
During the accumulation years, the priority may be building enough wealth. As retirement approaches, stability and liquidity become more important. Once retirement begins, the focus can shift towards creating sustainable income while managing inflation, healthcare and longevity risk.
That is why choosing a pension product should come after understanding your overall retirement plan, rather than becoming a substitute for one.
Sources & References
- PFRDA – NPS for All Citizen Model
- PFRDA – Retirement Income Schemes and Drawdown Options
- PFRDA – Annuity Service Providers
- IRDAI – Saral Pension Guidelines
- EPFO – Employees’ Provident Fund Organisation
Disclaimer: This article is for educational and informational purposes only and should not be treated as personalised financial advice. Pension schemes, insurance products and investment products have different risks, conditions, costs and tax treatment. Rules and product features can change. Verify current information with the relevant official authority or product provider before making a financial decision.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.