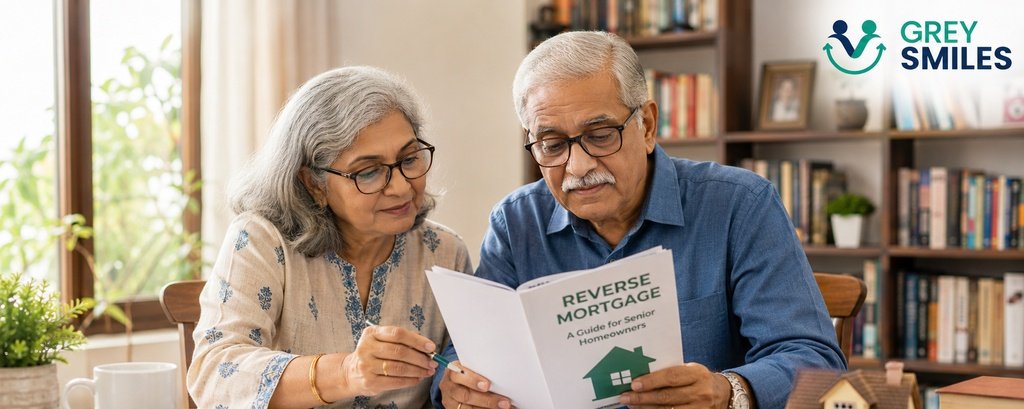
For many Indian seniors, their home is their most valuable asset, but it may not generate any regular income. After retirement, this can create a difficult situation: the house is valuable, yet the money available each month may not be enough to meet living expenses, healthcare costs and other needs.
A reverse mortgage in India is one way eligible senior homeowners may be able to access part of their property’s value without immediately selling it. However, it is a loan secured against the home, not free money. Before considering one, it is important to understand how the arrangement works, what it may provide and what it could mean for the family in the long run.
At a Glance
- What is a reverse mortgage? It allows an eligible senior homeowner to access funds against the value of a residential property while generally continuing to live in it, subject to the loan agreement.
- Who may consider it? Senior citizens who own a qualifying home and need additional retirement income may find it worth exploring.
- Do you have to sell your home? No. The arrangement is different from selling the property, although the home may ultimately be involved in settling the loan.
- How is the money paid? The payment structure depends on the product and lender. Check the amount, frequency and duration of payments before committing.
- What happens to the property? The outstanding loan generally becomes repayable under specified conditions. The agreement determines how the liability can be settled and what options may be available to the heirs.
- What should you check? Property valuation, interest rate, charges, payment terms, borrower obligations, repayment conditions and the implications for your family.
What Is a Reverse Mortgage in India?
A reverse mortgage works differently from a conventional home loan. With a regular home loan, you borrow money to purchase or construct a property and repay the lender over time. With a reverse mortgage, an eligible homeowner uses the value of an existing residential property to obtain funds under an agreed arrangement.
The homeowner generally continues to occupy the property while accessing the agreed financial benefit, subject to the loan conditions. This can be relevant to retirees who are asset-rich but income-constrained: they may own a valuable home but have limited pension, investment or other regular income.
The important distinction is that the property is not simply being sold for cash. A loan liability is created against the home, and the amount outstanding can change as interest and other applicable charges accumulate. The specific product terms determine how funds are released and when the loan must be settled.
Why Would a Senior Citizen Consider a Reverse Mortgage?
Retirement can create a mismatch between wealth and monthly cash flow. Someone may have spent decades paying for a home but have relatively little income after leaving work. Selling the property may not be appealing if it is close to family, familiar services and healthcare, or if the homeowner simply wants to remain in the place they know.
A reverse mortgage may offer a way to access some of the home’s value without an immediate sale. It may be worth exploring when the homeowner needs additional income, intends to remain in the property and has considered other sources of funds.
That does not automatically make it the right solution. The decision should take account of pension income, savings, investments, healthcare costs, other assets and the homeowner’s longer-term housing needs. If you are still assessing your overall position, the GreySmiles Retirement Readiness Test can help you consider your retirement preparedness beyond the value of your home.
How Does a Reverse Mortgage Work?
The process typically begins with the lender checking the homeowner’s eligibility and assessing the property. The lender then determines the amount that may be available and explains the payment structure, interest rate, charges and conditions under which the loan becomes repayable.
- Property assessment: The lender evaluates the property and its value according to its process.
- Eligibility assessment: The borrower and property must meet the applicable requirements.
- Loan amount determination: The amount available depends on factors such as the property valuation, the borrower’s age, the interest rate and the lender’s terms.
- Disbursement: Funds are released according to the payment structure agreed with the lender.
- Continued occupation: The homeowner generally continues living in the property, subject to the agreement and the borrower’s obligations.
- Settlement: The loan becomes repayable when the applicable conditions are triggered. The outstanding amount must then be settled according to the agreement.
The exact process can differ between lenders and products. A general explanation is useful for understanding the concept, but the current offer, sanction letter and loan agreement are what matter when evaluating a particular arrangement.
How Much Can You Get Through a Reverse Mortgage?
There is no single amount that applies to every homeowner. The property’s market value is important, but it does not determine the amount available on its own. The lender may also consider the borrower’s age, the interest rate, the permitted lending limits, the expected tenure and the product’s other conditions.
For example, owning a home valued at ₹1 crore does not mean that a homeowner can receive ₹1 crore through a reverse mortgage. The amount offered may be substantially lower, and the actual offer must be assessed against the homeowner’s income needs and the long-term cost of borrowing.
It is worth comparing the amount offered with the shortfall in your retirement budget. The GreySmiles retirement corpus calculation guide can help you think about the resources needed to fund retirement. It addresses a different question from a reverse mortgage: how much money you may need, rather than how much you might be able to borrow against your home.
How Is the Money Paid?
The payment structure depends on the product and the lender’s terms. For a retiree, the key question is not simply how much can be borrowed, but how much usable income the arrangement will provide, how long payments may continue and what conditions apply.
Before signing an agreement, ask the lender to explain the following points in writing.
| What to check | Why it matters |
|---|---|
| Payment frequency | Helps you understand how the funds will fit into your monthly retirement budget. |
| Payment duration | Clarifies how long payments are expected to continue and which conditions may affect them. |
| Interest rate | Interest affects the outstanding loan balance and the eventual amount that must be settled. |
| Property valuation | Influences the amount the lender may be willing to make available. |
| Repayment conditions | Explains when the loan becomes due and what settlement options may be available. |
| Charges and insurance | These costs can affect the overall value of the arrangement. |
| Borrower obligations | Clarifies responsibilities concerning occupation, maintenance, property taxes and other conditions in the agreement. |
Who Can Get a Reverse Mortgage?
Reverse mortgages are intended for eligible senior homeowners, but the precise requirements depend on the applicable scheme and lender. It is important not to assume that every senior citizen or every residential property will qualify.
Eligibility checks may cover the borrower’s age, ownership and title to the property, the property’s location and condition, the borrower’s occupation of the home and other lender-specific requirements. Where there are joint borrowers, the agreement should also explain how their respective rights and obligations work.
Ask for the current eligibility criteria and written terms directly from the lender before including a reverse mortgage in your retirement plan. Do not rely only on a general description or an advertised payment amount.
What Happens to the House After the Borrower Dies?
This is often the most sensitive part of the decision, particularly for families who expect the home to pass to the next generation. A reverse mortgage creates a loan secured against the property, so the outstanding liability has to be addressed when the loan becomes due under the agreement.
Depending on the loan terms and applicable law, the heirs may have an opportunity to settle the outstanding amount and retain the property. If the loan is not settled, the lender may seek to recover its dues from the property in accordance with the agreement and the applicable legal process.
Families should not assume that the home will automatically pass to the heirs free of any liability. Before signing, ask the lender to explain the settlement process, the time available to the family, the amount that may be due and the options for retaining the property. Where there are joint borrowers, clarify what happens after the death of one borrower and when the loan becomes repayable.
Reverse Mortgage vs Selling Your Home
A reverse mortgage and a home sale can both release money tied up in property, but they solve different problems. A reverse mortgage may allow an eligible homeowner to remain in the home while accessing funds. Selling the property converts it into sale proceeds, but the homeowner will need to arrange suitable housing elsewhere unless another living arrangement is already available.
| Reverse mortgage | Selling the home |
|---|---|
| Provides funds against the property under a loan arrangement. | Converts the property into sale proceeds by transferring ownership. |
| The homeowner may continue living in the home, subject to the agreement. | The seller generally needs another housing arrangement. |
| An outstanding loan liability is created, and interest may accumulate. | The sale itself does not create a reverse-mortgage liability. |
| The property may ultimately be involved in settling the outstanding loan. | The seller receives the net proceeds after applicable costs and obligations. |
| May suit someone who strongly prefers to remain in the home and needs additional funds. | May suit someone willing to move, downsize or use the sale proceeds to support retirement. |
Selling and downsizing may be financially more suitable for some seniors, particularly if the current home is expensive to maintain or larger than they need. Others may place a high value on remaining in familiar surroundings. The comparison should include not only the money available, but also future housing costs, maintenance, family preferences and quality of life.
Reverse Mortgage vs Other Retirement Income Sources
A reverse mortgage should be considered alongside the other income sources and assets available to you. These may include pension income, interest from deposits and fixed-income investments, withdrawals from investments, rental income, annuities and part-time or post-retirement earnings.
The aim is not necessarily to find one product that solves every retirement-income problem. It is to understand how your resources work together and which combination can meet your needs without creating risks you are unwilling to accept.
For a broader look at the choices available, read the GreySmiles guide to generating income after retirement in India. It can help you compare a reverse mortgage with other ways of supporting your retirement cash flow.
What Are the Advantages of a Reverse Mortgage?
The main attraction is that eligible homeowners may be able to access funds without immediately selling their home. This can be useful for people whose wealth is concentrated in residential property but whose regular income is not sufficient to meet their needs.
It may also provide an alternative for homeowners who want to remain in familiar surroundings rather than move immediately. However, whether this is a genuine financial advantage depends on the amount available, the cost of the loan, the terms of continued occupation and the alternatives open to the homeowner.
Risks and Limitations You Should Understand
A reverse mortgage is a borrowing arrangement secured against your home. Its value should be judged by looking at both the funds you receive and the obligations that build up over time.
- Interest accumulates: The outstanding loan balance can increase over time, affecting the amount that eventually needs to be settled.
- Your heirs may receive less property value: If the loan is settled from the property, the value remaining for the family may be lower than the property’s market value.
- Conditions must be maintained: The agreement may specify requirements relating to occupation, property maintenance, taxes, insurance and other responsibilities.
- The amount may not meet your needs: The funds available may be insufficient to cover the retirement-income gap, particularly if healthcare or other expenses rise.
- Property values can change: Future property values are uncertain, and the lender’s valuation process and conditions may affect the offer.
- Moving may affect the arrangement: A permanent move to another residence or assisted living may have consequences under the agreement. Clarify these before committing.
These risks do not automatically rule out a reverse mortgage. They mean that the arrangement should be compared with other ways of funding retirement and assessed against your own housing needs, financial resources and family priorities.
GreySmiles Take
A home can provide security and stability in retirement, but its value on paper is not the same as money available for everyday expenses. Before borrowing against it, first work out the income gap you need to close and compare the reverse mortgage with downsizing, rental income and withdrawals from other assets.
If a reverse mortgage still looks suitable, understand the full loan terms and discuss the implications with your family. The decision should work for your retirement and living needs, not just provide the highest possible payment today.
Questions to Ask Before Taking a Reverse Mortgage
Do not make the decision based only on the advertised monthly payment. Ask the lender to explain the terms in writing, and make sure you understand the answers before signing.
- How has the property value been assessed, and how much can I receive?
- How will the money be paid, and for how long are payments expected to continue?
- What interest rate, fees, insurance costs and other charges apply?
- How is the outstanding loan balance calculated over time?
- What responsibilities do I have for occupation, maintenance, taxes and insurance?
- What happens if I permanently move to another residence or assisted living?
- What happens after the death of one borrower where there are joint borrowers?
- When does the loan become due, and what settlement options are available?
- Can my heirs settle the loan and retain the property? What process and deadlines apply?
- What happens if the property value changes or the loan terms are reviewed?
Ask for examples that show how the balance may change under the proposed terms. If anything is unclear, seek independent financial or legal advice before committing to a long-term arrangement involving your home.
Is a Reverse Mortgage Right for You?
A reverse mortgage may be worth exploring if you own a suitable home, want to continue living there and need additional income that cannot comfortably be met from other sources. It is less likely to be suitable if you expect to move soon, already have adequate retirement income, or want to preserve the property’s full value for heirs without a plan to settle the loan.
Selling or downsizing may be more appropriate if you need a larger pool of funds, want to reduce maintenance costs or would prefer a different living arrangement. The right choice depends on your income needs, the value and role of the home, the alternatives available and how comfortable you are with the long-term implications.
Start with your retirement-income requirement rather than the maximum amount you might be able to borrow. The GreySmiles Retirement Readiness Test can help you consider your overall preparedness, while the retirement corpus calculation guide can help you think about the savings and resources needed to support your retirement.
A Practical Decision Framework
- Calculate your income gap. Work out how much you need each month after accounting for pension and other dependable income.
- Review your other assets. Consider savings, deposits, investments, pension benefits, rental income and other resources that could support retirement.
- Assess the role of your home. Consider its value, maintenance costs, location, accessibility and importance to your family.
- Compare alternatives. Look at downsizing, renting out part of the property where practical, investment withdrawals and other retirement-income options.
- Understand the loan terms. Compare the amount offered, interest, charges, payment structure, borrower obligations and repayment conditions.
- Discuss the implications with your family. This is particularly important if your family expects to retain the property.
- Get professional advice where needed. A qualified financial or legal professional can help you understand the implications for your circumstances.
Reverse Mortgage and Your Overall Retirement Plan
Your home should be considered alongside the rest of your retirement finances, rather than in isolation. If you are relying on the property because your retirement corpus may be insufficient, first try to understand the size of the shortfall and the income you need to cover it.
A reverse mortgage may form one part of a retirement-income strategy, but it does not remove the need to plan for healthcare, daily expenses, inflation and other long-term needs. Compare it with the income available from your other assets and consider whether the arrangement remains suitable if your circumstances change.
The aim is to make an informed decision that supports both your financial security and your preferred way of living in retirement.
Frequently Asked Questions
What is a reverse mortgage in India?
A reverse mortgage is a loan arrangement through which an eligible senior homeowner can access funds against the value of a residential property while generally continuing to live in it, subject to the lender’s terms. The loan must be settled according to the conditions of the agreement.
Do I have to sell my house to get a reverse mortgage?
No. A reverse mortgage is different from selling the property. It allows an eligible homeowner to access funds against the home while continuing to occupy it, subject to the applicable conditions. The property may, however, ultimately be involved in settling the outstanding loan.
Can I continue living in my home after taking a reverse mortgage?
The arrangement is generally intended to allow the borrower to remain in the property, subject to the loan agreement and applicable rules. Before signing, check the conditions relating to occupation, maintenance, taxes, insurance and any circumstances that could affect your right to remain in the home.
What happens to the house after the borrower dies?
The loan becomes subject to settlement under the applicable terms. Depending on the agreement and applicable law, heirs may have an opportunity to settle the outstanding liability and retain the property. Ask the lender to explain the process, timelines and options before entering the arrangement.
Is reverse mortgage income taxable?
The tax treatment depends on the applicable tax rules and the nature of the transaction. Do not assume that every payment will be treated in the same way as salary, pension or investment income. Check the current position with a qualified tax professional before making a decision.
Is a reverse mortgage better than selling the house?
Neither option is automatically better. A reverse mortgage may suit someone who wants to remain in the home and needs additional income. Selling or downsizing may make more sense for someone who needs a larger pool of funds, wants to reduce maintenance costs or is comfortable moving to another home.
What should I compare before choosing a reverse mortgage?
Compare the property valuation, amount available, interest rate, payment structure, duration, fees, borrower obligations, repayment conditions and implications for heirs. Consider these alongside your retirement-income needs and the alternatives available to you.
The Bottom Line
A reverse mortgage in India may help eligible senior homeowners turn part of their home equity into retirement cash flow without immediately selling their home. For someone who wants to remain in familiar surroundings but needs additional income, it may be worth considering.
However, the arrangement creates a loan against the property. Interest and other applicable costs affect the outstanding balance, and the eventual liability can influence what remains for heirs. The terms also determine the borrower’s responsibilities and the circumstances in which the loan must be settled.
The more useful question is not simply how much money you can obtain from your home. It is whether the arrangement can meet your retirement-income needs while allowing you to remain in your home, and whether you are comfortable with its long-term financial and family implications.
Compare the alternatives, read the agreement carefully and seek professional advice where needed before making a decision.
Disclaimer: This article is for general educational purposes and does not constitute personalised financial, legal or tax advice. Reverse-mortgage eligibility, terms, interest rates, tax treatment and regulatory requirements can change. Always verify the current terms with the relevant lender and consult an appropriate professional before making a financial decision.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.