
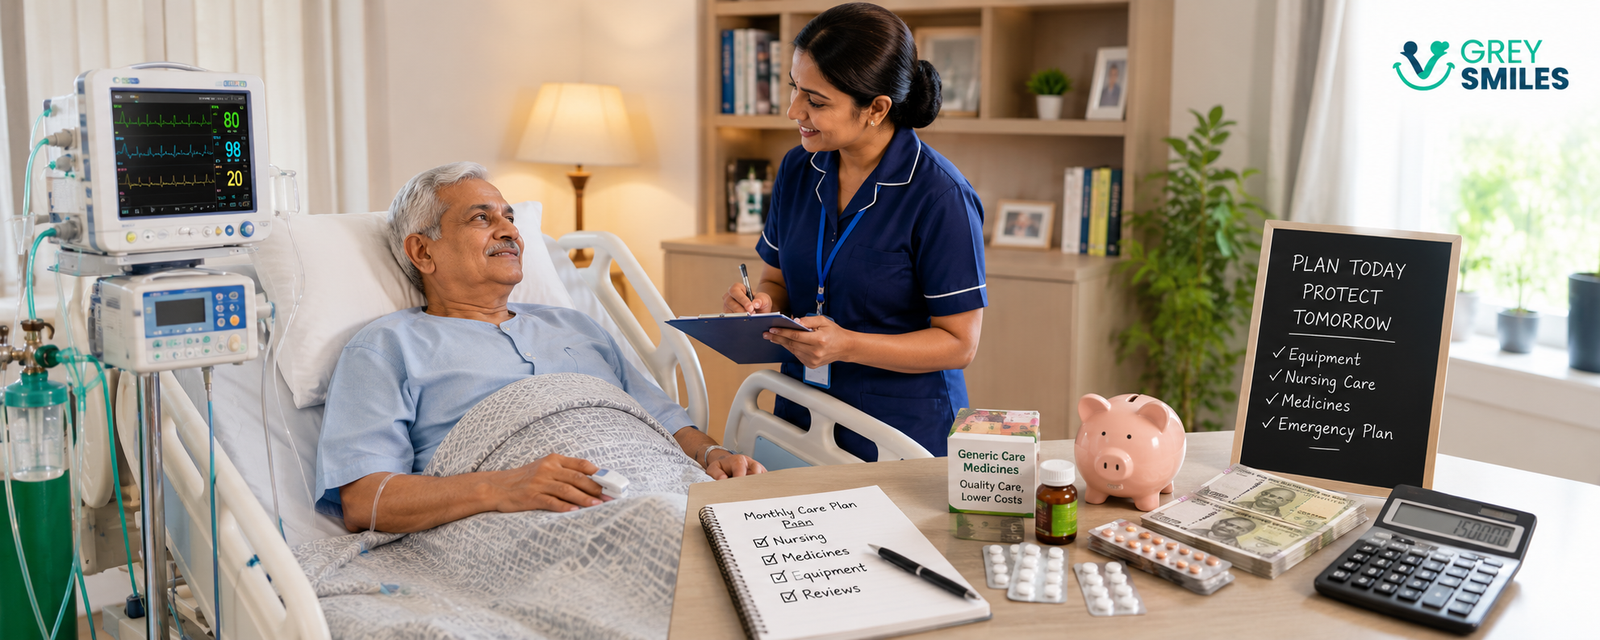
When an older family member needs intensive care, moving treatment home can feel like a practical alternative to prolonged hospitalisation. But home care does not mean the medical costs disappear. Depending on the person’s condition, the family may need equipment, trained nursing, medicines, consumables, medical supervision and a plan for emergencies.
The expense can also change quickly. A setup that seems manageable for a few weeks can become a significant financial commitment if care continues for several months.
That makes home ICU planning partly a healthcare decision and partly a household-finance decision. The treating medical team has to determine what care is appropriate; the family needs to understand what that care could mean for its finances.
At a Glance
- Home ICU costs extend beyond equipment. Nursing, medicines, consumables, doctor visits and emergency arrangements can all become recurring expenses.
- Nursing can be one of the largest monthly costs, particularly when a patient needs continuous or specialised care.
- There is no standard home ICU price in India. The cost depends on the patient’s condition, the level of support required, the city and the length of care.
- Insurance needs to be checked before assuming coverage. Home healthcare and domiciliary treatment may be subject to specific policy conditions.
- Long-term care can affect retirement savings. A prolonged period of home care should be considered alongside the family’s wider healthcare and retirement planning.
What Does Home ICU Care Actually Require?
A home ICU is not simply a hospital bed placed in a bedroom. The setup depends on what the patient needs medically. Some patients may need oxygen and basic monitoring, while others may require non-invasive ventilation, suction equipment, continuous monitoring or more intensive support.
The first step should therefore be a clear medical assessment. Families should understand which equipment is necessary, how much nursing support is required, who will supervise the treatment and what should happen if the patient’s condition worsens.
Once those requirements are clear, the financial estimate becomes much more useful than starting with a generic “home ICU package” price.
Home ICU Equipment: What May Need to Be Paid For
Equipment costs vary considerably because not every patient needs the same level of support. Renting may make more sense than buying when the expected period of care is uncertain or relatively short.
| Equipment | Indicative Monthly Rental |
|---|---|
| Electric hospital bed | ₹5,000–₹12,000 |
| Oxygen concentrator | ₹3,000–₹8,000 |
| BiPAP / non-invasive ventilation | ₹8,000–₹20,000+ |
| Patient monitor | ₹5,000–₹15,000+ |
| Suction machine | ₹2,000–₹5,000 |
These are indicative planning ranges rather than fixed market prices. Actual costs can vary by city, supplier, equipment specification, rental period and clinical requirement.
Nursing May Become the Biggest Recurring Cost
The nursing requirement can be very different from one patient to another. Someone who needs help with daily activities does not require the same level of support as a patient who needs continuous monitoring or assistance with complex medical equipment.
| Type of Care | Indicative Cost |
|---|---|
| Basic attendant / caregiver support | ₹15,000–₹25,000 per month |
| Trained nursing support | ₹25,000–₹45,000+ per month |
| Higher-dependency / specialised care | ₹40,000–₹70,000+ per month |
| 24-hour nursing arrangements | Can exceed ₹50,000–₹80,000 per month depending on staffing and care requirements |
These are indicative ranges only. Actual nursing costs depend on location, qualification, shift pattern, agency, staffing arrangement and the complexity of care.
When comparing nursing quotes, families should look beyond the headline monthly number. Clarify the number of hours covered, the qualification of the caregiver or nurse, replacement arrangements, night shifts and whether supervision is included.
The Monthly Bill Does Not Stop at Equipment and Nursing
Medicines and medical consumables can become a substantial part of the cost when treatment continues for a long period. Depending on the patient’s needs, there may also be diagnostic tests, doctor consultations, oxygen supplies, dressings, feeding supplies and other disposable items.
This is one reason a family should calculate the expected monthly cost rather than focus only on the initial equipment setup. A ₹20,000 equipment bill is relatively easy to understand; several thousand rupees of recurring expenses every week are easier to underestimate.
A More Useful Way to Estimate the Total Cost
Instead of looking for one home ICU figure, break the estimate into the costs that are likely to continue throughout the period of care.
| Cost Component | What to Include |
|---|---|
| Equipment | Bed, oxygen, monitoring, respiratory and other medically required equipment |
| Nursing | Daily, shift-based or 24-hour nursing and caregiving support |
| Medicines | Prescribed medicines and ongoing treatment |
| Consumables | Disposable medical and caregiving supplies |
| Medical supervision | Doctor visits, diagnostics and specialist consultations |
| Emergency provision | Transport and hospitalisation if home care becomes unsuitable |
What Happens When Home Care Continues for Months?
The financial calculation changes when a short-term arrangement becomes long-term care. A family may initially expect a few weeks of support, only to find that nursing, medicines and equipment remain necessary much longer.
For a retired household, that recurring expense can compete directly with normal retirement spending. Money that was expected to fund food, housing, travel or other living costs may instead be used for care.
This is why healthcare planning deserves its own place in retirement planning. GreySmiles’ guide to planning healthcare costs in retirement looks at regular healthcare spending, insurance and the need for a separate reserve. The related healthcare costs in retirement article goes further into the question of how much money may need to remain accessible for healthcare.
What About Health Insurance?
Families should check their policy before assuming that home ICU care will be reimbursed. Some health insurance policies may cover eligible domiciliary or home healthcare treatment, but the conditions, exclusions, limits and documentation requirements differ between policies.
The important distinction is between having health insurance and knowing what the policy will actually pay for. A family may still have to meet deductibles, co-payments, excluded expenses or costs that fall outside the policy’s definition of covered treatment.
Where possible, confirm the position with the insurer before committing to a major home-care arrangement. If the situation is urgent, the treating medical team and insurer should be involved as early as practical.
Planning for Healthcare Costs Before They Happen
It is difficult to predict exactly what an older person will spend on healthcare over the next ten or twenty years. It is possible, however, to see how today’s out-of-pocket costs could grow if they rise over time.
GREYSMILES CALCULATOR
Health Inflation Planner
The GreySmiles Health Inflation Planner lets you enter current annual out-of-pocket healthcare spending, an assumed medical inflation rate and a planning horizon. It then illustrates how those costs could grow over time.
Use the Health Inflation Planner
Illustrative planning tool. Actual healthcare costs depend on medical needs, treatment, inflation and individual circumstances.
How Much Should a Family Keep Available?
There is no sensible universal number for a home-care or healthcare reserve. The right amount depends on the person’s age, health, insurance, existing savings, family support and the kind of care that may realistically be required.
A useful starting point is to calculate the current monthly healthcare burden and then consider what would happen if that amount continued for six months, a year or longer. That exercise can reveal whether the family has enough accessible money or is relying too heavily on long-term investments.
For someone approaching retirement, the same exercise should feed into the broader retirement corpus calculation. The corpus is not just there to fund routine monthly spending. It may also need to absorb periods when healthcare or caregiving costs rise sharply.
Questions to Ask Before Setting Up Home ICU Care
Before committing to a home-care arrangement, it helps to get answers to a few practical questions:
- What level of medical support does the treating doctor recommend?
- Which equipment is medically necessary?
- How many hours of nursing support are required?
- Who supervises the clinical care?
- What happens if the patient’s condition deteriorates?
- Is there an emergency-transfer arrangement?
- Which expenses may be covered by insurance?
- What are the expected monthly medicine and consumable costs?
- How would the family fund the care if it continued for six months or longer?
The Financial Decision Is About Sustainability
Home care can offer a familiar environment for a seriously ill person, but it can also shift a significant amount of responsibility onto the family. The financial burden is only one part of that responsibility; caregiver availability, clinical supervision and the ability to respond to an emergency matter too.
For families, a useful plan is one that looks beyond the first invoice. Estimate the recurring cost, understand what insurance may cover, keep enough money accessible and consider how prolonged care would affect the rest of the household’s finances.
GreySmiles Take
The difficult part of home ICU planning is rarely the first month’s bill. It is the possibility that care continues for much longer than the family expected. A financially resilient plan therefore needs to consider the recurring cost of nursing and treatment, the limits of insurance and the effect that prolonged care could have on retirement savings.
Frequently Asked Questions
How much does a home ICU cost in India?
There is no single nationwide price. The cost depends on the patient’s medical condition, equipment, nursing requirement, medicines, consumables, medical supervision and duration of care. A basic arrangement can cost considerably less than one requiring continuous nursing and advanced respiratory or monitoring equipment.
Is home ICU care cheaper than hospital ICU care?
It can be, but the comparison depends on the level of care required and how long treatment continues. A properly supported home ICU can still involve substantial equipment, nursing and medical costs. Medical suitability should come before cost when deciding between care settings.
Does health insurance cover home ICU care?
Some policies may cover eligible domiciliary or home healthcare treatment, subject to their terms and conditions. Families should check the specific policy rather than assume that every home ICU expense will be reimbursed.
What is usually the biggest recurring home ICU expense?
Nursing can become one of the largest recurring expenses, particularly where round-the-clock or specialised care is required. Medicines, consumables, equipment rentals and medical supervision can add substantially to the monthly cost.
How should retirees prepare for long-term elder-care costs?
Start by understanding likely healthcare spending, reviewing insurance, maintaining accessible reserves and checking whether the retirement corpus can absorb a prolonged period of care. Healthcare planning works best when it is part of the retirement plan rather than something considered only after a medical crisis.
Further Reading
- How to Plan for Healthcare Costs in Retirement — planning regular healthcare expenses, insurance and a separate reserve.
- Healthcare Costs in Retirement — understanding the role of a dedicated healthcare reserve.
- How to Reduce Medicine Costs in Retirement — practical ways to manage recurring medicine expenses.
- How to Calculate Your Retirement Corpus in India — understanding how healthcare and other expenses fit into the wider retirement number.
Sources & References
- Insurance Regulatory and Development Authority of India (IRDAI) — health insurance consumer information and policyholder guidance.
- Ministry of Health and Family Welfare, Government of India — healthcare and elderly-care information.
Disclaimer: Costs mentioned in this article are indicative planning ranges and can vary significantly by city, provider, equipment specification, nursing requirements, medical condition and duration of care. Medical decisions should be taken with the treating healthcare professional. Insurance coverage depends on the terms of the individual policy.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.