
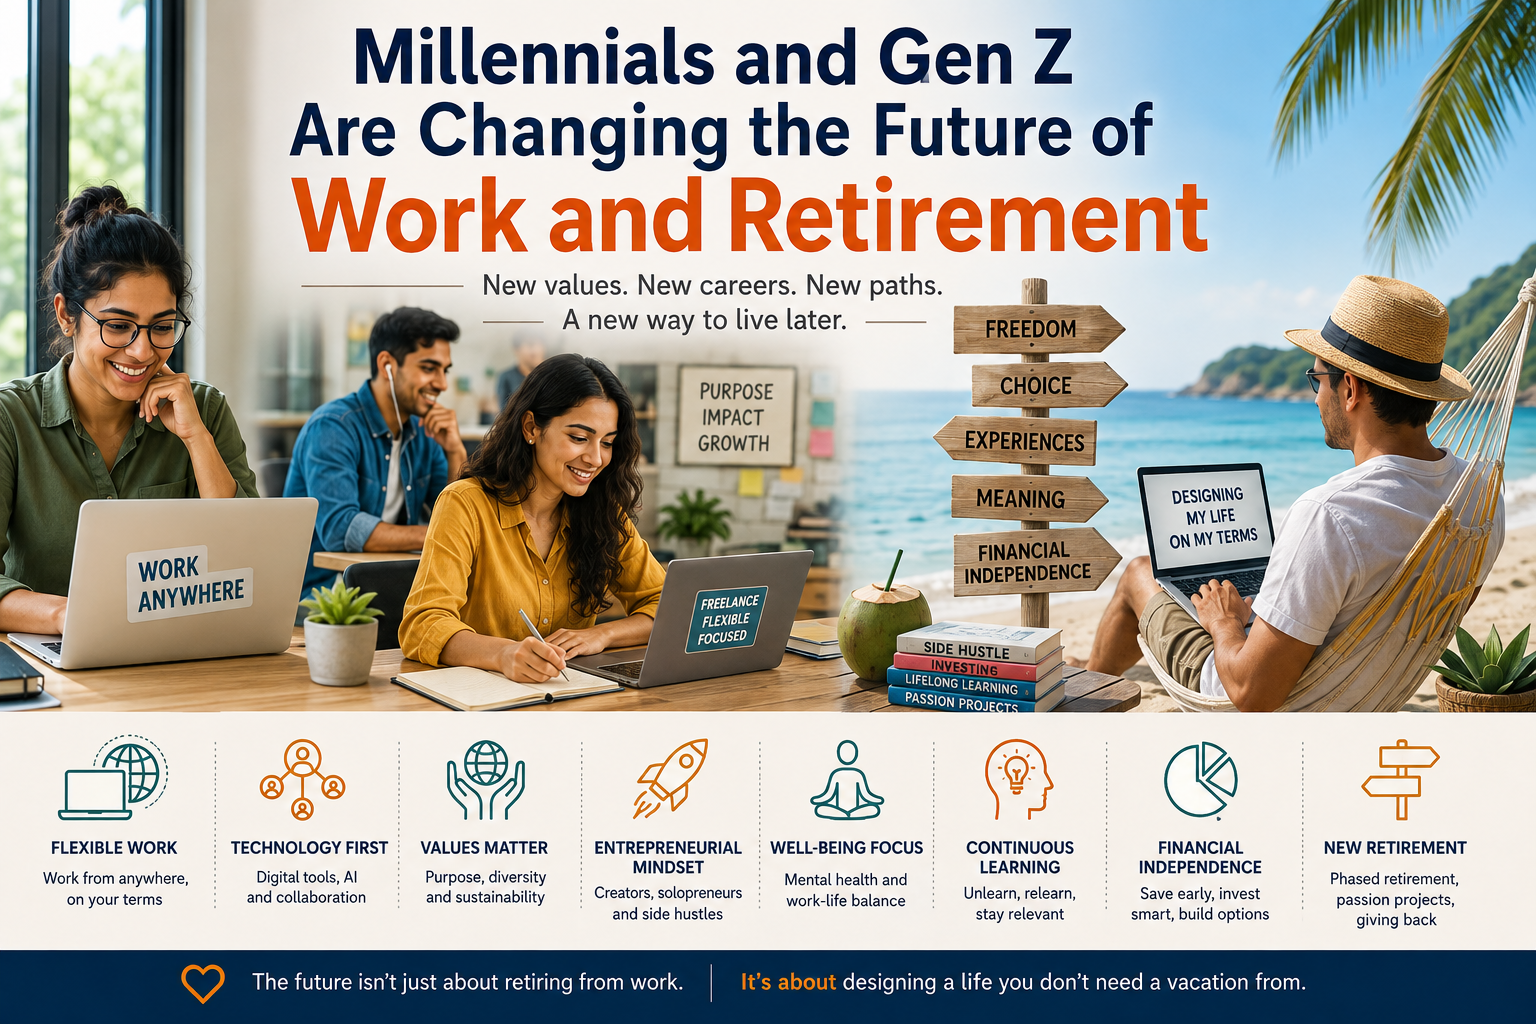
Millennials and Gen Z are reshaping work, financial independence and retirement.
Quick Takeaway
Millennials and Gen Z may not simply change the way we work; they could eventually change what we mean by retirement.
For younger Indians, retirement may increasingly be less about reaching a fixed age and more about achieving enough financial independence, flexibility and choice to decide how and when they work.
Remote work, technology, entrepreneurship, continuous learning, purpose and changing career paths are all part of this shift. The result could be a future where people move between full-time work, part-time work, career breaks, self-employment and retirement rather than following one straight path from employment to retirement.
Introduction
For a long time, the traditional Indian career path was relatively predictable: education, a stable job, decades of work, retirement and then life after work.
Millennials and Gen Z are growing up with a different set of possibilities. They have seen remote work become mainstream, technology transform jobs, entrepreneurship become more accessible and career changes become less unusual. They are also asking difficult questions about money, meaning, flexibility, wellbeing and how much of life should be spent working.
These changes are important for younger people, but they also matter to today’s retirees and pre-retirees. The way the next generation works could influence how families plan for retirement, whether children remain a financial safety net for parents, and whether the very idea of a fixed retirement age continues to make sense.
In this article
- Shaping the Future of Work
- Remote and Flexible Work
- Technology-Driven Collaboration
- Values-Driven Employment
- Entrepreneurial Spirit
- Mental Health and Well-Being
- Continuous Learning
- Shaping the Future of Retirement
- Changing Retirement Paradigms
- Financial Literacy and Planning
- Diverse Investment Strategies
- Alternative Retirement Models
- Technology in Retirement Planning
- The Indian Context: A More Radical Change?
- What Parents and Today’s Retirees Can Learn
- Key Takeaway
- FAQs
Why this matters now: Deloitte’s 2026 India Gen Z and Millennial Survey found that maintaining work-life balance and achieving financial independence remain top priorities for these generations. The survey also found that 54% of Gen Z respondents and 44% of millennials in India said they had delayed major life decisions because of their financial situation.
That makes the conversation about retirement more complicated than simply asking whether younger people want to retire early. They may instead be trying to build a life in which they have greater control over when, where and why they work.
Shaping the Future of Work
Millennials and Gen Z are playing a significant role in reshaping the future of work and retirement through their values, preferences, and behaviors. They prefer to work remotely, use technology as a tool to collaborate, and prefer to work with organisations that are sensitive towards sustainability and diversity. Here are some key ways they are influencing these domains:
1. Remote and Flexible Work
Both generations prioritize work-life balance and flexibility. The COVID-19 pandemic accelerated the adoption of remote work, and many employees now expect hybrid or fully remote options to continue.
This change goes beyond where people sit while working. Flexibility can affect how people think about the entire structure of their working lives. A person who can work remotely may be able to live in a different city, take a career break, work for an overseas employer from India, or gradually reduce working hours later in life.
For retirement planning, that raises an interesting possibility: what if retirement becomes a gradual reduction in work rather than a sudden stop?
2. Technology-Driven Collaboration
Millennials and Gen Z are digital natives, comfortable with a wide range of technologies. They advocate for the use of collaboration tools, cloud computing, and real-time communication platforms, which are reshaping traditional office dynamics.
Artificial intelligence is now accelerating this change. Deloitte’s 2026 India research reports that 93% of Gen Z respondents and 95% of millennials surveyed in India use AI in their day-to-day work. The research also points to learning, career advice and managing work-related stress as important ways younger workers are using AI.
This creates a new retirement-planning question for younger workers: will the skills that make you employable at 30 still make you employable at 50?
For Millennials and Gen Z, lifelong learning may therefore become as important to retirement security as saving and investing.
3. Values-Driven Employment
These generations tend to favor companies that align with their values. They often seek employers committed to diversity, equity, and environmental sustainability. Corporate social responsibility (CSR) has become an important factor in attracting and retaining talent.
The significance of this is that work is increasingly being connected to identity and purpose. Deloitte’s 2026 India research found that 99% of Gen Z respondents and 98% of millennials surveyed said having a sense of purpose is important to job satisfaction.
That could influence retirement too. If work is expected to provide meaning, identity and contribution, simply removing work from life may not automatically create a satisfying retirement.
4. Entrepreneurial Spirit
Both generations show an inclination toward entrepreneurship, driving the gig economy and freelance work. Many prefer projects over traditional long-term employment, leading to more jobs that are temporary or contract-based.
This could create a more complicated retirement journey. Someone may have periods of salaried employment, freelance income, entrepreneurship and career breaks rather than one uninterrupted career.
That means younger workers may need to think about retirement savings differently. They may need to understand how their savings, investments, insurance and retirement arrangements work when income is not always predictable.
In India, this also makes early financial planning particularly important. The National Pension System (NPS), for example, is a defined-contribution pension system regulated by PFRDA and can be voluntarily subscribed to by Indian citizens, including resident and non-resident Indians, subject to the applicable rules.
Retirement planning for a generation with multiple employers and income streams may need to be much more deliberate than simply relying on a single employer-linked retirement benefit.
5. Focus on Mental Health and Well-Being
There is a growing awareness and advocacy for mental health in the workplace. Employers are increasingly expected to provide resources for mental wellness, flexible hours, and supportive environments.
This could have an unexpected effect on retirement thinking. Younger workers may become less willing to accept the old idea that career success requires sacrificing health and personal life for decades and recovering later.
Instead, they may try to build wellbeing into the working years themselves.
That could make the traditional idea of “work hard now, enjoy life after retirement” increasingly outdated.
6. Continuous Learning and Development
Millennials and Gen Z value ongoing education and skill development. Companies are responding by offering training programs, mentorship opportunities, and support for professional growth, contributing to a culture of lifelong learning.
This is perhaps one of the most important connections between the future of work and the future of retirement.
If people are expected to keep learning throughout their careers, then retirement planning may eventually include a plan for staying employable, not simply a plan for accumulating a retirement corpus.
A 45-year-old who can learn a new skill and earn in a different way may have a very different retirement outlook from someone whose income depends entirely on one skill or one employer.
But the bigger change may not be happening at work.
It may be happening in the way Millennials and Gen Z think about retirement itself.
For previous generations, retirement was often a destination. For younger generations, it may increasingly become a form of financial freedom: having enough resources and flexibility to decide how much work they actually want to do.
Shaping the Future of Retirement
1. Changing Retirement Paradigms: Millennials and Gen Z are rethinking traditional retirement. With shifts in career paths and the gig economy, many do not view retirement as a final phase—but rather as a flexible opportunity for continued engagement in work, passion projects, or entrepreneurial ventures.
This distinction is worth exploring.
Traditional retirement can be described as:
Work → retirement → stop working.
A more flexible model could look like:
Full-time work → part-time work → career break → consulting → entrepreneurship → occasional work → retirement.
There may be no single retirement date.
There may simply be different stages of work.
2. Financial Literacy and Planning
Younger generations are increasingly focused on financial education and planning for their futures, often seeking to understand investments, savings, and retirement accounts like EPF/ NPS from an early age.
This is particularly important because the financial environment facing younger Indians is not necessarily easy. Deloitte’s 2026 India survey found that more than half of Gen Z respondents and a substantial proportion of millennials surveyed had delayed major life decisions because of financial circumstances. Housing affordability was also reported as influencing career decisions.
So while younger Indians may be more financially aware, they are also planning against higher uncertainty.
The retirement conversation therefore needs to move beyond “save as much as possible” to questions such as:
- How much should I save for retirement?
- How much flexibility will I need if my career changes?
- What happens if I take a career break?
- How will I fund healthcare later in life?
- How much should I depend on children or family?
- Could I work part-time later rather than stop completely?
3. Diverse Investment Strategies
There is a growing interest in socially responsible investing (SRI) and environmental, social, and governance (ESG) criteria. Younger workers often want their investments to align with their values, influencing how retirement savings are managed.
The larger trend is that younger investors may want to understand not only how much they are accumulating but also what they own and why.
However, values should not replace financial discipline. Retirement savings have a long time horizon, and investment decisions should be based on an individual’s goals, risk tolerance, time horizon and circumstances rather than simply following a trend.
4. Alternative Retirement Models
Concepts such as early retirement, part-time work in later years, or “phased” retirement are gaining popularity among younger generations who wish to transition into retirement while still staying engaged in work.
This may eventually become one of the most significant changes in retirement planning.
Instead of asking:
“At what age will I retire?”
younger workers may ask:
“At what point can I stop needing to work full-time?”
Those are very different questions.
The first is about age.
The second is about financial independence.
And financial independence does not necessarily require someone to stop working.
5. Technology in Retirement Planning
Fintech solutions like robo-advisors, apps for tracking expenses, and online financial education platforms cater to the tech-savvy nature of Millennials and Gen Z, making retirement planning more accessible.
Technology could also make retirement planning more continuous. Instead of thinking about retirement once every few years, younger people can track savings, expenses and investments more regularly.
But convenience should not be confused with good advice. A retirement app can show a number; it cannot necessarily tell someone whether that number is appropriate for their family circumstances, healthcare needs, longevity expectations or desired lifestyle.
The Indian Context: The More Radical Change May Be Family Expectations
There is an important Indian dimension to this conversation.
Retirement has traditionally been closely connected with family. Parents often expected adult children to remain nearby, help when necessary and eventually play a role in their later years.
That assumption is becoming harder to rely on.
Millennials and Gen Z may live in Bengaluru, Mumbai, Dubai, Singapore, London, Toronto, Sydney or somewhere else entirely. They may have demanding careers, their own financial commitments and their own ideas about family responsibilities.
Some may also choose not to have children, have children later, or live very different family lives from their parents.
This creates a retirement question Indian families do not always ask early enough:
“If my children cannot or should not be my retirement plan, what is my plan?”
This is not about blaming younger generations or suggesting that children do not care about their parents.
It is about recognising that love and financial dependence are not the same thing.
A son or daughter living abroad may be deeply involved in a parent’s life but may not be able to provide daily physical support, accompany a parent to every doctor appointment, handle an emergency at short notice or manage practical matters from another country.
That makes financial independence, healthcare planning, local support systems and practical retirement preparation increasingly important.
Related Grey Smiles Reading
Can I Retire? If you are wondering whether you are financially and personally ready for retirement, take the Grey Smiles Retirement Readiness Test.
Can I Retire Early? If financial independence and a more flexible working life interest you, explore the Grey Smiles guide on Can I Retire Early?.
Planning retirement beyond money: Readers should also be directed to relevant Grey Smiles articles on loneliness, healthcare, children living abroad, purpose after retirement and life after work. These are important because retirement readiness is not purely a financial calculation.
What Parents and Today’s Retirees Can Learn From Millennials and Gen Z
This conversation is not only for younger readers.
Today’s retirees and parents of adult children can learn something important from the generations that are questioning the traditional career model.
Retirement does not have to mean stopping everything
If a retiree enjoys consulting, teaching, mentoring, writing, advising, volunteering or running a small business, there is no rule that says retirement has to mean stopping all productive activity.
Work can be redesigned
Perhaps the choice is not simply “continue working” or “retire.”
Could you work three days a week? Take projects rather than a permanent role? Teach? Mentor? Consult? Work remotely?
Purpose matters as much as money
A retirement corpus can answer the question “Can I afford to stop working?”
It cannot answer “What will I do with my time?”
Younger generations are forcing the workplace to think more seriously about purpose and wellbeing. Older generations can bring the same thinking into retirement.
Conclusion
The impact of Millennials and Gen Z on the future of work and retirement is profound, as they continue to challenge traditional norms and redefine expectations in the workplace and beyond. As these generations continue to mature and influence the workforce, businesses and financial institutions will need to adapt to retain talent and meet the evolving needs of workers approaching retirement.
But there is a bigger possibility.
Millennials and Gen Z may not simply redefine the future of work. They may redefine the future of retirement.
The traditional model assumes that work is something we do for several decades and retirement is what happens afterwards.
The emerging model may be much less linear.
People may work, learn, pause, change careers, start businesses, work part-time, take breaks and return to work at different stages of life.
Retirement could become less about reaching a particular age and more about reaching a level of financial independence that gives people choices.
Perhaps the most radical change is this:
Maybe the goal of retirement isn’t to build enough money so that you never work again.
Maybe the goal is to build enough financial freedom that you only do work you actually want to do.
Key Takeaway
Millennials and Gen Z are changing more than the workplace. Their focus on flexibility, technology, learning, purpose, wellbeing and financial independence could eventually make the traditional retirement age less important.
For today’s retirees, there is a lesson too: retirement does not necessarily have to mean switching off. And for younger Indians, perhaps the goal is not simply to retire early.
It may be to build enough financial resilience that work becomes a choice rather than a necessity.
Sources and Further Reading
- Deloitte India – 2026 Gen Z and Millennial Survey – useful data on financial independence, work-life balance, AI adoption, purpose and financial pressures among India’s younger workers.
- Deloitte India – Gen Z and Millennial Survey 2026: AI and the Indian workforce – data on AI adoption, skills, financial strain and career priorities.
- PFRDA – National Pension System – official information on NPS and its role in retirement savings in India.
Frequently Asked Questions
Are Millennials and Gen Z changing the meaning of retirement?
They may be. Younger workers are increasingly interested in flexibility, financial independence, continuous learning, wellbeing and purpose. These preferences could lead to more flexible transitions between full-time work, part-time work, entrepreneurship, career breaks and retirement.
Do Millennials and Gen Z want to retire early?
Not necessarily. A better way to understand the trend is that many younger workers want greater control over when and how they work. Early retirement is only one possible outcome of that desire for flexibility.
What is the difference between financial independence and retirement?
Retirement generally means leaving employment. Financial independence means having enough financial resources and flexibility that you have greater freedom to choose whether, when and how you work.
Will AI change retirement planning?
It could. If technology changes careers and skills more rapidly, retirement planning may increasingly need to include lifelong learning, career adaptability and the ability to generate income in different ways.
What can today’s retirees learn from Millennials and Gen Z?
Today’s retirees can learn from younger generations’ focus on flexibility and purpose. Retirement does not necessarily have to mean stopping every form of productive or paid activity. Consulting, mentoring, teaching, entrepreneurship and part-time work can all form part of a fulfilling later life.
Could retirement become more flexible in India?
It is possible. India’s workforce is becoming more technology-enabled, geographically mobile and diverse. As careers become less linear, retirement may increasingly become a gradual transition rather than a single event at a fixed age.
Should parents expect their children to fund their retirement?
It is safer to view support from children as something that may complement a retirement plan rather than the foundation of one. Adult children may live in another city or country, have their own financial responsibilities or be unable to provide day-to-day support. A stronger retirement plan considers finances, healthcare, housing, emergency support and social connections independently.
Why should younger Indians think about retirement early?
Starting early gives savings and investments more time to grow and gives people more flexibility if their careers change. It also allows younger workers to plan for periods when they may earn less, take a career break, change professions or choose to work part-time later in life.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.