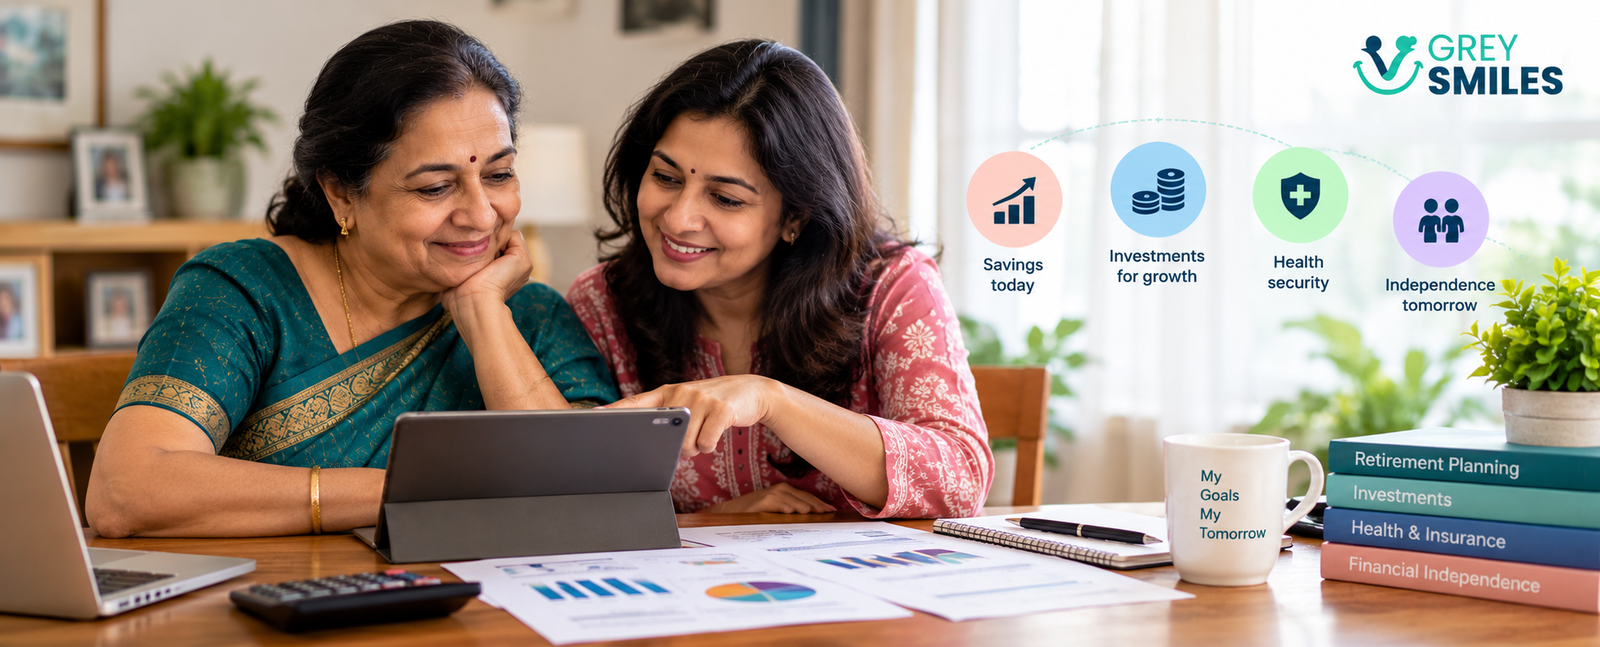
Sunita and her daughter discuss financial independence and the importance of planning for retirement
Retirement planning for women presents a particular challenge: women generally have longer life expectancies than men, yet many reach retirement with fewer financial resources of their own. Lower lifetime earnings, career interruptions for caregiving and years spent prioritising family needs can all affect how much they accumulate for later life.
In India, these challenges can be compounded by the assumption that a husband’s pension, family savings or support from children will be sufficient. But family circumstances change. Nuclear households, rising healthcare costs and longer retirements make it important for women to understand their own financial position, even when household finances are shared.
This is the difference between saving and planning. Savings are important, but a retirement plan must also consider future expenses, income sources, healthcare, inflation and the possibility of living for decades after paid employment ends.
At a Glance
- Longer life expectancy can mean that women need to fund a longer retirement.
- Career breaks and lower earnings can reduce contributions to EPF, NPS and other long-term investments.
- Nomination, ownership and access to money are different things; women should understand how their financial assets are held.
- Healthcare, inflation and income after a spouse’s death need to be considered in retirement planning.
- A realistic plan begins with calculating personal expenses, available assets and the income gap that remains.
The Retirement Talk: A Reality Check
When Sunita sat down with her family last Diwali, the conversation turned to her brother’s retirement villa. The discussion made her reflect on her own financial future. Despite working for 25 years, she realised that she had never calculated how much money she would personally need through retirement.
“I always prioritised the children’s education and gold for my daughter,” she said. “I assumed the family pool would cover me, but I never calculated my own specific needs for a life that might last 30 years past retirement.”
Sunita’s concern was not that she had saved nothing. It was that she had not brought all her savings, expected expenses and future income together into one plan. She did not know whether her resources would be sufficient, how much healthcare might cost or what would happen if she had to manage financially on her own.
Her experience highlights an important point: retirement planning should be a personal exercise, even when it is part of a family’s broader financial plan.
Social Norms and Fragmented Incomes
In many households, men take the lead in managing investments while women handle day-to-day household expenses and savings. Women’s earnings may be treated as supplementary, particularly when they are balancing paid employment with caregiving responsibilities.
This can leave women with less visibility into investments, insurance, property ownership and retirement accounts. A woman may contribute substantially to household well-being without having a clear picture of the assets she owns, the income she can access independently or the funds available for her later years.
Career interruptions can create another difficulty. When women move in and out of paid employment, their income and retirement contributions may become irregular. Even if they return to work, fewer earning years can mean less time for investments to compound.
The answer is not necessarily to keep finances separate from a spouse. It is to ensure that both partners understand the household’s financial position and that each has clarity about personal assets, liabilities, retirement income and access to funds.
The Hidden Gaps: Caregiving and Retirement Accumulation
1. The caregiving penalty
Sunita took a five-year break to care for her ageing in-laws and later her newborn. During this period, she had no salary from her job and no employer-linked retirement contributions from that employment.
Such breaks can have consequences beyond the immediate loss of income. Contributions to the Employees’ Provident Fund (EPF) or the National Pension System (NPS) may stop or fall, depending on a woman’s employment and contribution arrangements. She may also miss salary increases and the opportunity to invest additional savings during those years.
The long-term effect is not limited to the money that was not contributed. It can also include the investment growth those contributions might have generated over time.
2. Lower accumulation after returning to work
Women returning to employment may choose flexible working arrangements to manage family responsibilities. In some cases, this can mean accepting lower pay, fewer opportunities for advancement or work with less access to retirement benefits.
That does not make flexibility the wrong choice. It does mean that retirement planning should account for its possible financial consequences. Reviewing savings regularly, increasing contributions when income permits and rebuilding an emergency fund after a career break can help women regain control of their long-term plans.
3. The cost of a longer retirement
A retirement plan that assumes a short period after employment ends may underestimate the resources required. Everyday expenses continue, while healthcare and support needs can change with age. Inflation also reduces the purchasing power of money over time.
Women should therefore assess whether their expected pension, investment income and other resources can support their needs over a sufficiently long retirement. The appropriate period and financial assumptions will depend on individual circumstances rather than a single universal rule.
Survivor Benefits, Ownership and Financial Protection
Women should understand what would happen to their finances if their spouse died or became unable to manage money. This is not simply an insurance question. It involves bank accounts, investments, property, pension arrangements, loans and the documents needed to access or transfer assets.
1. Understand ownership and nominations
Being named as a nominee does not necessarily mean being the legal owner of an asset during the account holder’s lifetime. Nomination rules and the legal treatment of different assets can vary. Women should understand how their bank accounts, investments, insurance policies and property are held, and what documentation would be required if a spouse died.
Where appropriate, review joint accounts, asset ownership, nominations, wills and the arrangements for accessing essential household funds. The objective is to reduce uncertainty at a difficult time, not merely to complete paperwork.
2. Review pension and insurance arrangements
Couples should check the terms of applicable pension schemes, annuities and insurance policies to understand what benefits may be payable to a surviving spouse. Benefits are not automatic in every case and depend on the scheme, policy and applicable rules.
Women should also know the difference between life insurance, which may provide a benefit on death, and retirement investments, which are intended to build or provide financial resources over time. Any decision to buy a product should follow an assessment of the actual need, costs, conditions and alternatives.
3. Protect the healthcare reserve
Medical expenses can put pressure on retirement savings, particularly when income is limited or a person is living alone. Review health insurance coverage, exclusions, waiting periods, deductibles and the availability of funds for expenses that a policy may not cover.
A separate healthcare reserve can be useful, but its appropriate size depends on existing coverage, health needs, available assets and household circumstances. It should be considered alongside the overall retirement plan rather than treated as a substitute for insurance or other financial protection.
A Path to Success: Sunita’s Turnaround
Sunita decided to move from assumptions to a more deliberate plan. She started by reviewing her savings, retirement accounts, expected pension income and likely expenses. She then identified where she needed to strengthen her financial position.
1. Rebuild contributions and invest consistently
Sunita began directing a portion of her year-end bonuses towards long-term investments. Equity mutual funds were one option she considered for growth over a long horizon, while recognising that market-linked investments can fall in value and are not suitable for every time frame or risk tolerance.
Rather than assuming that higher returns would automatically make up for her career break, she reviewed how much she could realistically invest and how much time remained before retirement. Her contribution plan was based on her circumstances, not on a promise of a particular return.
2. Understand EPF and NPS before choosing products
Sunita reviewed the retirement benefits available through her employment and explored whether the National Pension System (NPS) fitted her needs. She considered the contribution rules, investment choices, charges, withdrawal conditions and the role the account could play in her overall retirement plan.
NPS Tier I and Tier II have different features. Tier II is a voluntary investment account, and tax treatment depends on the applicable rules and the investor’s circumstances; it should not be assumed to provide the same tax benefits as Tier I. Sunita therefore checked the relevant conditions before making a decision.
3. Follow the ‘self-first’ rule
Sunita arranged for her planned retirement contribution to be set aside before allocating the remainder of her income to household spending. This helped turn retirement saving from an occasional decision into a regular habit.
She also began discussing money more openly with her daughter, including the importance of understanding investments, insurance, account access and long-term financial commitments. The aim was not to put individual interests above family needs, but to ensure that financial security was not left to chance.
Turn Awareness into a Retirement Plan
Women at different stages of life will need different approaches. A younger woman may have several decades to save and invest, while someone approaching retirement may need to focus on the gap between expected income and expenses, liquidity and the protection of existing assets.
Start by listing current savings, EPF and NPS balances, investments, property interests, loans and expected pension income. Estimate essential and discretionary expenses, allowing for inflation and healthcare. Then identify the gap between likely resources and future needs.
The GreySmiles guide to starting retirement planning early explains why beginning early can help. For a more numbers-led assessment, the retirement corpus calculation guide can help you understand the relationship between retirement expenses and the savings required.
GreySmiles Calculators
How much might you need for retirement, and how could your savings support future expenses? Use the GreySmiles calculators to explore retirement-related financial questions and test different assumptions. The results are illustrative planning estimates, not guarantees of future returns or personalised financial advice.
As part of the review, women should also check whether they can access their financial accounts independently, understand the benefits available to them and know whom to contact if a claim or pension benefit needs to be processed. Where legal, tax or investment decisions are complex, qualified professional guidance may be useful.
The GreySmiles Take
Retirement security should not depend on assumptions about who will provide support later in life. Women can plan jointly with their families while still understanding their own assets, income and financial needs. The first step is not necessarily to invest more; it is to know where you stand, identify the gaps and build a realistic plan to address them.
Conclusion
For women, retirement planning is about more than accumulating a large corpus. It is about having sufficient resources, clarity over financial assets and the ability to meet future needs with confidence. Career breaks, lower earnings and caregiving responsibilities can make this more challenging, but recognising those challenges early creates an opportunity to plan.
Sunita’s experience is a reminder that saving and planning are not the same. Regular contributions, informed investment choices, an understanding of pension and survivor benefits, healthcare preparation and access to financial information can all strengthen long-term security.
As Sunita began telling her daughter, retirement is a family conversation, but personal financial security cannot be left entirely to the family. Every woman deserves to know what she has, what she may need and how she intends to bridge the gap.
Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.