
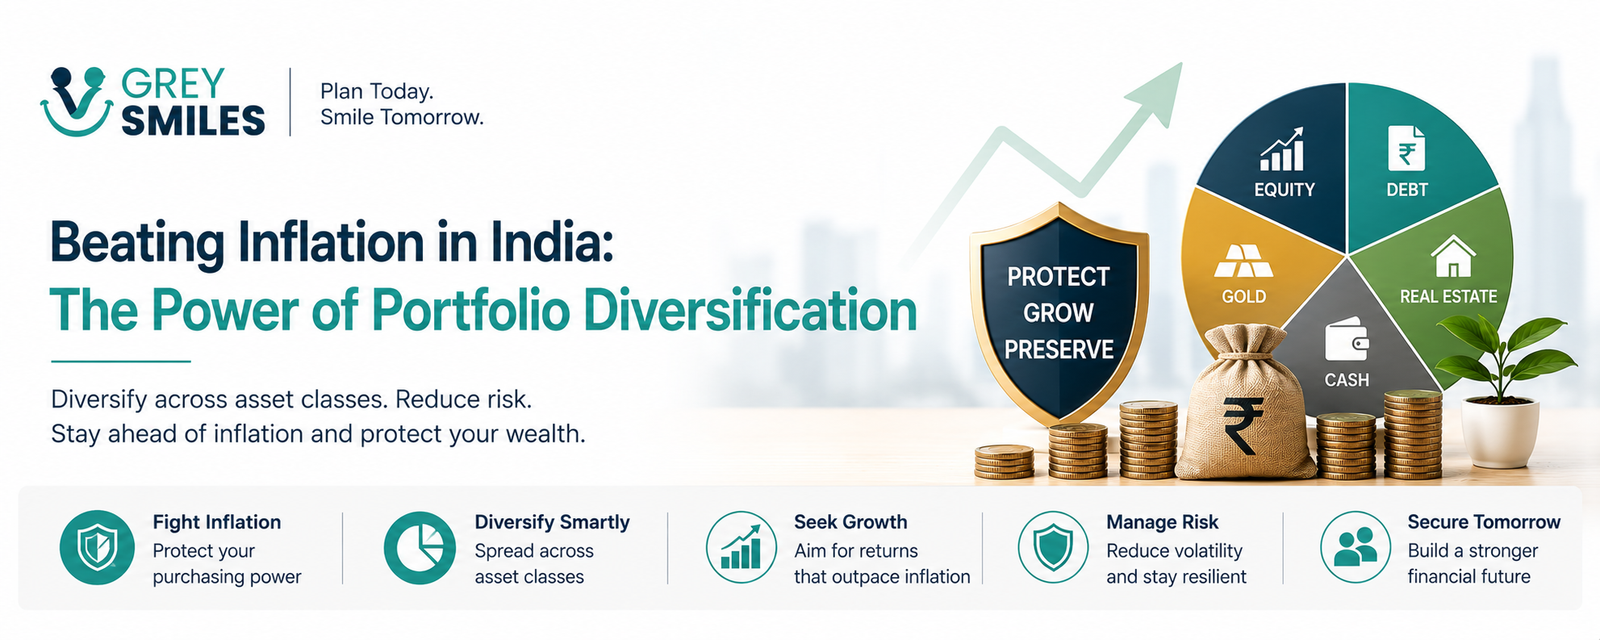
Portfolio diversification can help protect purchasing power and manage inflation risk over the long term.
In an era of persistent macroeconomic uncertainty, safeguarding your hard-earned capital against rising prices requires a deliberate financial strategy. This comprehensive guide explores how inflation impacts long-term wealth in India and how strategic asset allocation can preserve your purchasing power.
At a Glance: Beating Inflation Through Diversification
- Inflation reduces purchasing power: Money that does not grow at least broadly in line with inflation can lose purchasing power over time.
- Diversification matters: Spreading capital across equities, debt, gold, real estate and other assets can reduce concentration risk.
- Growth assets can help: Equities and selected real assets can provide long-term growth that has the potential to outpace inflation.
- Debt provides stability: Fixed-income investments can provide capital preservation and predictable cash flows within a diversified portfolio.
- Gold can diversify: Gold has historically acted as a store of value during periods of geopolitical and currency uncertainty.
- Global exposure adds another layer: International assets can reduce reliance on a single domestic economic cycle.
- There is no universal allocation: The right portfolio depends on your risk tolerance, investment horizon and financial goals.
Article Quick-Nav: In an era characterized by economic unpredictability, inflation stands out as a formidable adversary for savers and investors alike. Jump directly to key sections below:
- Understanding Inflation in the Indian Context
- The Strategic Need for Diversification
- Historical CAGR Performance Across Asset Classes (2003–2023)
- Building a Diversified Investment Portfolio in India
In an era characterized by economic unpredictability, inflation stands out as a formidable adversary for savers and investors alike. In India, where inflation can fluctuate significantly due to fiscal policy decisions, domestic supply constraints, and shifting global trade dynamics, adopting robust wealth management strategies is imperative. To explore actionable strategies for managing dynamic portfolios, consult the Grey Smiles Guide to Strategic Asset Allocation.
The global economy has weathered multiple macroeconomic headwinds since 2020—ranging from the COVID-19 pandemic during 2020–2021, the Galwan Valley border standoff, the Russia-Ukraine conflict, ongoing geopolitical unrest in the Middle East, to emerging global trade and tariff friction. These market disruptions underscore why relying on a single asset class or traditional savings product exposes investors to substantial purchasing power erosion.
One of the most proven defense mechanisms against market turbulence and inflationary pressure is multi-asset investment diversification. By structuring a well-balanced portfolio, investors can mitigate risks while remaining positioned to achieve inflation-beating real returns over the long term.
The GreySmiles Thumb Rule
Do not try to beat inflation by chasing the highest-returning asset every year. A better approach is to build a portfolio where growth, stability, diversification and liquidity work together, and where the investment mix matches your time horizon and risk tolerance.
Understanding Inflation in the Indian Context
The Reserve Bank of India (RBI) maintains a target inflation rate of around 4%. However, periods of monetary policy adjustment and shifting domestic demand often cause inflation to fluctuate outside this central band. Understanding how structural inflation damages long-term compounding is essential; for a deep dive on how inflation affects long-term retirement security, read Grey Smiles on Inflation and the Indian Wealth Gap.
Understanding historical context is vital. Between 2010 and 2020, India saw substantial variations in inflation rates, peaking at over 10% in certain years. During such periods, traditional investment avenues such as fixed deposits and savings accounts—which frequently yield interest rates lower than prevailing inflation—lead directly to negative real returns.
For someone planning for retirement, this distinction between nominal and real returns becomes particularly important. A portfolio may appear to be growing in rupee terms while its actual purchasing power is being eroded by inflation.
The Need for Diversification
Investment diversification involves spreading capital across distinct, non-correlated asset classes to lower overall portfolio risk while capturing potential market gains. In India’s rapidly evolving economy, diversification is no longer just a defensive tactic—it is a necessity for long-term wealth survival. Learn how early financial independence movements leverage diversification in The FIRE Movement in India by Grey Smiles.
Why Diversification Matters
Risk Mitigation: Allocating capital across equities, debt instruments, gold, real estate, and mutual funds buffers a portfolio against sector-specific downturns. Equities may thrive during periods of robust economic expansion, whereas fixed-income assets provide safety during market corrections.
Inflation Hedging: Certain tangible and growth-oriented assets naturally adjust upward during inflationary cycles. Commercial real estate and equities—particularly companies with strong pricing power that can pass input costs to consumers—act as natural hedges. Historically, gold has also served as a reliable store of value during currency devaluation.
Access to High-Growth Themes: Diversifying into emerging sectors—such as technology, renewable energy, manufacturing, and healthcare—offers significant capital appreciation potential. Sector-focused mutual funds or Exchange-Traded Funds (ETFs) allow investors to target these growth areas directly.
Global Diversification: As Indian markets become increasingly interconnected with global market cycles, investing in international assets through global mutual funds or ETFs reduces reliance on domestic economic cycles while capitalizing on growth in overseas markets.
Historical CAGR of Major Indian Asset Classes (2003–2023)
To better understand how each asset class has performed relative to inflation over the last two decades, here are the Compound Annual Growth Rates (CAGR) for major investment avenues in India from 2003 to 2023:
Historical CAGR Performance Across Asset Classes
| Asset Class | Benchmark / Representative Instrument | 20-Year CAGR (2003–2023) | Role in Inflation Protection |
|---|---|---|---|
| Equities | NIFTY 50 Index | ~12% – 14% | High long-term growth potential; consistently outpaces headline inflation over extended horizons. |
| Mutual Funds (SIP) | Diversified Equity SIPs | ~12% – 15% | Rupee-cost averaging mitigates timing risk while building wealth through steady compounding. For market insights, see Why Equities are Essential by Grey Smiles. |
| Gold | Domestic Gold Prices | ~9% – 11% | Acts as a classic store of value and safe-haven hedge during periods of global geopolitical or currency instability. |
| Real Estate | Major Tier-1 Indian Cities | ~8% – 10% | Combines ongoing rental yield potential with physical asset capital appreciation. |
| Debt Instruments | Government Bonds & Fixed Income | ~7% – 8% | Offers capital preservation and steady cash flows. Read how to structure fixed income efficiently at Grey Smiles’ Fixed Income Laddering Guide. |
Note: Historical CAGR figures provide context, not a forecast. Past financial performance across asset classes does not guarantee future returns.
Building a Diversified Portfolio in India
Creating a diversified investment portfolio is not merely about spreading money randomly across different instruments; it requires a strategic approach grounded in personal risk tolerance, investment horizon, and target goals. Regulatory frameworks set by regulatory bodies such as SEBI provide investor protection and market transparency across retail instruments.
Key Pillars for an Inflation-Resilient Portfolio
1. Equities Allocation: Allocate a significant portion of your portfolio to equities, given their historical ability to outpace inflation over the long term. Focus on a mix of blue-chip stocks, mid-cap, and small-cap companies across various growth sectors.
2. Debt Instruments: While equities offer high upside, fixed-income securities like government bonds and corporate debt provide stability and regular income, acting as a crucial buffer during market downturns.
3. Gold and Commodities: Consider allocating a portion of your portfolio to paper gold formats like Sovereign Gold Bonds (SGBs) or Gold ETFs, which retain value during inflationary shocks and geopolitical conflicts.
4. Real Estate: Real estate investments provide both physical capital appreciation over long periods and inflation-adjusted rental income streams.
5. Mutual Funds & ETFs: For investors seeking instant diversification without the need for constant stock selection, diversified mutual funds and index ETFs offer professional management and broad sector exposure.
6. Systematic Investment Plans (SIPs): Investing fixed sums regularly via SIPs allows you to capitalize on market volatility through rupee-cost averaging, removing emotional bias from long-term wealth creation.
The GreySmiles Thumb Rule
Diversification should reduce your dependence on any one investment, sector or economic outcome. The goal is not to own everything, but to ensure that each major asset has a clear role in protecting purchasing power, providing stability or creating long-term growth.
For investors approaching retirement, this principle becomes even more important because the portfolio must balance inflation protection with the need for dependable income and liquidity. See our Guide to Strategic Asset Allocation for a broader look at how allocation can change with life stage.
Disclaimer: Past financial performance across asset classes is not a guarantee of future returns. Investors should evaluate their personal risk tolerance or consult a registered financial advisor prior to making investment decisions.
Frequently Asked Questions
1. Why is inflation a risk to long-term wealth?
Inflation reduces the purchasing power of money over time. If your investments grow more slowly than inflation, your wealth may increase in rupee terms but decline in real purchasing power.
2. How does diversification help protect against inflation?
Diversification spreads investments across different asset classes such as equities, debt, gold and real estate. Different assets can respond differently to inflation and economic conditions, helping reduce dependence on any one investment.
3. Which investments can help beat inflation in India?
Over long periods, equities and certain real assets have the potential to outpace inflation. Debt instruments can provide stability and income, while gold can provide diversification and act as a store of value during periods of economic or currency uncertainty.
4. Is gold a good hedge against inflation?
Gold has historically acted as a store of value and can provide diversification during periods of inflation, geopolitical uncertainty and currency instability. It should generally be considered as one component of a diversified portfolio rather than the entire strategy.
5. Should I invest only in equities to beat inflation?
Not necessarily. Equities can provide long-term growth, but they also carry significant volatility. A diversified portfolio can combine growth assets with debt, gold, cash and other investments according to your risk tolerance and investment horizon.
6. How should I build an inflation-resilient portfolio?
Start with your investment horizon, financial goals and risk tolerance. Then combine appropriate allocations to equities, debt, gold, real estate, mutual funds or ETFs and other suitable investments rather than relying on a single asset class.

Start the conversation
Share a helpful experience, ask a thoughtful question, or add another perspective for fellow readers.